Motisons Jewellers (MOTISONS) Q2 FY27 Profit Dives 43% as Costs Swamp Festive Sales
The jeweller's festive quarter saw revenue grow 8% but profit plummeted 43% year-on-year as total expenses surged by a third, squeezing margins.
Motisons Jewellers reported a 43% plunge in Q2 FY27 net profit despite an 8% rise in revenue. A 32.5% surge in total expenses, amid high gold prices and a tough market, sharply eroded profitability.
For Motisons Jewellers, the September quarter is the festive season's test. This year, the jeweller passed on the top line but failed on the bottom, revealing a business caught between rising costs and a consumer pullback.
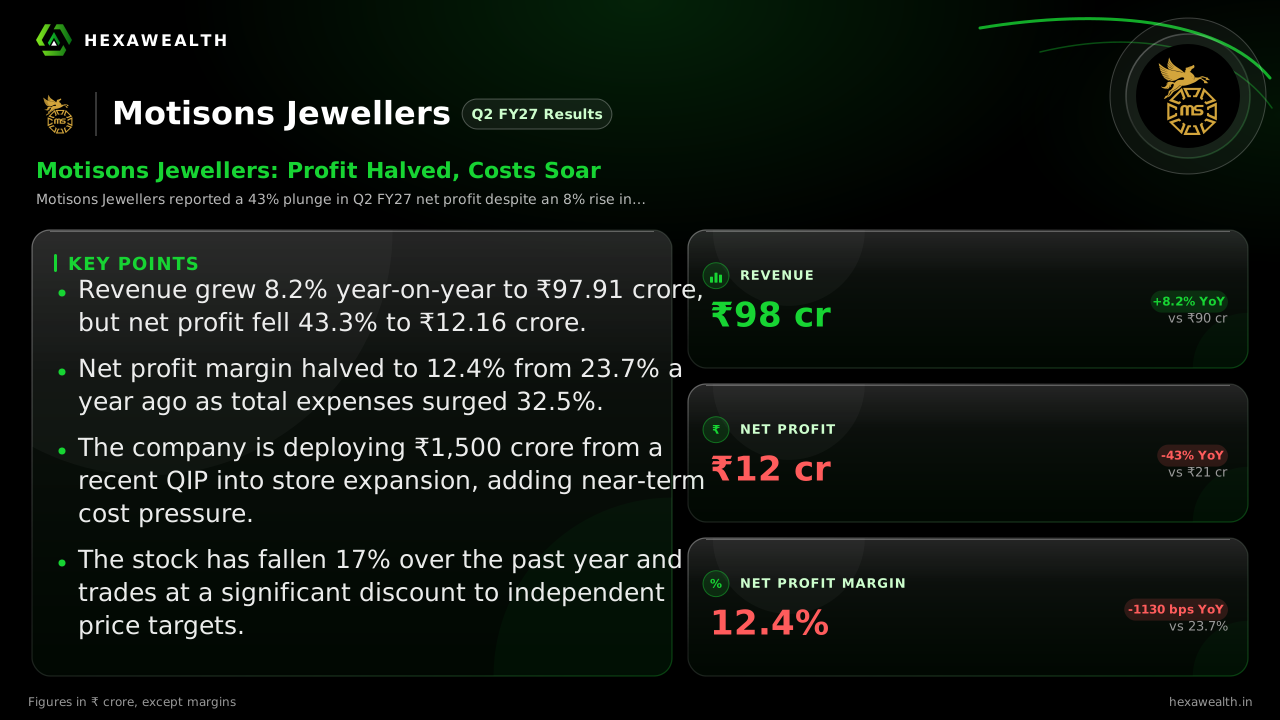
Revenue for Q2 FY27 came in at ₹97.91 crore, up 8.2% from a year ago. Net profit, however, fell 43.3% to ₹12.16 crore. The story is in the margins, which collapsed from 23.7% to 12.4% year-on-year as total expenses surged 32.5%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Period | Sep 2026 | Jun 2026 | Sep 2025 |
| Revenue (₹ Cr) | 97.91YoY +8.2% | 107.33 | 90.47 |
| Profit (₹ Cr) | 12.16YoY -43% | 11.05 | 21.43 |
| Net Profit Margin (%) | 12.4YoY -48% | 10.3 | 23.7 |
The Cost Squeeze That Ate the Profit
The sharp margin contraction was driven by a broad-based rise in expenses. Employee costs rose 13.6% year-on-year, but the bigger pressure came from other operational outlays as the company invested in its store footprint. According to a preview from StockWatch, Motisons is deploying ₹1,500 crore raised via a QIP into collections infrastructure, bringing new store leases and staff costs.
This spending hit just as the market turned. The World Gold Council reported India's gold demand fell 29% year-on-year in the September quarter, with jewellery volumes down 20%. High prices and a weak monsoon curbed rural spending, creating a tough environment for volume growth.
A Tough Road for the Growth Thesis
The quarter's modest revenue growth missed the Street's expectation for a print above ₹120 crore to sustain momentum. Independent research tracked by StockWatch had a net profit forecast of ₹11–14 crore, which Motisons met. However, the stock trades at a 30% discount to a ₹12-month target of ₹20, reflecting the execution risk priced in.
Analyst coverage is thin, but MarketsMOJO upgraded the stock to 'Hold' from 'Sell' just before the results, citing improved valuation. The key debate, per StockWatch, is whether the massive QIP-funded capex will drive collection growth or remain a persistent margin drag in the coming quarters.
Key Points
- Revenue grew 8.2% year-on-year to ₹97.91 crore, but net profit fell 43.3% to ₹12.16 crore.
- Net profit margin halved to 12.4% from 23.7% a year ago as total expenses surged 32.5%.
- The company is deploying ₹1,500 crore from a recent QIP into store expansion, adding near-term cost pressure.
- The stock has fallen 17% over the past year and trades at a significant discount to independent price targets.
Hexa Perspective
Motisons's quarter shows the limits of top-line growth in a squeezed consumer market. The 32.5% expense jump is structural, tied to a store expansion funded by fresh capital. For the growth thesis to hold, the new collections infrastructure must soon drive revenue velocity well beyond the single-digit pace seen this festive season. If gold prices stay high and rural demand weak, the cost absorption will be a multi-quarter challenge. Investors are weighing whether this capex is an investment in future scale or a burden on already-thinning returns.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.