Tarmat (TARMAT) Q2 FY27 Profit Jumps 91% as Infrastructure Execution Accelerates
The infrastructure contractor's quarterly profit nearly doubled year-on-year, driven by robust project execution and a sharp sequential margin recovery.
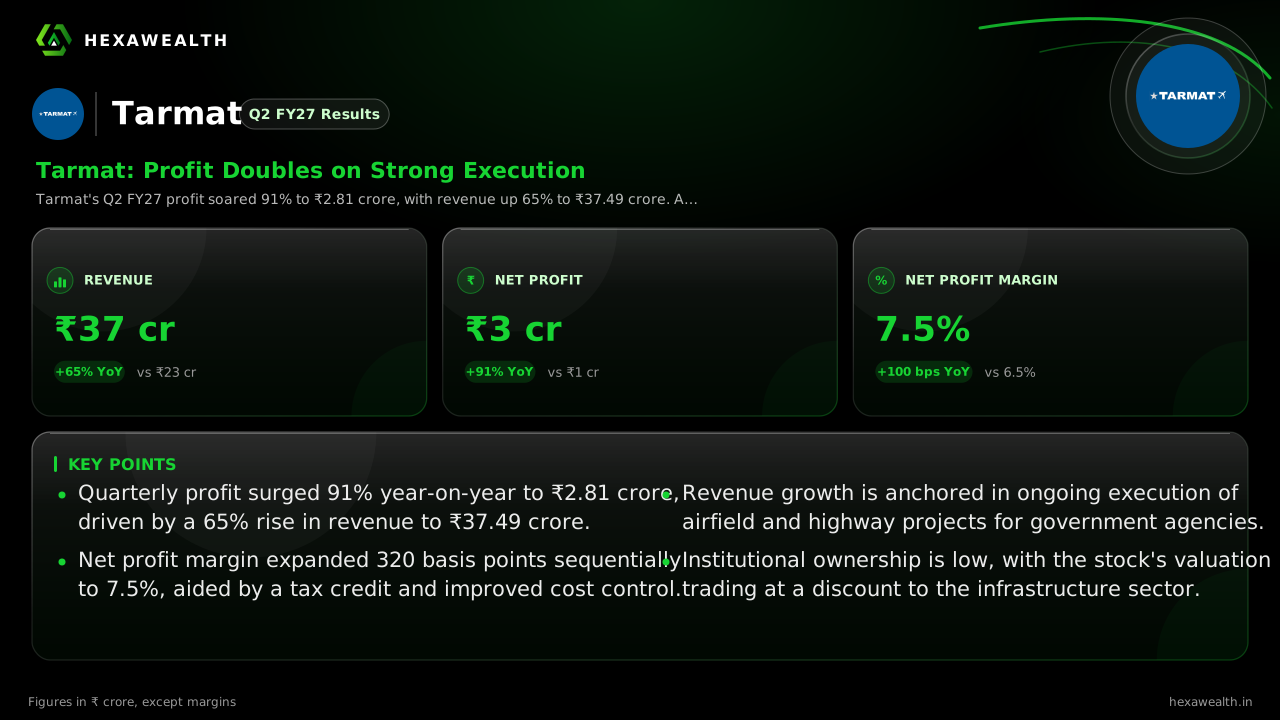
Tarmat's Q2 FY27 profit soared 91% to ₹2.81 crore, with revenue up 65% to ₹37.49 crore. A significant tax credit and improved operational efficiency drove a 320 bps sequential expansion in net profit margin.
For infrastructure contractors like Tarmat, the story is written in project execution. The September quarter saw that narrative accelerate, with revenue surging past year-ago levels as work on highways and airfields progressed.
Revenue for the quarter reached ₹37.49 crore, a 65% increase from last year. Profit grew even faster, rising 91% to ₹2.81 crore. The company's net profit margin expanded to 7.5%, a significant 320 basis point improvement from the previous quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 37.49YoY +65% | 35.81 | 22.67 |
| Profit (₹ Cr) | 2.81YoY +91% | 1.53 | 1.47 |
| Net Profit Margin (%) | 7.5YoY +15% | 4.3 | 6.5 |
The margin lift behind the profit surge
Sequential profit growth of 84% far outpaced the 5% rise in revenue. This was powered by a sharp margin recovery. A key factor was a tax credit of ₹0.43 crore, as reported in the company's filings, which provided a one-time boost to the bottom line.
Even excluding this, operating efficiency improved. Employee costs fell 2% quarter-on-quarter, while total expenses grew at a slower pace than revenue. The company's interest expense rose sharply, but this was offset by the stronger operational performance.
Execution drives the top line
The revenue jump stems from the core business of building runways and highways. A StockScans report notes the company is executing projects at airports in Mumbai, Cochin, Trichy and Tuticorin, alongside national highway jobs.
Government infrastructure spending remains a tailwind. Mordor Intelligence projects the Indian construction market to grow at a 7% CAGR through 2032, supported by public investment. This provides a steady pipeline for contractors like Tarmat.
A cautious market read
Despite the strong print, institutional interest remains muted. Data from FundTrackerIndia shows foreign portfolio investors hold just 1.81% of the company, with no mutual fund holdings as of September 2026.
The stock has returned 3.3% over the past year, underperforming the broader market. The price-to-earnings ratio of 20.3 trades at a 15% discount to the industry average, reflecting the market's wait-and-see approach.
Key Points
- Quarterly profit surged 91% year-on-year to ₹2.81 crore, driven by a 65% rise in revenue to ₹37.49 crore.
- Net profit margin expanded 320 basis points sequentially to 7.5%, aided by a tax credit and improved cost control.
- Revenue growth is anchored in ongoing execution of airfield and highway projects for government agencies.
- Institutional ownership is low, with the stock's valuation trading at a discount to the infrastructure sector.
Hexa Perspective
The quarter shows Tarmat can deliver strong growth when project execution ramps up. The sustainability of this momentum hinges on the order book, which the research indicates is filled with government contracts.
The margin expansion is encouraging but was flattered by a one-off tax credit. The core challenge remains translating top-line growth into consistent, high-quality earnings, especially with rising interest costs. Investors are pricing in this uncertainty, leaving room for re-rating if execution stays on track.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.