Methodhub Software (METHODHUB) Q4 FY26's Acquisitions Fuel 189% Revenue Surge, But Margins Narrow Sharply
The IT services firm's revenue more than doubled year-on-year in Q4 FY26, yet its net profit margin halved sequentially as costs from rapid inorganic growth weighed.
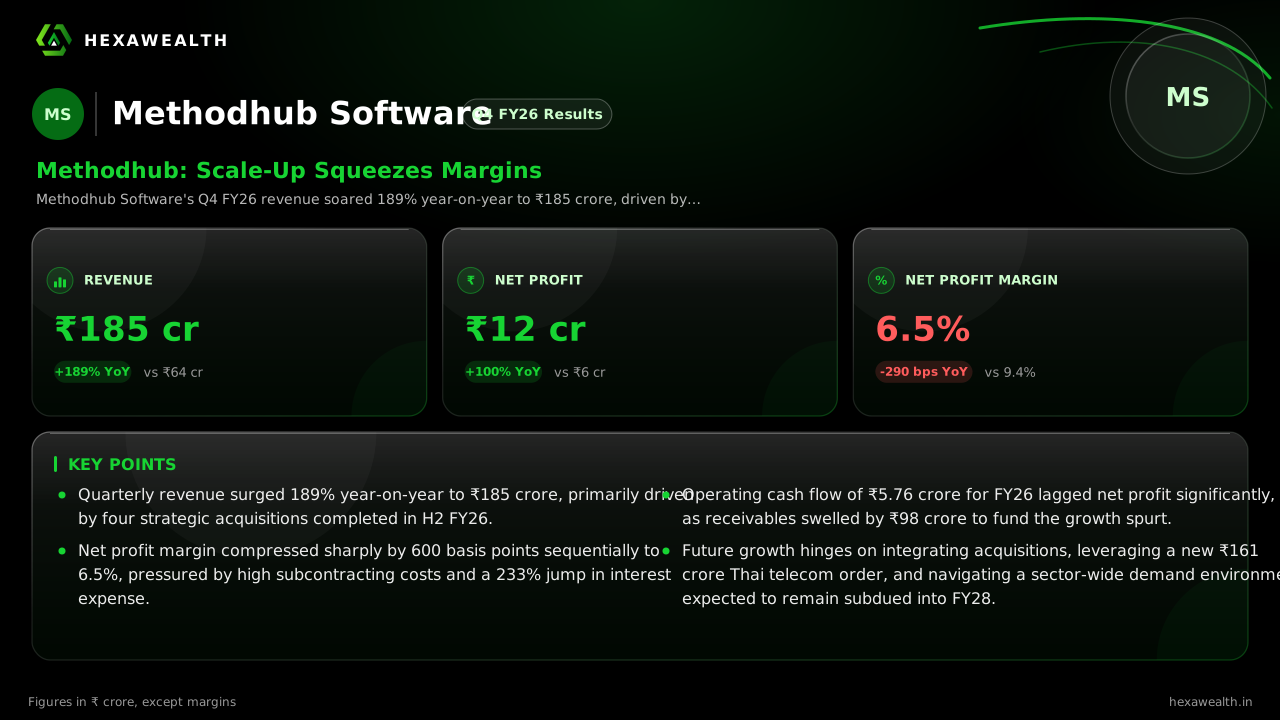
Methodhub Software's Q4 FY26 revenue soared 189% year-on-year to ₹185 crore, driven by four strategic acquisitions. However, net profit margin compressed by 600 basis points to 6.5% as interest and subcontracting costs surged with the expanded scale.
Methodhub Software's story this quarter is one of scale achieved, but at a price. The company transformed its size through four cross-border acquisitions in the latter half of the year, pushing revenue to a new high. Yet, the financials reveal the immediate cost of that ambition, with profitability taking a significant step back.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 64.0
- Revenue (₹ Cr), Q2 FY26: 80.0
- Revenue (₹ Cr), Q4 FY26: 185.0
- Net Profit (₹ Cr), Q4 FY25: 6.0
- Net Profit (₹ Cr), Q2 FY26: 10.0
- Net Profit (₹ Cr), Q4 FY26: 12.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 64.0
- Revenue (₹ Cr), Q2 FY26: 80.0
- Revenue (₹ Cr), Q4 FY26: 185.0
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q4 FY25: 6.0
- Net Profit (₹ Cr), Q2 FY26: 10.0
- Net Profit (₹ Cr), Q4 FY26: 12.0
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY25: 9.4
- Net Profit Margin (%), Q2 FY26: 12.5
- Net Profit Margin (%), Q4 FY26: 6.5
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 185.0YoY +189% | 64.0 |
| Net Profit (₹ Cr) | 12.0YoY +100% | 6.0 |
| Net Profit Margin (%) | 6.5YoY -31% | 9.4 |
Revenue for the March quarter leapt 189% from a year ago and more than doubled from the September quarter. Profit, however, grew at a far slower pace, rising 100% year-on-year and just 20% sequentially. The net profit margin fell sharply from 12.5% in Q2 to 6.5% in Q4.
The Cost of Buying Growth
The explosive revenue growth was almost entirely inorganic. MarketPing notes the company scaled up through four subsidiary acquisitions in H2 FY26, including stakes in US-based Leo Technology Ventures and Sewtech Inc. This brought in new revenue streams but also significantly higher direct costs.
Subcontracted services and materials now form nearly 66% of revenue. Interest expense also surged 233% from the previous quarter to ₹10 crore, reflecting the borrowed capital used for expansion. The result is a business that grew much larger, but with a thinner slice of each rupee reaching the bottom line.
Live Chart
· METHODHUB
(BSE)
ISIN: INE0QZR01017
Cash Flow and Concentration Risks
The balance sheet shows the strains of rapid expansion. Operating cash flow for the full year FY26 was a modest ₹5.76 crore, a fraction of the ₹31.84 crore net profit. This gap is tied to a ₹98 crore jump in receivables as the company extended credit to fuel growth.
Client concentration remains a key watchpoint. The company's investor presentation, cited by StockFin.ai, shows the top three customers accounted for 43.8% of FY26 revenue. While this brings large contracts, it also introduces dependency risk that investors must weigh against the growth narrative.
The Path Ahead
Management is betting on its acquired platform to drive future efficiency. The company is setting up nearshore centers in Mexico and Costa Rica, as per an Alfafinder report, to better serve North American clients. Its Thai subsidiary also secured a ₹161 crore telecom managed services contract valid until mid-2028, providing near-term visibility.
The broader IT services environment, however, is challenging. A BNP Paribas report summarized by IANS Live suggests demand recovery for mid-tier firms is being pushed to FY28, with pricing pressure and AI-driven disruption persisting. Methodhub's ability to improve margins will depend on integrating its acquisitions and managing costs in this tight market.
Key Points
- Quarterly revenue surged 189% year-on-year to ₹185 crore, primarily driven by four strategic acquisitions completed in H2 FY26.
- Net profit margin compressed sharply by 600 basis points sequentially to 6.5%, pressured by high subcontracting costs and a 233% jump in interest expense.
- Operating cash flow of ₹5.76 crore for FY26 lagged net profit significantly, as receivables swelled by ₹98 crore to fund the growth spurt.
- Future growth hinges on integrating acquisitions, leveraging a new ₹161 crore Thai telecom order, and navigating a sector-wide demand environment expected to remain subdued into FY28.
Hexa Perspective
Methodhub has executed a bold transformation, using acquisitions to achieve scale that would have taken years organically. The financial trade-off is now clear: spectacular revenue growth came with a steep decline in quarterly profitability and a strain on cash conversion.
The next phase is about proving this model can work. Investors are watching for signs that the company can hold pricing, improve working capital discipline, and extract operating leverage from its new size. Success would validate the acquisition spree; continued margin pressure would question its cost.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.