Kirloskar Oil Engines (KIRLOSENG) Q2 FY27 Profit Drops 18% as Cost Surge Outpaces Revenue Growth
The engine maker's revenue grew 17% year-on-year, but a sharp rise in raw material and operating expenses compressed margins and pushed profit down.
Kirloskar Oil Engines posted a 17% rise in Q2 FY27 revenue, but net profit fell 18% as total expenses surged 21.5%. The margin squeeze was driven by higher input costs, though management expects commodity pressure to moderate.
Kirloskar Oil Engines is pushing toward its ambitious Vision 2030, but the September quarter showed the cost of getting there. The company delivered strong top-line growth, yet profitability took a significant hit as expenses rose faster than sales.
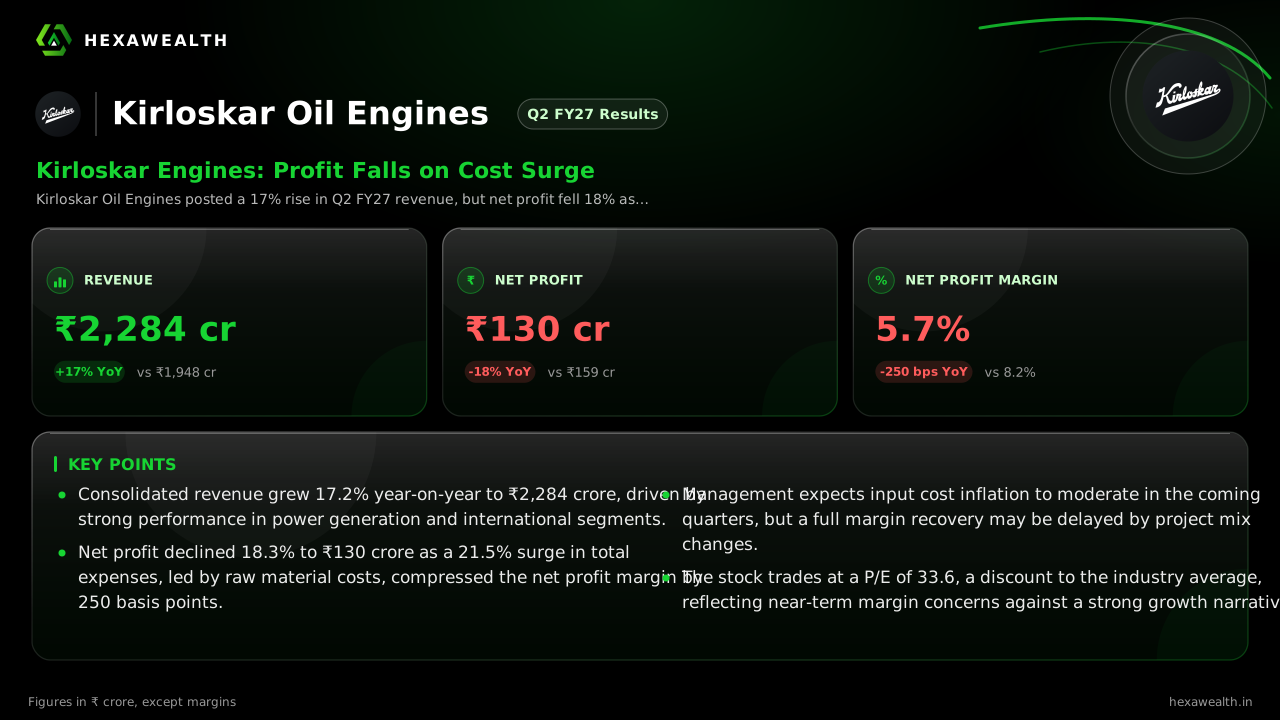
The numbers tell a story of divergence. Revenue climbed 17.2% year-on-year to ₹2,284 crore, a solid performance. Profit, however, fell 18.3% to ₹130 crore. The net profit margin contracted by 250 basis points to 5.7%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 2,284.0YoY +17% | 1,999.5 | 1,948.4 |
| Profit (₹ Cr) | 130.0YoY -18% | 111.1 | 159.2 |
| Net Profit Margin (%) | 5.7YoY -30% | 5.6 | 8.2 |
The Engine Ran Hot, But Costs Ran Hotter
The revenue growth was broad-based. According to IANS, the core B2B Power & Energy segment revenue rose 20% year-on-year, while the B2C Fluid Dynamics segment grew 28%. Standalone sales hit a record, led by a 50% jump in international business and 17% growth in Powergen, as per ScanX.
Yet, this demand did not translate to the bottom line. Total expenses surged 21.5% year-on-year, outpacing revenue growth. Autocar Professional reported this was driven by a sharp rise in raw material costs. The cost pressure was severe enough to push standalone EBITDA down 6% year-on-year, according to ScanX.
A Margin Squeeze With a Long Tail
Management, citing trends from its sister company Kirloskar Brothers, expects commodity cost pressure from steel and copper to moderate over the next few quarters. However, a full margin recovery may take longer. The company is also navigating a shift in its order mix toward lower-margin oil and gas projects.
The market looked past the profit drop, focusing on the robust revenue and long-term strategy. The stock closed at ₹1,802 on November 4, having delivered a 65% return over the past year. Analyst sentiment remains positive, with Simply Wall St noting a consensus 'Buy' rating and a median price target of ₹2,565.
Key Points
- Consolidated revenue grew 17.2% year-on-year to ₹2,284 crore, driven by strong performance in power generation and international segments.
- Net profit declined 18.3% to ₹130 crore as a 21.5% surge in total expenses, led by raw material costs, compressed the net profit margin by 250 basis points.
- Management expects input cost inflation to moderate in the coming quarters, but a full margin recovery may be delayed by project mix changes.
- The stock trades at a P/E of 33.6, a discount to the industry average, reflecting near-term margin concerns against a strong growth narrative.
Hexa Perspective
This quarter underscores the tension in Kirloskar Oil Engines' transition. The growth engine is firing, with record sales and strategic wins in data centers and defense. Yet, profitability is being sacrificed at the altar of input costs and strategic investments.
The path to its $2 billion revenue goal is clear, but the margin trajectory is less so. Investors are betting that operating leverage from new capacity and easing commodity prices will eventually bridge the gap. For now, the story is one of growth at a cost.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.