Honasa Consumer (HONASA) Q2 FY27 Profit Jumps 87% on Strong Brand Growth, But Margins Contract Sequentially
The Mamaearth parent posted its highest growth since listing, driven by younger brands, but a sequential profit dip points to rising costs.
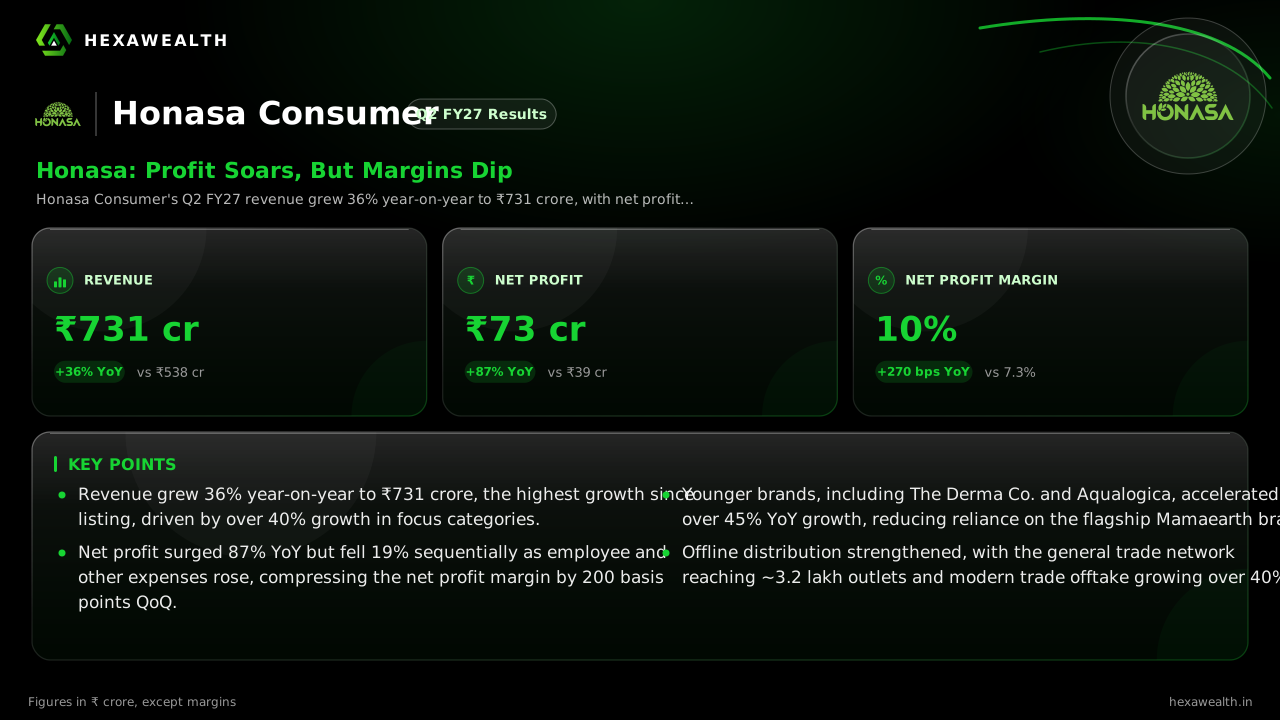
Honasa Consumer's Q2 FY27 revenue grew 36% year-on-year to ₹731 crore, with net profit surging 87%. However, both revenue and profit declined from the previous quarter, and the net profit margin contracted by 200 basis points.
Honasa Consumer’s multi-brand strategy is delivering its fastest growth since listing, but the path to profitability is showing new pressures. The September quarter saw revenue jump 36% year-on-year, powered by younger brands expanding at a blistering pace. Yet a sequential dip in both sales and profit reveals the cost of scaling this 'house of brands'.
The numbers tell a story of powerful year-on-year momentum tempered by quarterly moderation. Revenue reached ₹731.2 crore, while net profit nearly doubled to ₹73.2 crore. Compared to the June quarter, however, revenue slipped 3.3% and profit fell 19%, pulling the net profit margin down to 10% from 12%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 538.06
- Revenue (₹ Cr), Q3 FY26: 601.54
- Revenue (₹ Cr), Q4 FY26: 657.08
- Revenue (₹ Cr), Q1 FY27: 755.95
- Revenue (₹ Cr), Q2 FY27: 731.19
- Profit (₹ Cr), Q2 FY26: 39.23
- Profit (₹ Cr), Q3 FY26: 50.20
- Profit (₹ Cr), Q4 FY26: 69.44
- Profit (₹ Cr), Q1 FY27: 90.45
- Profit (₹ Cr), Q2 FY27: 73.25
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 538.06
- Revenue (₹ Cr), Q3 FY26: 601.54
- Revenue (₹ Cr), Q4 FY26: 657.08
- Revenue (₹ Cr), Q1 FY27: 755.95
- Revenue (₹ Cr), Q2 FY27: 731.19
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 39.23
- Profit (₹ Cr), Q3 FY26: 50.20
- Profit (₹ Cr), Q4 FY26: 69.44
- Profit (₹ Cr), Q1 FY27: 90.45
- Profit (₹ Cr), Q2 FY27: 73.25
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26: 7.3
- Net Profit Margin (%), Q3 FY26: 8.3
- Net Profit Margin (%), Q4 FY26: 10.6
- Net Profit Margin (%), Q1 FY27: 12.0
- Net Profit Margin (%), Q2 FY27: 10.0
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 731.19YoY +36% | 755.95 | 538.06 |
| Profit (₹ Cr) | 73.25YoY +87% | 90.45 | 39.23 |
| Net Profit Margin (%) | 10.0YoY +37% | 12.0 | 7.3 |
Why the profit engine cooled off
Sequential profit fell faster than revenue because costs rose in key areas. Employee benefit expenses jumped over 10% quarter-on-quarter, according to the company's financials. Other expenses, a large bucket, also remained elevated. This squeezed the bottom line even as total expenses dipped slightly.
The pressure is not from a lack of demand. Management told Businessworld that focus categories grew over 40% and now make up more than 80% of revenue. Underlying volume growth was a robust 31.3%, indicating consumers are buying more, not just paying higher prices.
The younger brands are now the growth drivers
The star performers are the newer labels. Brands like The Derma Co., Aqualogica, and Dr. Sheth’s grew over 45% year-on-year, as reported by The Economic Times. The Derma Co. saw its brand search interest hit an all-time high. This shift is crucial as Honasa successfully builds a portfolio beyond its flagship Mamaearth, which grew at a high-teens rate.
Live Chart
· HONASA
(BSE)
ISIN: INE0J5401028
Offline expansion is fueling this growth. The general trade network now spans approximately 3.2 lakh outlets, and modern trade offtake grew more than 40% year-on-year. The company is converting digital brand love into physical shelf presence.
The market's muted reaction and the road ahead
The stock traded marginally higher after the results, a calm reaction to stellar yearly growth. Investors may be weighing the rich valuation—a P/E of 48.5 against an industry average of 45.9—against the sequential margin pressure. Management's focus remains on scaling brands and innovation, with recent launches like Mamaearth's Kulhad Chai Lip Balm highlighting this push.
The quarter confirms Honasa's growth story is intact and broadening. The coming quarters will test its ability to manage the cost side of this expansion, turning top-line surges into consistent bottom-line delivery.
Key Points
- Revenue grew 36% year-on-year to ₹731 crore, the highest growth since listing, driven by over 40% growth in focus categories.
- Net profit surged 87% YoY but fell 19% sequentially as employee and other expenses rose, compressing the net profit margin by 200 basis points QoQ.
- Younger brands, including The Derma Co. and Aqualogica, accelerated with over 45% YoY growth, reducing reliance on the flagship Mamaearth brand.
- Offline distribution strengthened, with the general trade network reaching ~3.2 lakh outlets and modern trade offtake growing over 40%.
Hexa Perspective
The quarter solidifies Honasa's transition from a single-brand wonder to a multi-brand platform, a critical de-risking of its model. The 31% volume growth is particularly encouraging, showing real consumer pull. Yet, the sequential margin contraction is a clear signal that scaling multiple brands simultaneously is costly. The premium valuation demands that these costs are temporary investments for future leverage, not a new normal. Success now hinges on proving that the marketing and employee spend behind The Derma Co. and other young brands will yield similar profitability to Mamaearth's mid-teens EBITDA margin.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.