GR Infraprojects (GRINFRA) Q2 FY27 Profit Jumps 53% YoY Despite Sequential Dip
The road EPC major posted robust yearly growth but saw revenue and profit dip from the previous quarter, with a massive order book providing future visibility.
GR Infraprojects reported a 53% yearly jump in net profit for Q2 FY27, though revenue and earnings declined sequentially. The company's order book stands at a robust ₹24,577 crore, but working capital days have risen significantly.
For road builders, the story is written in the order book and the monsoon. GR Infraprojects entered the September quarter with a strong backlog but faced the typical seasonal slowdown, delivering a quarter of robust yearly growth shadowed by a sequential dip.
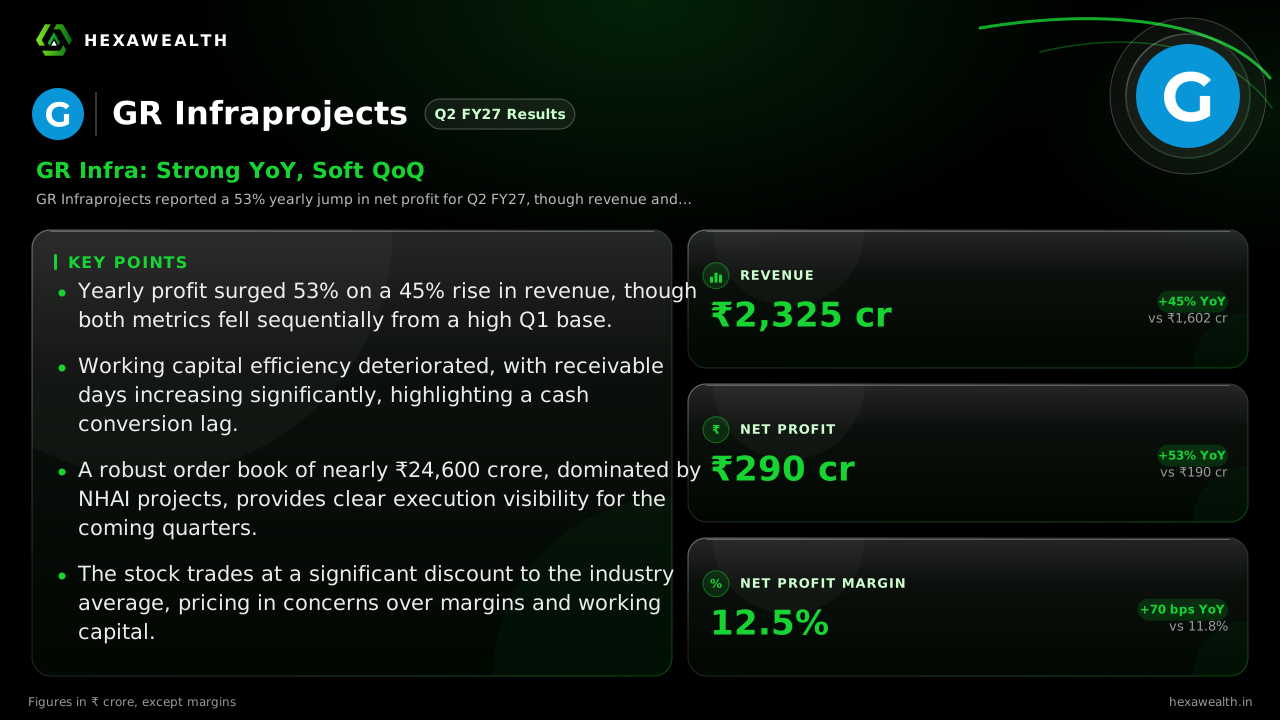
Consolidated revenue for Q2 FY27 was ₹2,325 crore, a 45% jump from a year ago. Net profit rose 53% to ₹290 crore. Sequentially, both figures softened, with revenue down 16.5% and profit down 18.9% from a strong June quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 2,325.42YoY +45% | 2,784.11 | 1,602.14 |
| Profit (₹ Cr) | 290.30YoY +53% | 357.79 | 189.56 |
| Net Profit Margin | 12.5%YoY +5.9% | 12.9% | 11.8% |
The yearly growth was supported by strong execution across projects. According to the company's investor presentation, consolidated revenue from operations grew 45.1% year-on-year. The quarterly decline aligns with management's Q1 commentary, which noted that construction activity typically slows until November due to monsoon rains.
The cash catch behind the growth
A key concern emerging from the quarter is working capital. Reports from Multibagg.ai and ScanX.trade note that net working capital days ballooned to 152 in September 2026 from 98 a year earlier. Receivable days alone jumped to 120 from 80. This suggests the impressive revenue growth has not yet translated into proportional cash inflows, potentially tying up capital.
A full pipeline for the dry months
The primary buffer against quarterly volatility is the order book. As per the investor presentation, it stood at ₹24,577 crore as of September 30, providing over two years of revenue visibility at current run rates. The National Highways Authority of India (NHAI) accounts for 63% of this backlog. A fresh mega-project, the Agra-Gwalior Greenfield road with a total cost of ₹4,263 crore, also commenced in September, as noted by StockFin.ai.
Management has guided for 15-20% revenue growth for the full year FY27, as reported in the Q1 earnings call. With the monsoon receding and these large projects ramping up, the second half is expected to drive that growth. The company's valuation, at a P/E of 8.6 against an industry average of 22.5, reflects market skepticism around execution and cash flow conversion.
Key Points
- Yearly profit surged 53% on a 45% rise in revenue, though both metrics fell sequentially from a high Q1 base.
- Working capital efficiency deteriorated, with receivable days increasing significantly, highlighting a cash conversion lag.
- A robust order book of nearly ₹24,600 crore, dominated by NHAI projects, provides clear execution visibility for the coming quarters.
- The stock trades at a significant discount to the industry average, pricing in concerns over margins and working capital.
Hexa Perspective
The quarter presents a classic infrastructure tale: strong backlog-driven growth on paper, tempered by the reality of seasonal execution and working capital strain. The 53% yearly profit leap is impressive but set against a soft prior-year quarter. The sequential dip was anticipated. The real test is whether the company can convert its massive order book into cash-efficient execution as projects accelerate post-monsoon. The widening working capital gap is the figure to watch; it could pressure the balance sheet if not reversed in the coming quarters. Investors are weighing the clear revenue visibility against these cash flow challenges.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.