Gallard Steel (GALLARD) Q2 FY27 Profit Jumps 40% as Margins Widen
Gallard Steel's Q2 FY27 profit surged 40% year-on-year, driven by higher volumes and operating leverage, with margins expanding to a multi-quarter high.
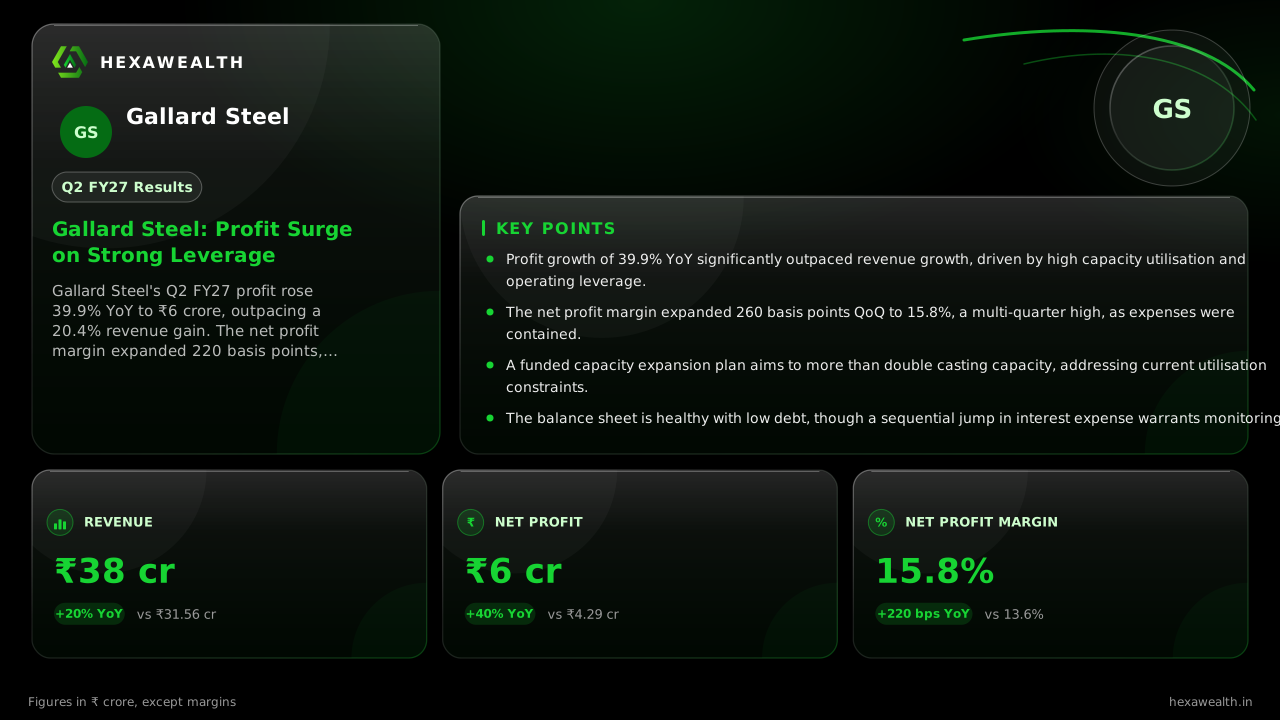
Gallard Steel's Q2 FY27 profit rose 39.9% YoY to ₹6 crore, outpacing a 20.4% revenue gain. The net profit margin expanded 220 basis points, reflecting strong operating leverage as the company runs at near-full capacity.
For a capital-intensive manufacturer like Gallard Steel, the story is told in the spread between revenue growth and profit growth. The September quarter delivered a clear message: with facilities running near their limit, every extra rupee of sales is dropping more to the bottom line.
Revenue rose 20.4% year-on-year to ₹38 crore, while profit leapt 39.9% to ₹6 crore. The net profit margin widened sharply to 15.8%, up 260 basis points from the previous quarter. This performance builds on a strong sequential trend.
Revenue & profit
Revenue (₹ Cr.)
Profit (₹ Cr.)
- Revenue (₹ Cr.), Q4 FY25: 32.11
- Revenue (₹ Cr.), Q2 FY26: 31.56
- Revenue (₹ Cr.), Q4 FY26: 36.48
- Revenue (₹ Cr.), Q2 FY27: 38.0
- Profit (₹ Cr.), Q4 FY25: 3.13
- Profit (₹ Cr.), Q2 FY26: 4.29
- Profit (₹ Cr.), Q4 FY26: 4.81
- Profit (₹ Cr.), Q2 FY27: 6.0
Revenue (₹ Cr.)
- Revenue (₹ Cr.), Q4 FY25: 32.11
- Revenue (₹ Cr.), Q2 FY26: 31.56
- Revenue (₹ Cr.), Q4 FY26: 36.48
- Revenue (₹ Cr.), Q2 FY27: 38.0
Profit (₹ Cr.)
- Profit (₹ Cr.), Q4 FY25: 3.13
- Profit (₹ Cr.), Q2 FY26: 4.29
- Profit (₹ Cr.), Q4 FY26: 4.81
- Profit (₹ Cr.), Q2 FY27: 6.0
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY25: 9.7
- Net Profit Margin (%), Q2 FY26: 13.6
- Net Profit Margin (%), Q4 FY26: 13.2
- Net Profit Margin (%), Q2 FY27: 15.8
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr.) | 38.0YoY +20% | 31.56 |
| Profit (₹ Cr.) | 6.0YoY +40% | 4.29 |
| Net Profit Margin (%) | 15.8YoY +16% | 13.6 |
The leverage of a tight ship
The profit surge was powered by operating leverage. According to a report from mcapital.in, the company's existing manufacturing facilities were operating at about 98% utilisation in the prior period. With total expenses nearly flat quarter-on-quarter despite higher sales, the incremental revenue flowed directly to profit.
This efficiency is critical as the company prepares for expansion. A ₹37.5 crore preferential issue from November 2025 is funding a major capacity increase. The plan is to expand casting capacity from 2,400 MT to 6,100 MT per annum.
Funding growth without strain
While interest expense rose 42.9% sequentially, the balance sheet remains robust. The debt-to-equity ratio is a conservative 0.26. Research by Minerva Capital, cited by mcapital.in, notes that a significant portion of the raised funds is still held in fixed deposits, providing liquidity for the planned capex.
Live Chart
· GALLARD
(BSE)
ISIN: INE0BUQ01012
The company has not issued formal guidance, but the strong first half sets a high baseline. Analysis by Minerva Capital suggests FY27 revenue could grow 15-22% and net profit 35-50% from the FY26 base.
Key Points
- Profit growth of 39.9% YoY significantly outpaced revenue growth, driven by high capacity utilisation and operating leverage.
- The net profit margin expanded 260 basis points QoQ to 15.8%, a multi-quarter high, as expenses were contained.
- A funded capacity expansion plan aims to more than double casting capacity, addressing current utilisation constraints.
- The balance sheet is healthy with low debt, though a sequential jump in interest expense warrants monitoring.
Hexa Perspective
This quarter confirms Gallard Steel's ability to convert top-line growth into superior earnings when running at full tilt. The margin expansion is a function of scale, not a one-off, and is sustainable as long as utilisation stays high. The coming test is execution: the planned capacity ramp must be timely and efficient to absorb the capital deployed. For now, the story is one of a tightly-run operation harvesting the rewards of demand in its core railway components market.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.