Chemplast Sanmar (CHEMPLASTS) Q2 FY27's Loss Shrinks 89% as Revenue Jumps 28%
The specialty chemicals maker posted a sharp reduction in its quarterly loss, driven by strong specialty segment demand and improved operating margins.
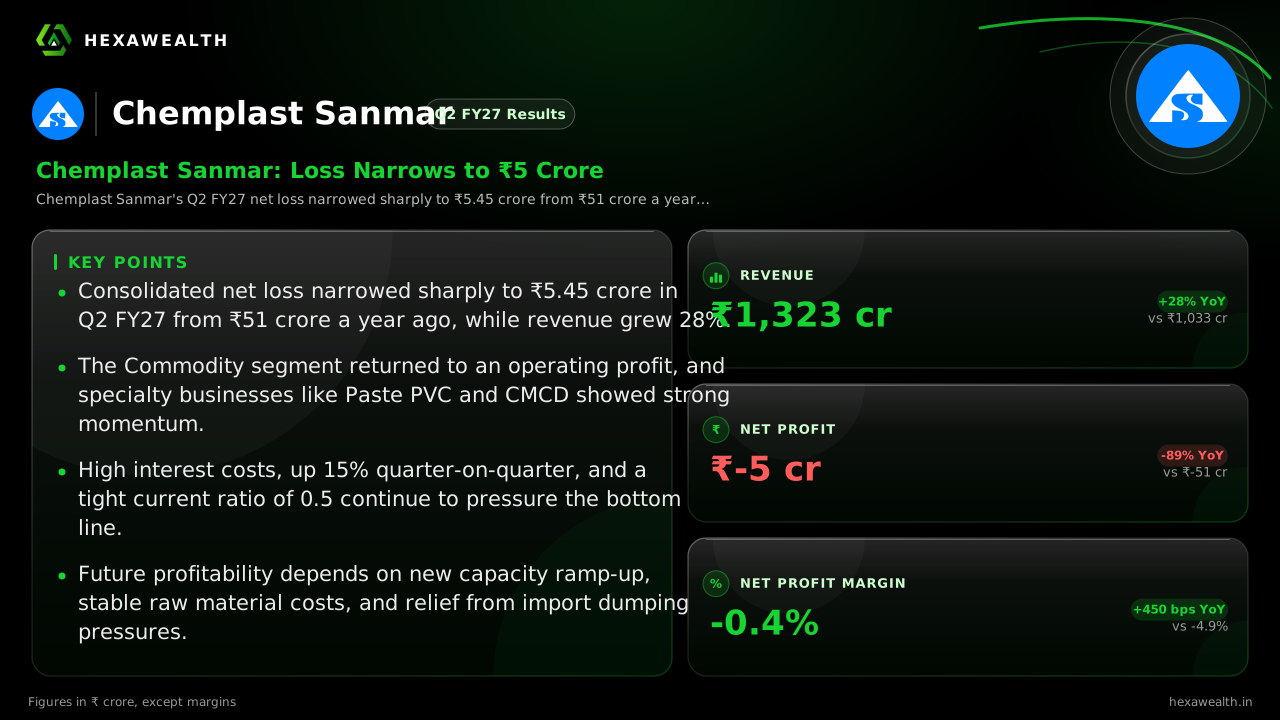
Chemplast Sanmar's Q2 FY27 net loss narrowed sharply to ₹5.45 crore from ₹51 crore a year ago. Revenue grew 28% to ₹1,323 crore, supported by robust demand in its Paste PVC and custom manufacturing divisions.
For Chemplast Sanmar, a quarter defined by a painful raw material squeeze has finally shown signs of easing. The specialty chemicals maker reported a consolidated net loss of ₹5.45 crore for Q2 FY27, a dramatic 89% improvement from the ₹51 crore loss a year ago, as a 28% surge in revenue began to translate down the income statement.
Revenue climbed to ₹1,323 crore, up from ₹1,033 crore in Q2 FY26 and 18% higher than the previous quarter. The company's net loss margin improved to -0.4%, a significant recovery from -15.6% in Q1 FY27 and -4.9% a year ago.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 1,323.21 | 1,124.66 |
| Profit (₹ Cr) | -5.45 | -175.58 |
| Net Profit Margin (%) | -0.4 | -15.6 |
A Tale of Two Segments
The recovery was led by its specialty chemicals business. According to a scanx.trade report, the Commodity segment turned an operating profit of ₹6.64 crore, a sharp reversal from a loss a year earlier. The Specialities segment, which includes Paste PVC and custom chemicals, also narrowed its loss significantly.
Management, in an investor presentation cited by blog.perivis.com, highlighted robust Paste PVC demand and growth in the Custom Manufactured Chemicals Division (CMCD). However, the Suspension PVC and value-added chemicals businesses continued to face pressure from soft demand and Chinese import dumping.
The Burden of Borrowing
Despite the operational improvement, a rising interest bill weighed on the final result. Interest expense grew 13% year-on-year and 15% sequentially to ₹68 crore. This reflects the company's leverage, with a debt-to-equity ratio of 1.11 as of June 2026, according to sectoralpha.in data.
The balance sheet shows strain, with a current ratio of 0.5. While the company reduced net debt by ₹203 crore in the first half, servicing this debt remains a significant drag on profitability as it inches toward breakeven.
The Path to Profitability
The outlook hinges on the ramp-up of high-margin projects. Management expects its 14,000-tonne R-32 refrigerant gas capacity to be fully online by FY27-end, with initial sales already recorded. A 7 KTPA debottlenecking at the Cuddalore Paste PVC plant, scheduled for October 2026, should further support volumes.
Analyst sentiment remains cautiously constructive. Data from sharpely.in shows a median 12-month price target of ₹265, implying a 24% upside from recent levels, with all three covering analysts maintaining a Buy or Strong Buy rating.
Key Points
- Consolidated net loss narrowed sharply to ₹5.45 crore in Q2 FY27 from ₹51 crore a year ago, while revenue grew 28%.
- The Commodity segment returned to an operating profit, and specialty businesses like Paste PVC and CMCD showed strong momentum.
- High interest costs, up 15% quarter-on-quarter, and a tight current ratio of 0.5 continue to pressure the bottom line.
- Future profitability depends on new capacity ramp-up, stable raw material costs, and relief from import dumping pressures.
Hexa Perspective
The quarter marks a clear inflection from the deep losses of Q1, but not yet a turnaround. The core story is operating leverage: revenue growth finally outpacing fixed costs, pulling EBITDA sharply positive. Yet, the journey from an ₹8.5 crore pre-tax loss to sustained net profit is blocked by a ₹68 crore quarterly interest wall.
Investors are betting that specialty chemical expansions will generate enough cash to chip away at that wall. For now, the stock's 40% decline over the past year prices in the past pain, while the 28% revenue growth offers a glimpse of the potential reward if execution holds.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.