Axel Polymers (AXELPOLY) Q1 FY27 Swings to Profit as Revenue Jumps 39%
Axel Polymers posted a net profit of ₹0.18 crore in Q1 FY27, reversing a loss from the prior quarter, driven by a sharp 38.5% rise in revenue.
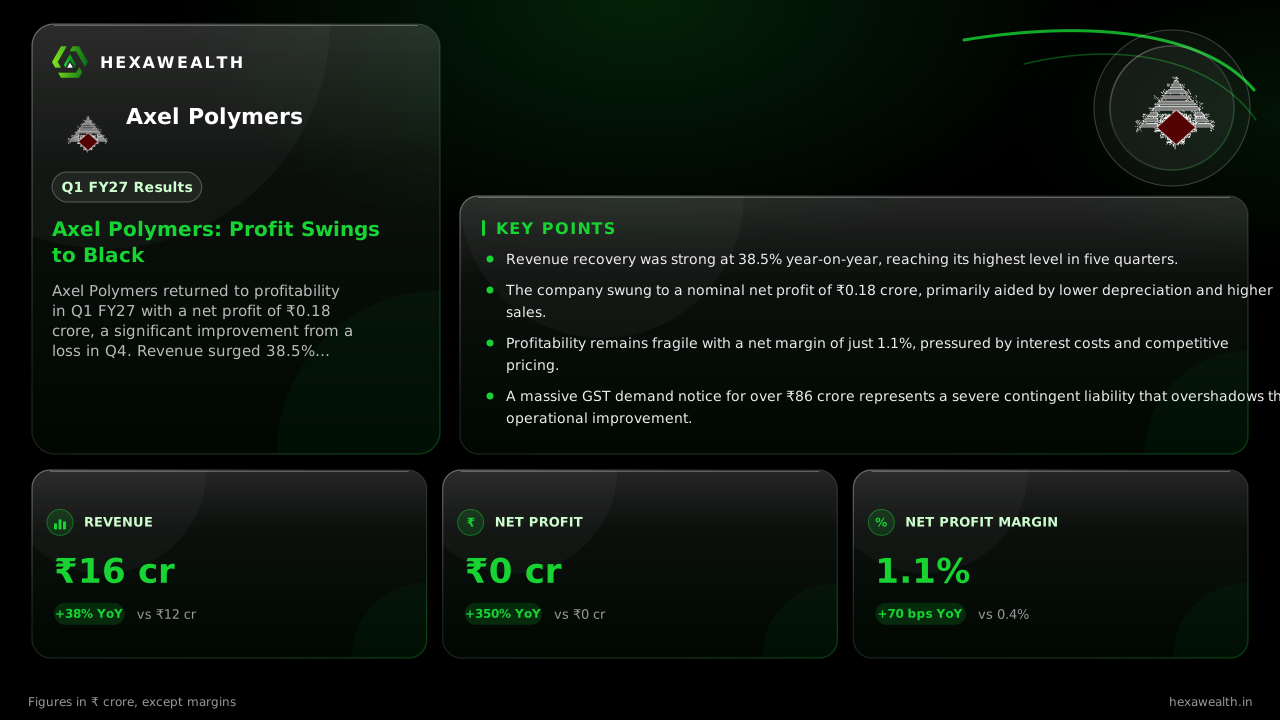
Axel Polymers returned to profitability in Q1 FY27 with a net profit of ₹0.18 crore, a significant improvement from a loss in Q4. Revenue surged 38.5% year-on-year to ₹16.2 crore, though profitability remains fragile.
For Axel Polymers, the first quarter of FY27 was about escaping a deep hole. The company, which makes engineering polymer compounds, had posted losses in two of the last three quarters. This quarter brought a top-line surge and a fragile return to the black.
The numbers show a business in recovery, but one still finding its footing. Revenue reached ₹16.2 crore, up 38.5% from a year ago and 23.5% from the March quarter. Net profit was ₹0.18 crore, a sharp swing from the ₹0.82 crore loss in Q4. The margin story is stark: the net profit margin improved by 740 basis points sequentially to 1.1%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ1 FY27 (Jun 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 16.2 | 13.12 |
| Profit (₹ Cr) | 0.18 | -0.82 |
| Net Profit Margin (%) | 1.1 | -6.3 |
The fragile nature of profit
The profit swing is more a story of cost control than booming margins. According to a Cruxal.in analysis, operating profit rose to ₹1.06 crore, pushing the operating margin to 6.54%. A key contributor was a 45.5% quarter-on-quarter drop in depreciation expense. This, as per the company's filings, helped offset still-elevated interest costs, which rose 7.6% sequentially to ₹0.75 crore.
Management has pointed to broader challenges. A report from ScanX.Trade notes the company attributed past performance issues to subdued demand in certain segments, competitive pricing, and raw material cost fluctuations. These headwinds haven't fully abated, keeping the current profitability thin.
A looming regulatory shadow
Beyond operations, a significant overhang persists. The company is contesting a GST order demanding ₹31.57 crore in input tax credit and ₹55.06 crore in penalties for FY22-FY25, as reported by MCapital. This sum dwarfs its annual revenue of ₹44.4 crore. While an appeal is underway, it creates a substantial contingent liability and potential cash outflow for a pre-deposit.
This regulatory cloud complicates any turnaround narrative. The stock closed at ₹48.75 on the results date, down 9.1% over the past year, reflecting these persistent risks alongside the company's high debt-to-equity ratio of 1.18.
Key Points
- Revenue recovery was strong at 38.5% year-on-year, reaching its highest level in five quarters.
- The company swung to a nominal net profit of ₹0.18 crore, primarily aided by lower depreciation and higher sales.
- Profitability remains fragile with a net margin of just 1.1%, pressured by interest costs and competitive pricing.
- A massive GST demand notice for over ₹86 crore represents a severe contingent liability that overshadows the operational improvement.
Hexa Perspective
The quarter shows Axel Polymers can generate sales growth, but converting that into durable profit is the unresolved challenge. The margin improvement is welcome but partly technical, relying on a lower depreciation charge. The core business still grapples with the interest burden from a leveraged balance sheet.
The GST dispute is the defining risk. Its scale relative to the company's size means the appeal's outcome will likely outweigh any near-term operational progress for investors. Until there is clarity on this front or evidence of sustained margin expansion, the stabilization remains precarious.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.