Asian Hotels (AHLEAST) (East) Profit Returns, But Operating Margins Slip in Q2 FY27
The Hyatt Regency Kolkata operator swung to a ₹5.16 crore profit, yet a sequential margin squeeze and high leverage cloud the recovery.
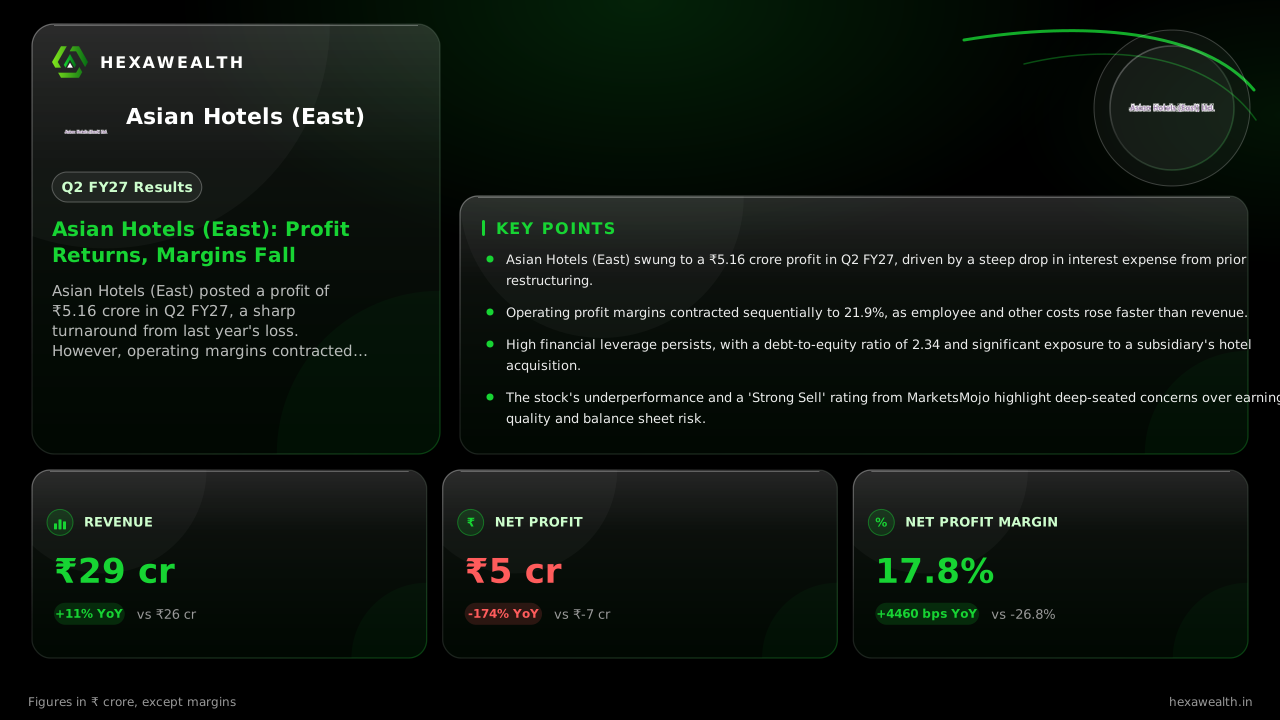
Asian Hotels (East) posted a profit of ₹5.16 crore in Q2 FY27, a sharp turnaround from last year's loss. However, operating margins contracted sequentially as costs rose, and the company's high debt remains a structural challenge.
For Asian Hotels (East), the operator of Hyatt Regency Kolkata, the September quarter delivered a headline win: a return to profitability. The underlying story, however, is one of a fragile recovery where cost pressures are rising faster than revenue, and a heavy debt load continues to define the business.
Revenue rose 11.2% year-on-year to ₹29 crore, while net profit stood at ₹5.16 crore, a dramatic swing from a ₹6.98 crore loss in the same quarter last year. Sequentially, profit grew 19.4% from the June quarter. The scorecard shows the turnaround, but the details reveal its quality.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentSep 2026 (Q2 FY27) | PreviousJun 2026 (Q1 FY27) |
|---|---|---|
| Revenue (₹ Cr) | 29.00 | 26.87 |
| Profit (₹ Cr) | 5.16 | 4.32 |
| Net Profit Margin | 17.8% | 16.1% |
Why the profit rebound feels fragile
The profit swing was powered by a collapse in interest costs, which fell over 70% year-on-year to ₹3.04 crore. MarketsMojo notes this reflects improved balance sheet management following debt restructuring. Yet, operating margins tell a different story. Employee costs rose 13.8% YoY, and the operating profit margin, excluding other income, contracted to 21.9% from 24.1% in the prior quarter.
This margin compression indicates the core hotel business faced rising costs or pricing pressure even as revenue grew. The Kolkata market, as per MarketsMojo, faces slower recovery dynamics and competitive pressure compared to other metros, limiting pricing power for the single-property company.
The debt that defines the horizon
Despite lower interest costs, leverage remains the company's defining characteristic. The debt-to-equity ratio stands at 2.34, and the current ratio is a tight 0.23, signalling significant working capital pressure. The company's subsidiary, Novak Hotels, is pursuing the acquisition of Hyatt Regency Mumbai, with capital work-in-progress of over ₹500 crore, as noted by Arthneeti.
This massive exposure, alongside borrowings of ₹140 crore secured against the Kolkata property, means balance sheet stress is a multi-quarter reality. The recovery in profitability provides cash flow, but it is first a tool for managing this existing leverage rather than funding growth.
How the market read the print
The stock closed at ₹134.25 on November 13, the day before the results. It trades 26.85% below its 52-week high, reflecting the market's scepticism about sustainability. MarketsMoji assigned a 'Strong Sell' rating just days before the results, citing weak return ratios, high leverage, and minimal institutional ownership.
No formal management guidance was published with the results. The outlook, therefore, hinges on the company's ability to defend margins in a competitive Kolkata market while navigating its substantial debt and subsidiary commitments.
Key Points
- Asian Hotels (East) swung to a ₹5.16 crore profit in Q2 FY27, driven by a steep drop in interest expense from prior restructuring.
- Operating profit margins contracted sequentially to 21.9%, as employee and other costs rose faster than revenue.
- High financial leverage persists, with a debt-to-equity ratio of 2.34 and significant exposure to a subsidiary's hotel acquisition.
- The stock's underperformance and a 'Strong Sell' rating from MarketsMojo highlight deep-seated concerns over earnings quality and balance sheet risk.
Hexa Perspective
The quarter presents a classic tension between a cyclical upturn and structural constraints. The profit is real, born of successful debt cost reduction, but the operating margin squeeze suggests the underlying hotel business is not yet generating robust, high-quality earnings.
For the recovery to be more than a debt-refinancing story, the company must demonstrate it can expand margins on a sustained basis. With a leverage ratio above 2, a tight liquidity position, and a major capital commitment in progress, the balance sheet offers little room for error. Investors are rightly weighing the profit rebound against these persistent, heavy anchors.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.