All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 14 November 20263 min read

Agarwal Industrial (AGARIND) Q2 FY27 Profit Jumps 50% Despite Seasonal Revenue Dip

The company's Q2 FY27 net profit surged 50% sequentially, powered by a sharp recovery in bitumen margins and lower costs, even as revenue fell 29% due to monsoon seasonality.

By Anant Kacholia, HexaWealth Research · Created 14 November 2026

Agarwal Industrial's Q2 FY27 profit rose 50% from the previous quarter to ₹15.5 crore. This came despite a 29% sequential revenue drop, a pattern the company attributes to the seasonal nature of its core bitumen business during monsoon months.

For a company tied to road construction, the monsoon quarter is a test of operational resilience. Agarwal Industrial Corporation passed it, posting a 50% sequential jump in net profit even as revenue fell by nearly a third, a pattern the company's own filing notes is typical for its seasonal bitumen business.

The numbers show a quarter of sharp contrasts. Year-on-year, revenue grew 26% to ₹309 crore. Sequentially, it dropped 29% from a high base in Q1. Profit, however, rose 30% over last year and 50% from the prior quarter, with the net profit margin expanding to 5%.

Revenue & profit

Revenue (₹ Cr)

Net Profit (PAT) (₹ Cr)

Net Profit Margin

MetricCurrentQ2 FY27 (Sep 2026)PreviousQ1 FY27 (Jun 2026)
Revenue (₹ Cr)
308.58
433.31
Net Profit (PAT) (₹ Cr)
15.54
10.35
Net Profit Margin
5.0%
2.4%

Why profit rose as revenue fell

The profit surge was driven by a powerful margin recovery in the core bitumen segment. According to StockWatch, the Ancillary Infrastructure segment's profit before interest and tax (PBIT) nearly tripled year-on-year to ₹10.81 crore. This was supported by a 22% drop in finance costs, as the company cut short-term borrowings by ₹116 crore in the first half, reports Multibagg.ai.

Costs fell faster than revenue. Total expenses dropped 31% sequentially, with depreciation down 18% and interest nearly flat. This operational efficiency, amid lower monsoon-related activity, allowed profitability to expand sharply.

A tale of two segments

Not all divisions shared the strength. The Petroleum vessel chartering segment showed margin pressure, with its PBIT falling 9% year-on-year despite 32% higher revenue, as noted by StockWatch. This divergence highlights where the company's near-term earnings power currently lies.

Management, in a filing note cited by Alfafinder, stated it has taken measures to minimize the impact of the Middle East conflict on supply and pricing. The outlook is tied to a large order book, including a ₹478 crore bitumen supply contract from HPCL secured in June.

Key Points

  • Net profit jumped 50% quarter-on-quarter to ₹15.5 crore, defying a 29% sequential drop in revenue due to seasonal monsoon effects./n- A sharp recovery in bitumen segment profitability and a significant reduction in finance costs were the primary drivers of the margin expansion.
  • The company's cash flow strengthened, with operating cash inflow of ₹143 crore in H1 FY27 funding a ₹116 crore reduction in short-term debt.

Hexa Perspective

This quarter demonstrates Agarwal Industrial's ability to manage costs and preserve margins during its seasonal low. The story for the coming quarters, however, hinges on execution. The substantial HPCL contract and the post-monsoon rebound in road activity, amid rising bitumen prices, set the stage for stronger revenue. The catch is whether the vessel segment's margin pressure eases and if the company can translate higher industry demand into sustained profitability. With a cleaner balance sheet, the capacity to perform is there, but the market will judge it on delivery.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
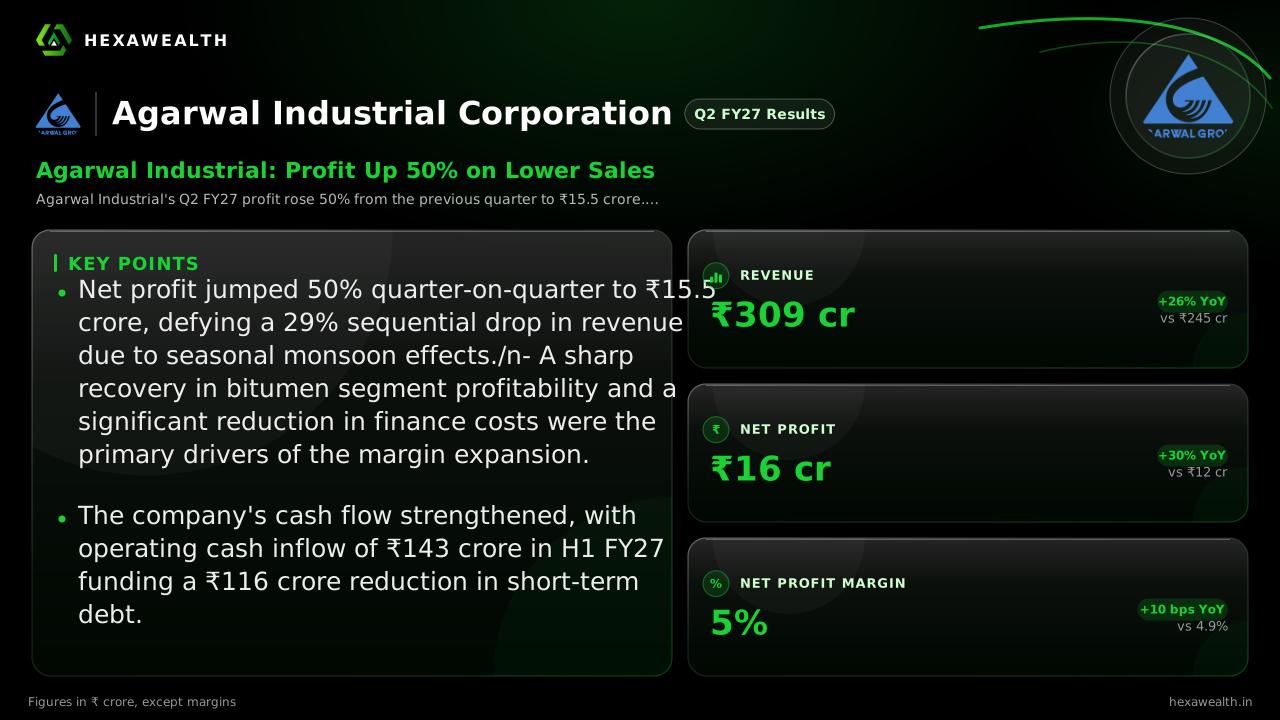
Agarwal Industrial Corporation (AGARIND) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Agarwal Industrial Corporation's Q2 FY27 results?
Agarwal Industrial Corporation reported consolidated revenue of ₹308.58 crore and a net profit of ₹15.54 crore for Q2 FY27 (quarter ended September 2026). This represents a 26% year-on-year revenue growth and a 30% increase in profit. Sequentially, profit rose 50% despite a 29% drop in revenue.
Why did Agarwal Industrial's Q2 FY27 revenue decline 28.8% sequentially?
The sequential revenue drop is a seasonal pattern, not a trend reversal. The company's filing, as reported by StockWatch, notes that the bitumen and infrastructure business is seasonal, with monsoon months typically curbing road-laying demand, which explains the QoQ dip.
What drove the 50.1% quarter-on-quarter surge in net profit for Agarwal Industrial in Q2 FY27?
The profit surge was driven by a sharp margin recovery in the core bitumen segment and lower costs. StockWatch reports the Ancillary Infra segment's PBIT nearly tripled YoY. Finance costs also fell 22% year-on-year due to lower borrowings, supporting the bottom line.
Why did Agarwal Industrial's net profit margin expand by 260 basis points sequentially?
The net profit margin expanded to 5.0% from 2.4% in Q1 due to stringent cost control. Total expenses fell 31% QoQ, outpacing the 29% revenue decline. Lower finance and depreciation costs, alongside a strong bitumen margin recovery, drove the improvement.
Did a specific segment drive Agarwal Industrial's Q2 FY27 performance?
Yes, the core Ancillary Infrastructure (Bitumen & Allied Products) business was the main driver. According to StockWatch, its segment PBIT nearly tripled year-on-year to ₹10.81 crore. In contrast, the Petroleum vessel chartering segment saw its PBIT fall 8.6% despite higher revenue.
How did lower costs contribute to Agarwal Industrial's Q2 FY27 profitability?
Lower finance and depreciation costs significantly boosted profit. Finance costs fell 22% year-on-year to ₹5.21 crore due to reduced borrowings. Depreciation was down 10% YoY and 18% QoQ. These savings helped profit grow faster than revenue.
What is the status of Agarwal Industrial's order book as of Q2 FY27?
The company's project pipeline is anchored by a substantial ₹477.50 crore bitumen supply contract from HPCL, secured in June 2026. Alfafinder reports this contract is scheduled through May 2027, providing visibility for the core business.
What explains the 142.1% year-on-year increase in tax expense?
The tax expense rose to ₹3.84 crore from ₹1.59 crore in Q2 FY26 because the effective tax rate climbed to 19.8% from 11.7% a year ago. This higher rate is why net profit growth (+30%) trailed pre-tax profit growth (+43%).
Did Agarwal Industrial's Q2 results beat analyst estimates?
There is no record of analyst coverage or consensus estimates for this micro-cap stock, as confirmed by a search cited in StockWatch. Therefore, the results cannot be classified as a beat or a miss against published street expectations.
How did the stock price react to the Q2 FY27 results?
The stock closed at ₹422.75 on November 13, 2026, the day before the official results announcement, down 4.3% for the day. It had risen nearly 13% over the preceding month going into the print.
What is the outlook for Agarwal Industrial's cash flow?
The cash flow outlook is positive. For the six months ended September 2026, the company generated ₹142.98 crore from operations and cut short-term borrowings by ₹115.58 crore, as reported by Multibagg.ai. This provides financial flexibility for upcoming project execution.
Agarwal Industrial Corporation Q2 net profit
Agarwal Industrial Corporation's Q2 FY27 (September 2026 quarter) consolidated net profit was ₹15.54 crore. This marks a 29.6% increase from the ₹11.99 crore profit reported in the same quarter last year (Q2 FY26).
Agarwal Industrial Corporation Q2 FY27 results order book
A key component of Agarwal Industrial's Q2 FY27 order book is a ₹477.50 crore bitumen supply contract from HPCL, as reported by Alfafinder. This contract, secured in June 2026, is scheduled to run through May 2027, supporting future revenue visibility.