All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 14 November 20263 min read

Patanjali Foods (PATANJALI) Q2 FY27 Profit Growth Stalls Behind a Record Revenue Quarter

The company's September quarter revenue soared, but profitability was squeezed by higher costs and a shift in its business mix.

By Abhinav Singhvi, Founder & CEO Hexawealth · Created 28 October 2026

Patanjali Foods reported a 131% year-on-year surge in revenue for Q2 FY27, yet profit growth was a more modest 46%. The gap highlights margin pressure from rising input costs and a growing reliance on its lower-margin edible oils segment.

For Patanjali Foods, the September quarter was a story of two engines. Its massive edible oils business drove revenue to a new high, while its more profitable FMCG arm struggled to keep pace, leaving overall earnings growth trailing far behind the top line.

The numbers show the split clearly. Revenue more than doubled year-on-year to ₹22,660 crore. Profit, however, grew at less than half that rate, reaching ₹755.5 crore. The net profit margin fell 200 basis points from a year ago to 3.3%.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Net Profit Margin

MetricCurrentQ2 FY27PreviousQ1 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr)
22,660.03YoY +131%
11,337.45
9,798.84
Profit (₹ Cr)
755.5YoY +46%
335.73
516.7
Net Profit Margin
3.3%YoY -38%
3.0%
5.3%

Why Profitability Shrank

The margin squeeze came from a faster-growing, lower-margin business taking the lead. According to a report by Multibagg.ai, the edible oils segment posted record revenue of ₹8,532 crore, up 22% year-on-year, but with an EBITDA margin of just 3%. Meanwhile, the higher-margin FMCG segment, with a 7.57% EBITDA margin, grew at a slower pace.

Costs also rose sharply. Total expenses jumped 134% from last year, with interest costs surging 154% as the company's debt level increased. Management, cited by Multibagg.ai, noted retail and food inflation climbed through the quarter, pressuring input costs for key ingredients like wheat, milk, and sugar.

The Path Ahead

CEO Sanjeev Asthana expects growth momentum to continue through the festive and wedding seasons. The company is focusing on premiumisation and portfolio expansion within FMCG to improve the mix. However, the near-term outlook remains tied to volatile commodity prices and the success of these brand-building efforts.

The market reaction was muted, with the stock closing at ₹421 on November 13. This reflects investor caution as the company trades at a P/E of 27.5, a discount to the industry average, balancing strong revenue growth against persistent margin challenges.

Key Points

  • Revenue growth of 131% YoY was driven by a record performance in the edible oils segment.
  • Profit growth of 46% YoY lagged significantly, compressing the net profit margin by 200 basis points.
  • Higher input costs and a business mix shift toward lower-margin edible oils were the primary drags on profitability.
  • Management is banking on festive demand and FMCG premiumisation to sustain growth, but margins face headwinds from inflation.

Hexa Perspective

This quarter underscores Patanjali Foods' transition phase. The company is successfully scaling its volume-heavy edible oils operation, which provides revenue heft and market share. Yet, the path to higher quality earnings runs through its FMCG business, where margins are better but growth is more competitive and costly to achieve. The coming quarters will test whether brand investments and a favourable festive calendar can lift FMCG's contribution enough to offset the inherent thin margins of the oils business. Until that mix improves meaningfully, strong revenue numbers may continue to deliver relatively weaker profit growth.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
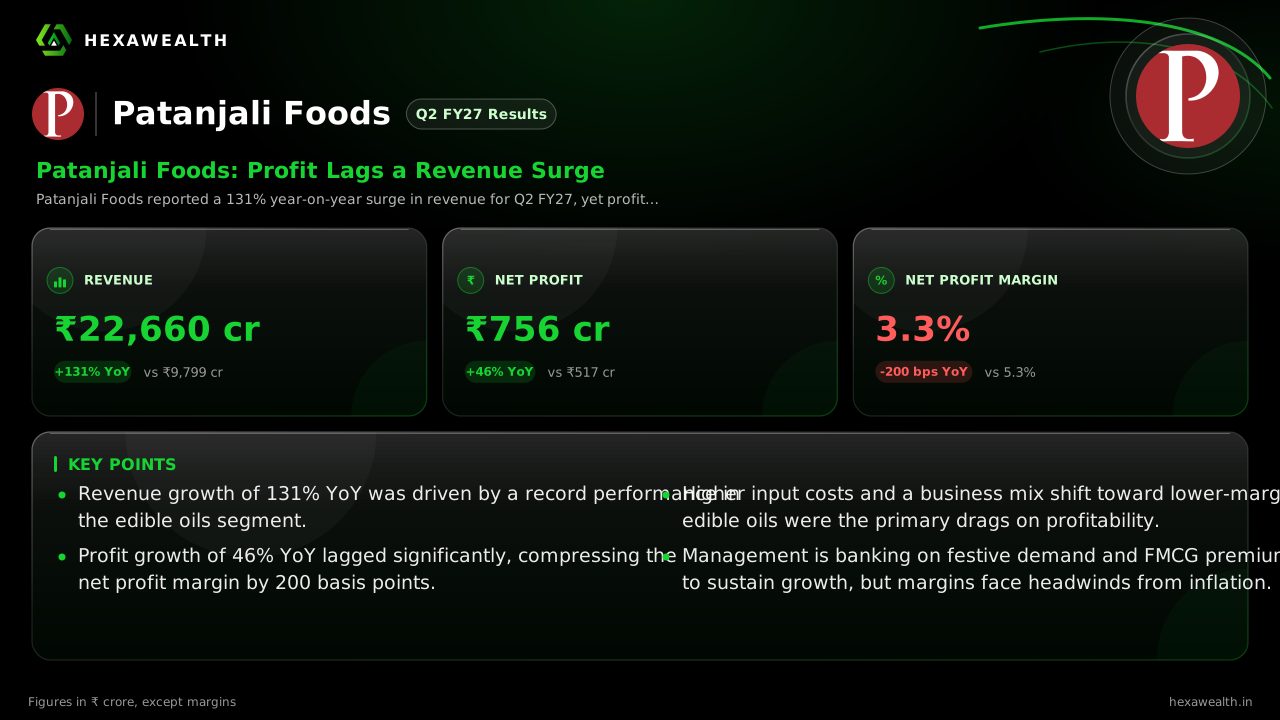
Patanjali Foods (PATANJALI) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Patanjali Foods' Q2 FY27 results?
For the September 2026 quarter, Patanjali Foods reported consolidated revenue of ₹22,660.03 crore, a 131% increase year-on-year. Net profit was ₹755.5 crore, marking a 46% growth from the same quarter last year. The net profit margin for the quarter was 3.3%.
Why did Patanjali Foods' profit margin decline in Q2 FY27?
Patanjali Foods' net profit margin fell 200 basis points year-on-year to 3.3% in Q2 FY27. The decline was driven by a faster-growing, lower-margin edible oils segment and higher overall costs. Reports from Multibagg.ai note that interest expense surged 154% and input costs rose amid increasing food inflation.
How did Patanjali Foods' edible oils segment perform in Q2 FY27?
Patanjali Foods' edible oils segment delivered record revenue of ₹8,532.25 crore in Q2 FY27, up 22.39% year-on-year, as reported by Multibagg.ai. The segment's EBITDA margin was 3.00%. It contributed the majority of the company's total revenue but at a lower profitability than its FMCG business.
How did Patanjali Foods' FMCG business perform in the September 2026 quarter?
According to Multibagg.ai, Patanjali Foods' FMCG segment generated revenue of ₹2,923.48 crore and EBITDA of ₹221.33 crore in Q2 FY27, resulting in a healthier EBITDA margin of 7.57%. The segment contributed 45% of the company's EBITDA excluding unallocable income.
What was the reason for the 154% increase in interest cost for Patanjali Foods in Q2 FY27?
Patanjali Foods' interest expense rose 154% year-on-year in Q2 FY27, reaching ₹89.81 crore. This sharp increase correlates with a rise in the company's debt levels, as its debt-to-equity ratio increased from 0.14 to 0.22 over the past year, indicating higher borrowing to fund operations or growth.
What guidance did Patanjali Foods management provide after Q2 FY27 results?
Management, cited by Multibagg.ai, stated they expect growth momentum to continue through the festive and wedding seasons. CEO Sanjeev Asthana highlighted a focus on premiumisation, FMCG portfolio expansion, and operating efficiencies to drive future performance.
Did Patanjali Foods' Q2 FY27 results beat analyst estimates?
The available research does not provide specific consensus analyst estimates for Patanjali Foods' Q2 FY27 revenue and profit. The reported figures show strong revenue growth of 131% YoY, but profit growth of 46% was significantly lower, indicating performance was likely mixed relative to expectations.
How did Patanjali Foods stock price react to the Q2 FY27 results?
On the last trading day before the results (November 13, 2026), Patanjali Foods' stock closed at ₹421.00, down 2.27%. The stock has declined 28.4% over the past year, reflecting broader market sentiment and concerns over profitability despite strong revenue growth.
What is Patanjali Foods' debt-to-equity ratio after Q2 FY27?
Patanjali Foods' debt-to-equity ratio stood at 0.22 as of the latest reporting, a significant increase from 0.14 a year ago. This indicates the company has taken on more debt relative to its equity, which contributed to the sharp rise in interest costs during the quarter.
Patanjali Foods Q2 FY27 results August 2026
Patanjali Foods announced its Q2 FY27 (July-September 2026) results on November 14, 2026. The company reported revenue of ₹22,660.03 crore and a net profit of ₹755.5 crore for the quarter ended September 2026.
Patanjali Foods biscuits revenue rises 28% as margin reaches 11.91%
In Q2 FY27, Patanjali Foods' biscuits division revenue rose 27.69% year-on-year to ₹638.31 crore, as reported by Multibagg.ai. The segment's EBITDA margin expanded to 11.91% from 9.79% in the prior-year quarter, demonstrating strong performance within the FMCG portfolio.
Patanjali Foods reports record Rs 22,660 crore H1 revenue
For the first half of FY27 (H1FY27), Patanjali Foods reported record revenue from operations of ₹22,660.03 crore, a 22.06% increase year-on-year. The half-year operating EBITDA, excluding exceptional items, was ₹969.03 crore, yielding a margin of 4.28%.