Toss the Coin (TTC) Q4 FY26 Profit Slips Despite Revenue Surge as Costs Rise
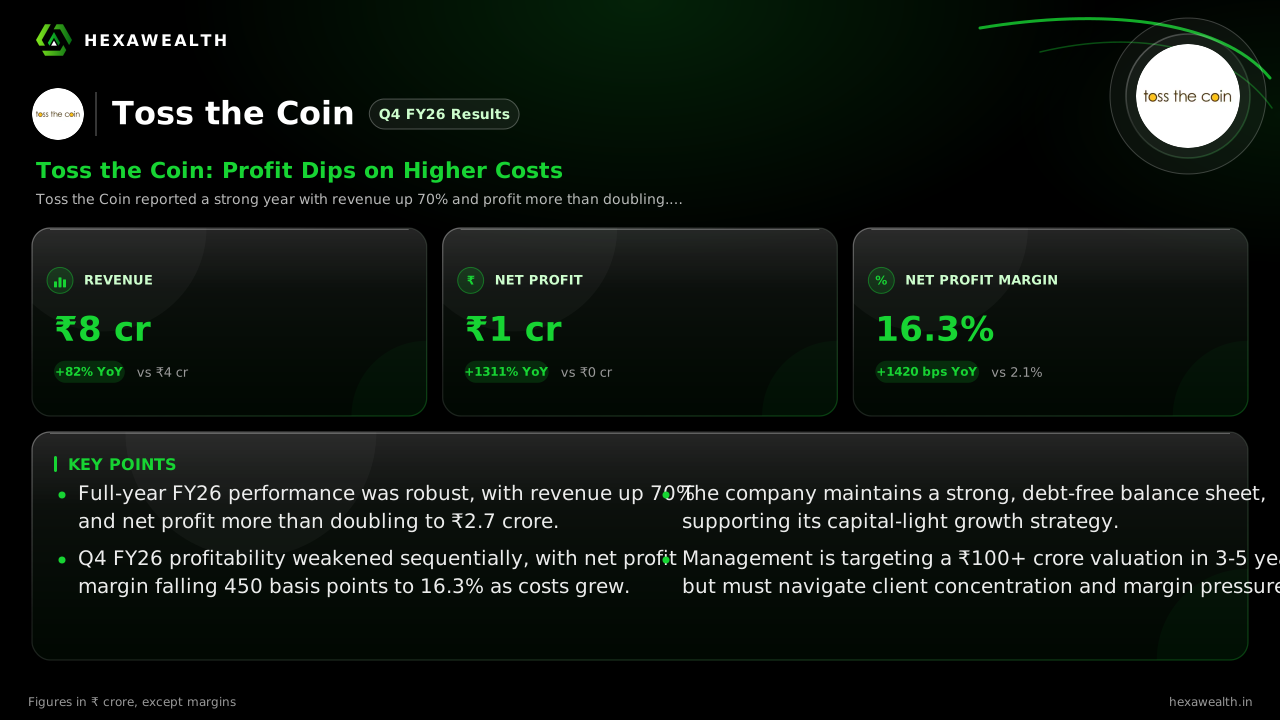
The company's Q4 revenue jumped 82% year-on-year, but profit fell 11% sequentially as expenses and depreciation rose faster than sales.
Toss the Coin reported a strong year with revenue up 70% and profit more than doubling. However, the March quarter saw profitability weaken as costs grew, highlighting the challenge of scaling while preserving margins.
For Toss the Coin, a year of explosive growth ended with a quarter that showed the cost of that expansion. The company closed FY26 with revenue nearly doubling and profit more than doubling, but the final quarter revealed margin pressure as expenses outpaced sales.
The numbers tell a story of two halves. Full-year revenue hit ₹14.7 crore, up 70% from FY25, while net profit soared 116% to ₹2.7 crore. The fourth quarter alone saw revenue of ₹7.81 crore, an 82% jump from a weak year-ago period. Yet, profit fell 11% from the previous quarter to ₹1.27 crore as the net profit margin narrowed.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 4.36
- Revenue (₹ Cr), Q4 FY25: 4.29
- Revenue (₹ Cr), Q2 FY26: 6.89
- Revenue (₹ Cr), Q4 FY26: 7.81
- Net Profit (₹ Cr), Q2 FY25: 1.16
- Net Profit (₹ Cr), Q4 FY25: 0.09
- Net Profit (₹ Cr), Q2 FY26: 1.43
- Net Profit (₹ Cr), Q4 FY26: 1.27
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 4.36
- Revenue (₹ Cr), Q4 FY25: 4.29
- Revenue (₹ Cr), Q2 FY26: 6.89
- Revenue (₹ Cr), Q4 FY26: 7.81
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q2 FY25: 1.16
- Net Profit (₹ Cr), Q4 FY25: 0.09
- Net Profit (₹ Cr), Q2 FY26: 1.43
- Net Profit (₹ Cr), Q4 FY26: 1.27
Net Profit Margin
- Net Profit Margin, Q2 FY25: 26.6%
- Net Profit Margin, Q4 FY25: 2.1%
- Net Profit Margin, Q2 FY26: 20.8%
- Net Profit Margin, Q4 FY26: 16.3%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 7.81YoY +82% | 4.29 |
| Net Profit (₹ Cr) | 1.27YoY +1311% | 0.09 |
| Net Profit Margin | 16.3%YoY +676% | 2.1% |
Why Profit Fell as Revenue Rose
The margin squeeze came from two sides. Total expenses rose 24% quarter-on-quarter, faster than the 13% revenue growth. Depreciation more than doubled year-on-year, a sign of recent capital investment. According to data from newboard.in, the operating profit margin for the half-year ending March 2026 was 21.8%, down from 27.5% in the prior six months.
Management, cited by StockFin.ai, is focused on scaling US operations and using AI tools to drive efficiency. Their target is a ₹100+ crore valuation in three to five years while maintaining margins above 25%. However, the quarterly dip shows the execution challenge in balancing growth with profitability.
A Conservative Foundation for Aggressive Goals
The company's balance sheet provides a stable platform for this ambition. It carries virtually no debt, with a debt-to-equity ratio of zero, and holds a strong current ratio of 8.8. This capital-light structure, funded by retained earnings and IPO proceeds, allows aggressive reinvestment without leverage risk.
Live Chart
· TTC
(BSE)
ISIN: INE0XAY01012
Yet, a key risk remains client concentration. StockFin.ai notes that the top three clients still contribute 35% of revenue, with 66% of sales coming from the US market. Diversifying this base is a stated management priority for sustainable scaling.
Key Points
- Full-year FY26 performance was robust, with revenue up 70% and net profit more than doubling to ₹2.7 crore.
- Q4 FY26 profitability weakened sequentially, with net profit margin falling 450 basis points to 16.3% as costs grew.
- The company maintains a strong, debt-free balance sheet, supporting its capital-light growth strategy.
- Management is targeting a ₹100+ crore valuation in 3-5 years but must navigate client concentration and margin pressures.
Hexa Perspective
The quarter underscores the transition from a high-margin, smaller operation to a scaled business where operating leverage has yet to fully kick in. The stellar annual growth is undeniable, but the sequential margin compression asks whether top-line gains can consistently translate to the bottom line.
The path forward hinges on management's ability to execute its US expansion and AI-driven efficiency plans while actively reducing reliance on a few large clients. The debt-free balance sheet buys time, but investors will watch for a reversion to the 20%+ net margins seen earlier in the year as proof that growth is sustainable and profitable.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.