Technocraft Ventures (TECHNOCRAF) Q2 FY27 Profit Jumps 77% as Order Book Fuels Growth
The infrastructure player's revenue surged 66% year-on-year, but sequential profitability softened as costs rose faster than sales.
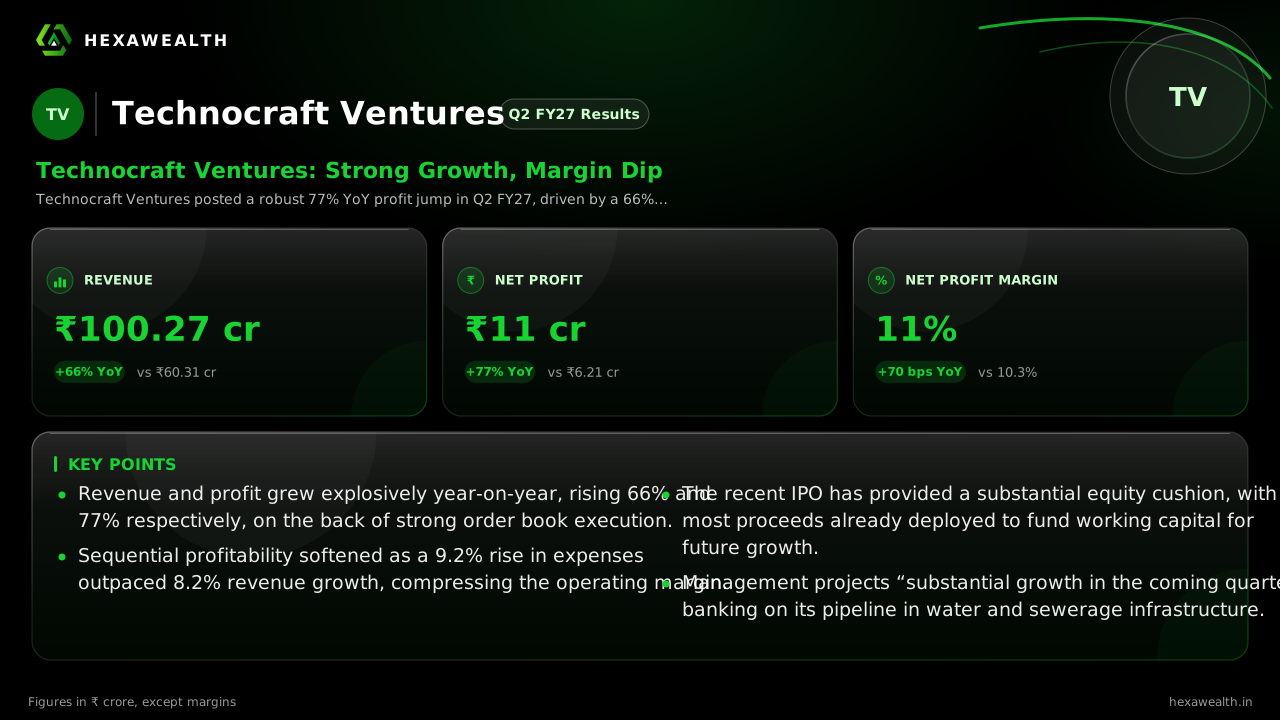
Technocraft Ventures posted a robust 77% YoY profit jump in Q2 FY27, driven by a 66% revenue surge from its growing order book. However, margins contracted sequentially as expenses outpaced sales growth.
For a newly-listed infrastructure EPC firm, the first post-IPO quarters are about proving the order book can convert into sustained growth. Technocraft Ventures delivered that proof with a 66% year-on-year revenue surge, translating to a 77% jump in net profit.
The numbers show a company hitting its stride from a lower base. Revenue reached ₹100.3 crore, while profit settled at ₹11 crore. The year-ago comparison is clean, with reports from Stockwatch.live noting no one-off items to adjust for in either period.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q1 FY26: 90.67
- Revenue (₹ Cr), Q2 FY26: 60.31
- Revenue (₹ Cr), Q4 FY26: 140.00
- Revenue (₹ Cr), Q1 FY27: 92.70
- Revenue (₹ Cr), Q2 FY27: 100.27
- Profit (₹ Cr), Q1 FY26: 9.34
- Profit (₹ Cr), Q2 FY26: 6.21
- Profit (₹ Cr), Q4 FY26: 24.00
- Profit (₹ Cr), Q1 FY27: 10.69
- Profit (₹ Cr), Q2 FY27: 11.00
Revenue (₹ Cr)
- Revenue (₹ Cr), Q1 FY26: 90.67
- Revenue (₹ Cr), Q2 FY26: 60.31
- Revenue (₹ Cr), Q4 FY26: 140.00
- Revenue (₹ Cr), Q1 FY27: 92.70
- Revenue (₹ Cr), Q2 FY27: 100.27
Profit (₹ Cr)
- Profit (₹ Cr), Q1 FY26: 9.34
- Profit (₹ Cr), Q2 FY26: 6.21
- Profit (₹ Cr), Q4 FY26: 24.00
- Profit (₹ Cr), Q1 FY27: 10.69
- Profit (₹ Cr), Q2 FY27: 11.00
Net Profit Margin
- Net Profit Margin, Q1 FY26: 10.3%
- Net Profit Margin, Q2 FY26: 10.3%
- Net Profit Margin, Q4 FY26: 17.1%
- Net Profit Margin, Q1 FY27: 11.5%
- Net Profit Margin, Q2 FY27: 11.0%
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 100.27YoY +66% | 92.70 | 60.31 |
| Profit (₹ Cr) | 11.00YoY +77% | 10.69 | 6.21 |
| Net Profit Margin | 11.0%YoY +6.8% | 11.5% | 10.3% |
Where the growth came from
Management attributed the performance to a “growing orderbook size,” according to its press release cited by Stockwatch.live. The company’s expertise in sewerage and water-supply projects under central schemes is feeding a visible execution ramp. This drove EPC revenue growth of 66% year-on-year.
Sequentially, the story is one of top-line growth meeting cost pressure. Revenue grew 8.2% from the June quarter, but total expenses rose 9.2%. This squeezed the operating margin down by about 100 basis points to 18.4%, as reported by Alpha Tribe.
The cost pinch and the IPO cushion
Interest costs rose 78% year-on-year, reflecting the debt needed to fund projects before the IPO. The recent ₹202 crore fresh issue, however, has sharply strengthened the balance sheet. A report from MCapital notes about ₹150 crore was already utilized by September end, primarily for working capital.
Live Chart
· TECHNOCRAF
(BSE)
ISIN: INE1D0W01018
This capital infusion is critical. It funds the working capital for the very order book driving growth, potentially easing future borrowing needs. The remaining ~₹50 crore, parked in fixed deposits, offers a buffer for corporate initiatives.
Key Points
- Revenue and profit grew explosively year-on-year, rising 66% and 77% respectively, on the back of strong order book execution.
- Sequential profitability softened as a 9.2% rise in expenses outpaced 8.2% revenue growth, compressing the operating margin.
- The recent IPO has provided a substantial equity cushion, with most proceeds already deployed to fund working capital for future growth.
- Management projects “substantial growth in the coming quarters,” banking on its pipeline in water and sewerage infrastructure.
Hexa Perspective
The quarter validates the growth thesis post-listing, showing the order book is real and converting. The year-on-year pop is impressive, but the sequential margin compression is the watchpoint. It suggests that while revenue scales, maintaining pricing power or cost control in a competitive infrastructure market is an ongoing challenge.
The IPO war chest mitigates near-term financing risk, allowing focus on execution. The outlook now hinges on whether revenue growth can re-accelerate to outrun the cost inflation that surfaced this quarter, turning top-line momentum into sustained margin expansion.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.