TCC Concept Q2 FY27 Profit Nearly Doubles QoQ as Tax Credit Lifts Earnings
A deferred tax credit of ₹12.22 crore powered a 96% quarterly profit jump, even as the core business grew more slowly and margins remain under pressure.
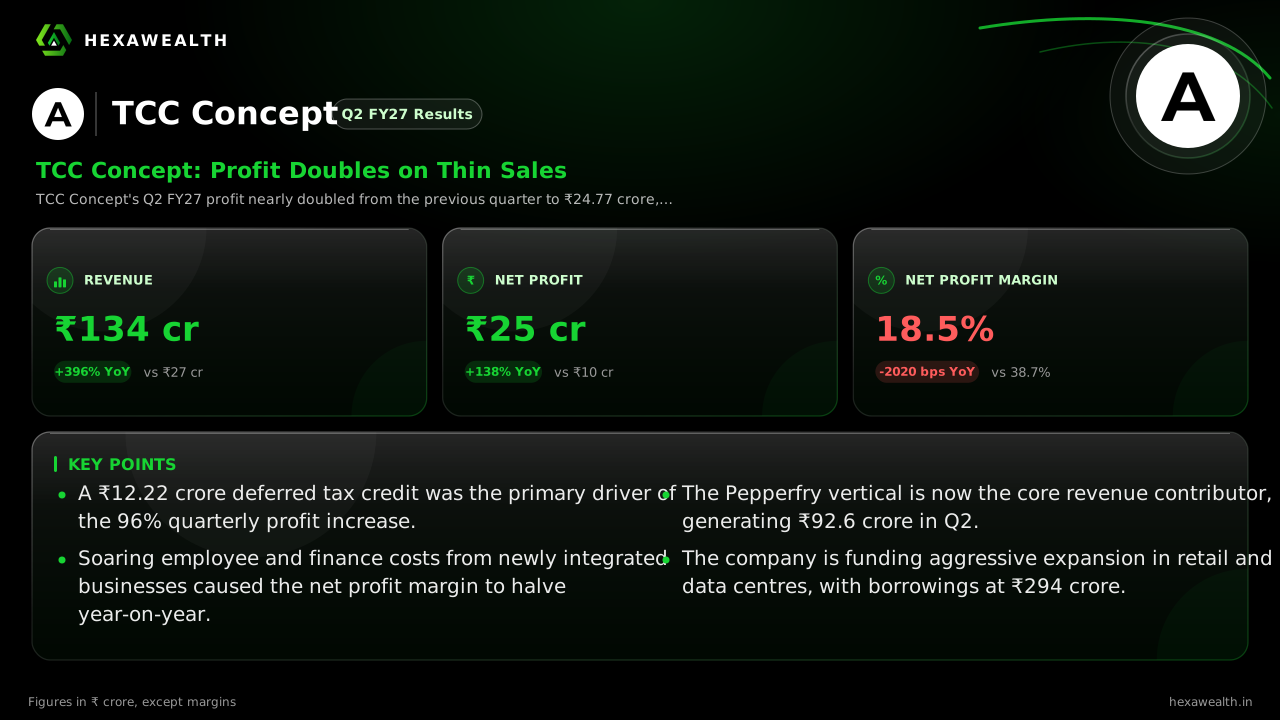
TCC Concept's Q2 FY27 profit nearly doubled from the previous quarter to ₹24.77 crore, but a large tax credit drove the gain. Revenue grew 4.2% sequentially, while costs from newly consolidated businesses squeezed margins.
For TCC Concept, a quarter of explosive top-line growth collided with the heavy costs of scaling. The flexible office space aggregator's revenue multiplied, but profitability tells a more complex story of integration and one-time boosts.
Revenue for the September 2026 quarter reached ₹133.67 crore, a staggering 396% leap from a year ago. Profit after tax rose 138% to ₹24.77 crore. The quarter-on-quarter picture shows more measured top-line growth of 4.2%, but profit nearly doubled, jumping 96%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 26.93
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 46.48
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 83.87
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 128.28
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 133.67
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 10.42
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 14.01
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 30.98
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 12.64
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 24.77
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 26.93
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 46.48
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 83.87
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 128.28
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 133.67
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 10.42
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 14.01
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 30.98
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 12.64
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 24.77
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep 2025): 38.7%
- Net Profit Margin, Q3 FY26 (Dec 2025): 30.1%
- Net Profit Margin, Q4 FY26 (Mar 2026): 36.9%
- Net Profit Margin, Q1 FY27 (Jun 2026): 9.9%
- Net Profit Margin, Q2 FY27 (Sep 2026): 18.5%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 133.67 | 128.28 |
| Profit (₹ Cr) | 24.77 | 12.64 |
| Net Profit Margin | 18.5% | 9.9% |
The tax credit that flattered the profit
The sharp quarterly profit jump had a significant tailwind. According to a report by ScanX, the surge was primarily driven by a substantial deferred tax benefit of ₹12.22 crore. This turned the total tax expense negative for the quarter. Without it, the underlying profit growth was more modest.
Why margins compressed on soaring sales
Despite the revenue surge, the net profit margin fell sharply year-on-year from 38.7% to 18.5%. This reflects the operational scale-up of newly consolidated entities. Employee costs skyrocketed 3,328% YoY to ₹20.26 crore, and finance costs rose over 1,000% to ₹11.53 crore, as reported by ScanX.
The main growth engine was the Pepperfry vertical, which Flash Finance notes contributed ₹92.6 crore to quarterly revenue. The company now operates 125 retail studios and plans to add over 50 more stores this fiscal year.
Live Chart
· TCC
(BSE)
ISIN: INE887D01024
A balance sheet funding ambitious plans
This scaling comes with a heavier balance sheet. Flash Finance data shows borrowings stood at ₹294 crore as of September 2026. The company is also pursuing a massive data centre expansion, having signed an MoU for a 60 MW campus in Pune, a 1,500% increase over its current 4 MW capacity.
Market reaction was positive, with the stock rising 3.3% on the results day. Flash Finance noted an unusually high delivery volume of 83.6%, a pattern often associated with accumulation.
Key Points
- A ₹12.22 crore deferred tax credit was the primary driver of the 96% quarterly profit increase.
- Soaring employee and finance costs from newly integrated businesses caused the net profit margin to halve year-on-year.
- The Pepperfry vertical is now the core revenue contributor, generating ₹92.6 crore in Q2.
- The company is funding aggressive expansion in retail and data centres, with borrowings at ₹294 crore.
Hexa Perspective
The quarter illustrates the tension between hyper-growth and sustainable profitability. The headline profit jump is largely a one-off accounting benefit, while the underlying business is in a heavy investment phase. The success of Pepperfry's turnaround is clear, but it brings a much higher fixed-cost structure. Investors are betting that the current margin compression is a temporary cost of achieving scale in a booming flexible office market. The key watchpoint is whether operating leverage kicks in before the next phase of capital-intensive data centre expansion begins.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.