SSMD Agrotech Profit Triples as Revenue Jumps 83% in Q4 FY26
The FMCG firm's March quarter saw a dramatic top-line surge, but rising costs and delayed expansion plans cloud the near-term outlook.
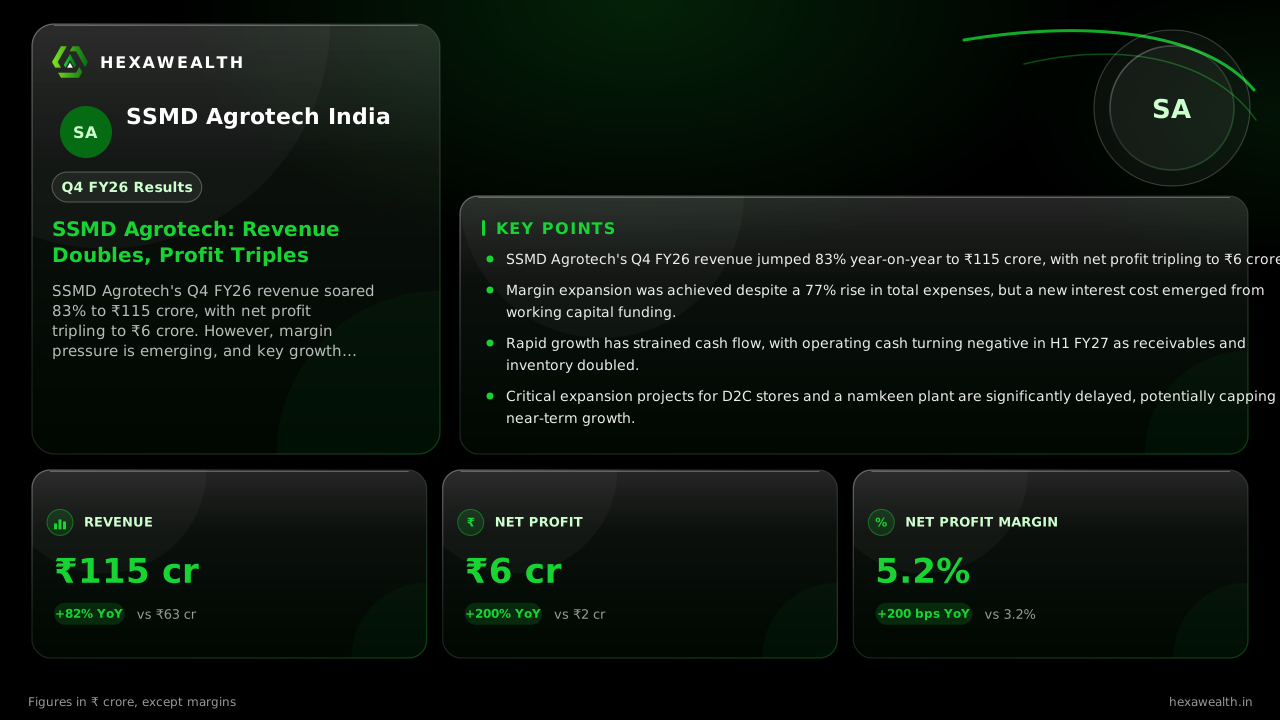
SSMD Agrotech's Q4 FY26 revenue soared 83% to ₹115 crore, with net profit tripling to ₹6 crore. However, margin pressure is emerging, and key growth projects are behind schedule, raising questions about sustainability.
For SSMD Agrotech, the March quarter was a story of explosive growth finally reaching the bottom line. The FMCG player, operating under brands like House of Manohar, saw revenue nearly double year-on-year, translating into a threefold jump in profit. This capped a year where the company graduated from a tiny base to a ₹115-crore revenue business.
The numbers tell a clear story of acceleration. Revenue surged to ₹115 crore in Q4 FY26 from ₹63 crore a year ago. Net profit followed, rising to ₹6 crore from ₹2 crore. The net profit margin expanded by 200 basis points to 5.2%, showing that profitability improved even as the business scaled rapidly.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 63.0
- Revenue (₹ Cr), Q4 FY26: 115.0
- Net Profit (₹ Cr), Q4 FY25: 2.0
- Net Profit (₹ Cr), Q4 FY26: 6.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 63.0
- Revenue (₹ Cr), Q4 FY26: 115.0
Net Profit (₹ Cr)
- Net Profit (₹ Cr), Q4 FY25: 2.0
- Net Profit (₹ Cr), Q4 FY26: 6.0
Net Profit Margin
- Net Profit Margin, Q4 FY25: 3.2%
- Net Profit Margin, Q4 FY26: 5.2%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 115.0YoY +83% | 63.0 |
| Net Profit (₹ Cr) | 6.0YoY +200% | 2.0 |
| Net Profit Margin | 5.2%YoY +63% | 3.2% |
The growth engine and its new costs
The surge was driven by its portfolio of branded agro-food products like gram flour, chana dal, and spices, sold through both B2B and direct-to-consumer channels. However, this growth came with a cost. Total expenses rose 77%, slightly slower than revenue, which allowed margins to expand.
A new interest expense of ₹1 crore appeared in the quarter, which mCapital notes was linked to rising short-term borrowings needed to fund working capital. This is a sign that the cash conversion cycle is stretching as the company finances higher receivables and inventory to support its sales jump.
A strained balance sheet and delayed plans
The strain is visible beyond the P&L. According to mCapital, operating cash flow for the first half of the next fiscal year (H1 FY27) was deeply negative at -₹6.76 crore. Receivables and inventories roughly doubled from March 2026 levels, indicating that growth is consuming cash faster than it is being generated.
Live Chart
· SSMD
(BSE)
ISIN: INE1U2R01013
Furthermore, the company's expansion plans are lagging. Its IPO-funded projects for new D2C dark stores and a namkeen plant are progressing slower than planned. mCapital reports that about 92% of the allocated ₹3 crore for this growth capex remains unspent due to phased execution, which could trim near-term revenue potential.
Key Points
- SSMD Agrotech's Q4 FY26 revenue jumped 83% year-on-year to ₹115 crore, with net profit tripling to ₹6 crore.
- Margin expansion was achieved despite a 77% rise in total expenses, but a new interest cost emerged from working capital funding.
- Rapid growth has strained cash flow, with operating cash turning negative in H1 FY27 as receivables and inventory doubled.
- Critical expansion projects for D2C stores and a namkeen plant are significantly delayed, potentially capping near-term growth.
Hexa Perspective
This quarter marks a powerful operational breakout for SSMD Agrotech, proving it can scale its branded FMCG model profitably. The 23% return on equity and minimal debt provide a solid foundation. Yet, the sustainability of this leap is now the central question. The sharply negative cash flow and ballooning working capital reveal that this growth is capital-intensive. The delayed deployment of growth capex means the next leg of expansion is postponed, just as the existing business model shows signs of cash strain. Investors are left weighing a proven growth story against a balance sheet that is starting to feel the heat.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.