SSMD Agrotech Q2 FY27 Profit Rises 25% as Cash Flow Turns Negative
The agri-processor's revenue jumped 38.5% year-on-year, but a sharp build-up in inventory and receivables drained operating cash.
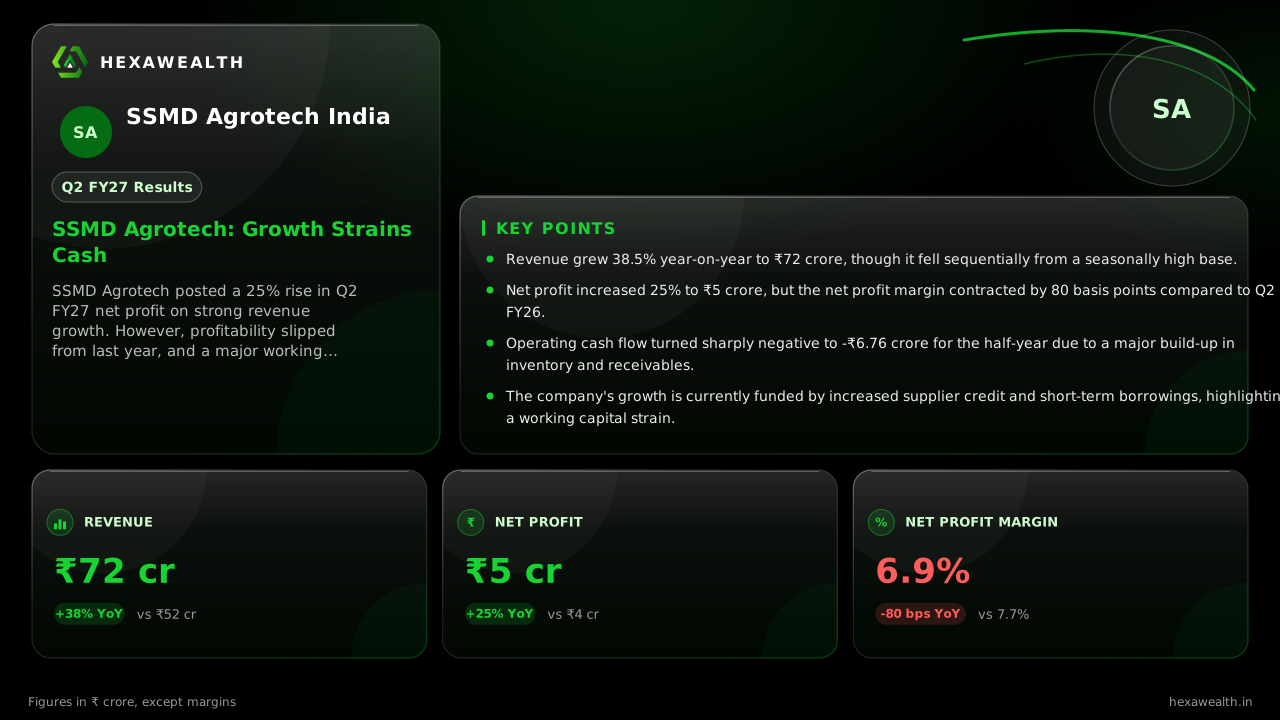
SSMD Agrotech posted a 25% rise in Q2 FY27 net profit on strong revenue growth. However, profitability slipped from last year, and a major working capital build led to a negative operating cash flow of ₹6.76 crore.
For a commodity trader, growth is a double-edged sword. SSMD Agrotech's September quarter shows the blade cutting both ways, with a 38.5% revenue surge accompanied by a cash conversion that turned deeply negative.
The numbers tell a story of expansion under pressure. Revenue reached ₹72 crore, up sharply from last year but down 37% from a seasonally strong March quarter. Profit grew 25% to ₹5 crore. The net profit margin, however, narrowed by 80 basis points year-on-year to 6.9%, though it improved sequentially.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 63.0
- Revenue (₹ Cr), Q2 FY26: 52.0
- Revenue (₹ Cr), Q4 FY26: 115.0
- Revenue (₹ Cr), Q2 FY27: 72.0
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 4.0
- Profit (₹ Cr), Q4 FY26: 6.0
- Profit (₹ Cr), Q2 FY27: 5.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 63.0
- Revenue (₹ Cr), Q2 FY26: 52.0
- Revenue (₹ Cr), Q4 FY26: 115.0
- Revenue (₹ Cr), Q2 FY27: 72.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 4.0
- Profit (₹ Cr), Q4 FY26: 6.0
- Profit (₹ Cr), Q2 FY27: 5.0
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY25: 3.2
- Net Profit Margin (%), Q2 FY26: 7.7
- Net Profit Margin (%), Q4 FY26: 5.2
- Net Profit Margin (%), Q2 FY27: 6.9
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 72.0YoY +38% | 52.0 |
| Profit (₹ Cr) | 5.0YoY +25% | 4.0 |
| Net Profit Margin (%) | 6.9YoY -10% | 7.7 |
Why margins tightened on higher sales
A report from mcapital.in points to rising purchase and employee costs compressing operating margins. Total expenses grew 39.1% year-on-year, slightly outpacing the revenue increase. This suggests the company paid more for raw materials, a dynamic supported by broader food inflation trends.
The cash flow that tells a different story
The headline profit growth masks a significant strain on liquidity. For the half-year, SSMD Agrotech reported an operating cash outflow of ₹6.76 crore, according to Multibagg.ai. This was driven by a near-doubling of inventories and trade receivables since March, locking up roughly ₹38 crore in working capital.
The company partly funded this gap by increasing trade payables and short-term borrowings. This working capital intensity is a material concern for a company of its size, directly challenging the quality of its earnings growth.
Live Chart
· SSMD
(BSE)
ISIN: INE1U2R01013
The outlook: growth with a cash caveat
Management has not provided formal guidance, but the pace of expansion is expected to continue. mcapital.in estimates full-year revenue could grow 25-35% over FY26. However, the delayed deployment of IPO funds for new D2C stores and a namkeen plant may slightly temper near-term growth.
The key question is how long the working capital cycle will remain stretched. With food prices elevated and the company chasing volume, the cash conversion challenge may persist for at least another quarter or two.
Key Points
- Revenue grew 38.5% year-on-year to ₹72 crore, though it fell sequentially from a seasonally high base.
- Net profit increased 25% to ₹5 crore, but the net profit margin contracted by 80 basis points compared to Q2 FY26.
- Operating cash flow turned sharply negative to -₹6.76 crore for the half-year due to a major build-up in inventory and receivables.
- The company's growth is currently funded by increased supplier credit and short-term borrowings, highlighting a working capital strain.
Hexa Perspective
The quarter presents a classic growth-versus-quality trade-off. The top-line momentum is clear and likely supported by a firm pricing environment for agricultural commodities. Yet, the margin compression and, more critically, the severe cash absorption reveal the cost of that expansion.
Investors are weighing robust revenue growth against a balance sheet that is actively funding it. For the positive thesis to hold, SSMD Agrotech must demonstrate an ability to convert its sales into cash with greater efficiency in the coming quarters. Until then, the growth story carries a significant liquidity caveat.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.