SPA Capital Services (SPACAPS) Q2 FY27 Revenue Surges 79% YoY as Profit Slumps 57% QoQ
The financial distributor's September quarter revenue hit a five-quarter high, but a sharp drop in other income and rising costs squeezed profitability.
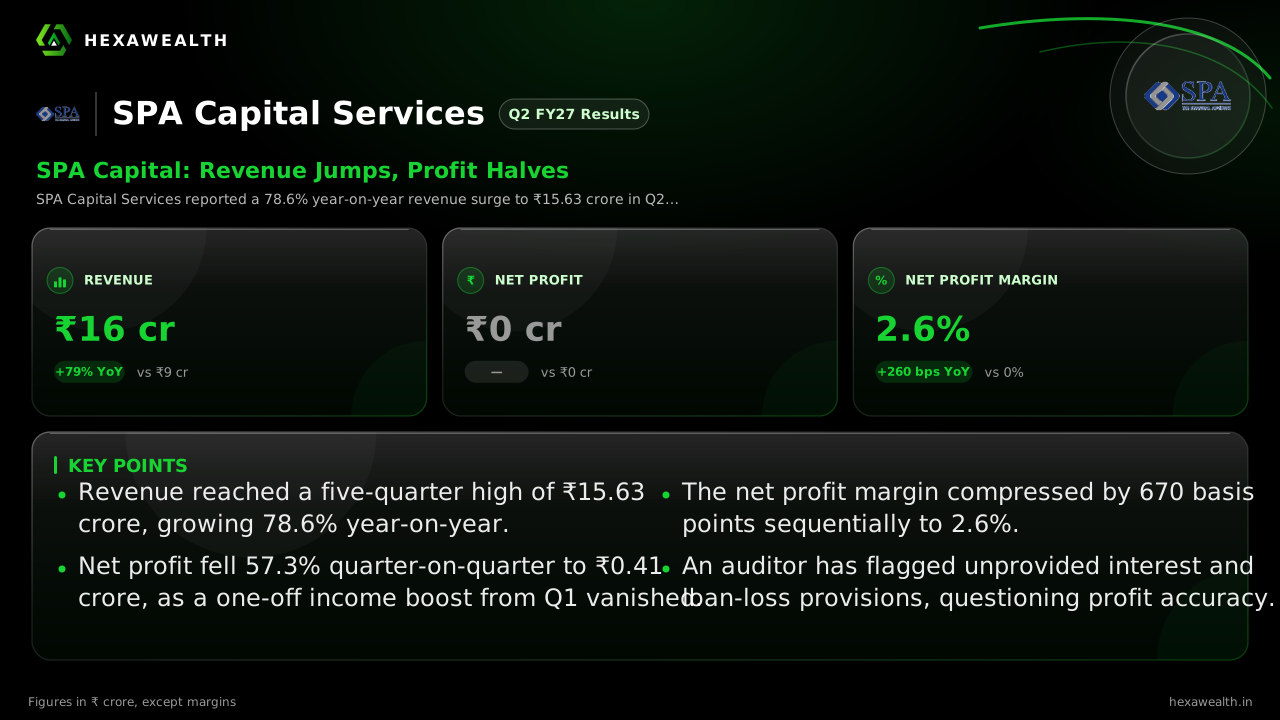
SPA Capital Services reported a 78.6% year-on-year revenue surge to ₹15.63 crore in Q2 FY27. However, net profit fell 57.3% sequentially to ₹0.41 crore as a one-off income boost from the previous quarter vanished and expenses climbed.
For SPA Capital Services, a small financial distributor, the September quarter delivered a powerful surge in business activity. Revenue jumped 79% from a year ago to ₹15.63 crore, a five-quarter high. Yet the bottom line tells a different story, with profit halving sequentially as a one-off income boost faded and costs rose faster than sales.
The numbers reveal a quarter of two halves. While the top line grew strongly, net profit fell 57% from the June quarter to ₹0.41 crore. The net profit margin compressed sharply to 2.6%, down 670 basis points from the previous quarter's 9.3%.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 15.63 | 10.30 |
| Net Profit (₹ Cr) | 0.41 | 0.96 |
| Net Profit Margin (%) | 2.6 | 9.3 |
The One-Off That Inflated Q1
The sharp profit drop stems largely from a 91.8% quarter-on-quarter collapse in other income, which fell to just ₹0.07 crore. This line item had contributed ₹0.91 crore in the June quarter, flattering that period's profitability. Without that boost, the underlying operating performance appears more consistent with the company's thin-margin history.
Costs Outpaced the Revenue Surge
Expenses rose 53.4% sequentially, slightly faster than the 51.7% revenue growth. Employee costs were up 29%, while depreciation and tax outflows also increased. According to analysis from StockFin.ai, the company's operating profit margins have historically hovered below 5%, indicating limited pricing power in its core distribution business.
The company's legacy NBFC loan book also presents a persistent challenge. An auditor's review, noted by StockFin.ai, flagged unprovided interest and loss-asset provisions that affect profit accuracy. This suggests reported earnings may be overstated relative to stricter RBI provisioning norms.
A Consolidation Phase With No Clear Catalyst
Management has not provided explicit forward guidance, according to StockFin.ai. The analysis suggests the company is in a consolidation phase with no clear catalyst for operational improvement. The absence of institutional investor holdings, as per the latest shareholding pattern, underscores the limited market confidence in its growth trajectory.
Key Points
- Revenue reached a five-quarter high of ₹15.63 crore, growing 78.6% year-on-year.
- Net profit fell 57.3% quarter-on-quarter to ₹0.41 crore, as a one-off income boost from Q1 vanished.
- The net profit margin compressed by 670 basis points sequentially to 2.6%.
- An auditor has flagged unprovided interest and loan-loss provisions, questioning profit accuracy.
Hexa Perspective
This quarter underscores the volatility and thin operating leverage in SPA Capital's fee-based distribution model. The revenue jump is positive but needs to be sustained across multiple quarters to signal a durable shift. The profit decline, while partly due to a high base of other income, highlights that core profitability remains fragile. Investors are weighing a revenue resurgence against persistent margin pressures and governance notes from the auditor. For the stock's premium valuation to hold, the company must demonstrate it can convert top-line growth into cleaner, more consistent bottom-line earnings.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.