Shukra Bullions (SKRABUL) Q2 FY27 Profit Plunges 86% Despite Sales Doubling
The jewellery and real estate firm saw revenue jump 39% year-on-year, but a massive surge in expenses crushed its net profit margin.
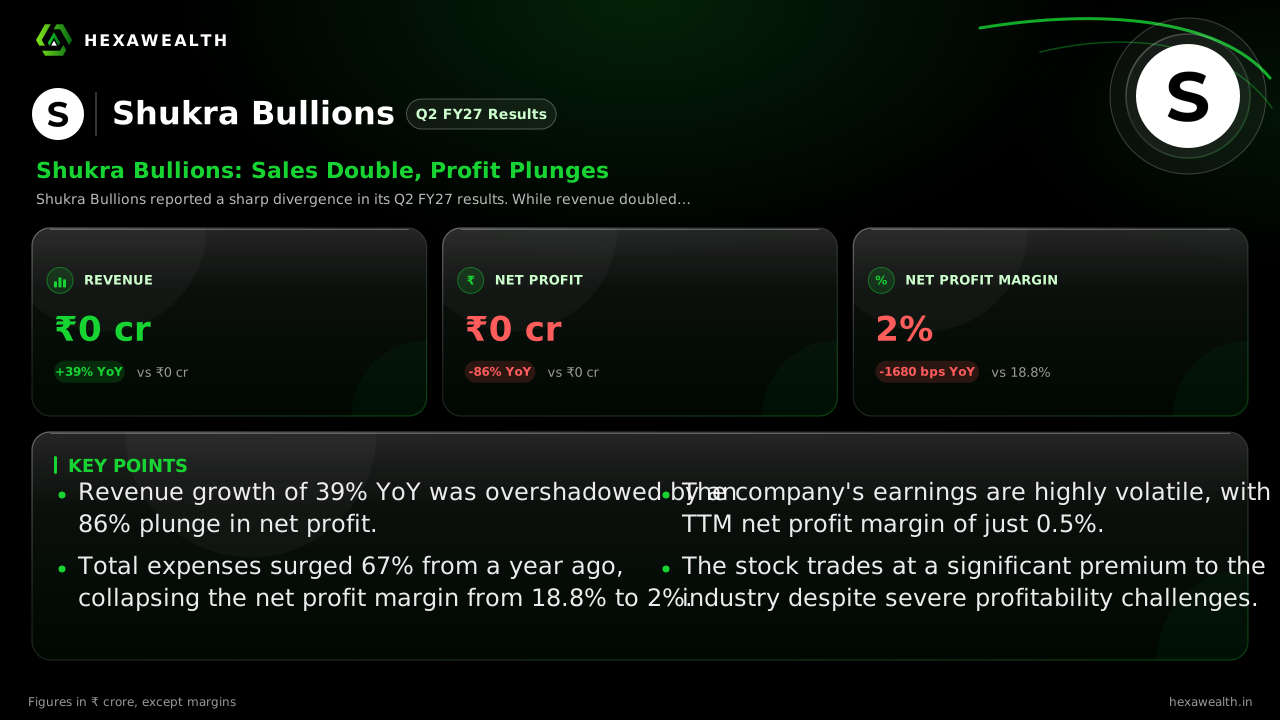
Shukra Bullions reported a sharp divergence in its Q2 FY27 results. While revenue doubled sequentially, profit fell 86% year-on-year as total expenses surged, squeezing the net profit margin to just 2%.
For Shukra Bullions, a multi-sector player in jewellery and real estate, the September quarter delivered a jarring split. Sales momentum was strong, but profitability collapsed under a surge in costs, highlighting the volatility in its core operations.
The numbers tell a story of two opposing forces. Revenue for Q2 FY27 came in at ₹0.5 crore, doubling from the previous quarter and rising 39% from a year ago. Yet, profit plummeted 86% year-on-year to just ₹0.01 crore. The net profit margin, once a healthy 18.8%, has been crushed to 2%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 0.50YoY +39% | 0.25 | 0.36 |
| Profit (₹ Cr) | 0.01YoY -86% | -0.02 | 0.07 |
| Net Profit Margin (%) | 2.0YoY -89% | -9.3 | 18.8 |
Where the profit vanished
The collapse in margin stems from a 67% year-on-year surge in total expenses, which grew even faster than sales. This suggests the revenue growth came at a significant cost, possibly from higher raw material prices or project-related spending in its real estate segment. The company's financials, as shown on Investing.com ZA, have historically shown wide swings in operating expenses.
This cost pressure aligns with a challenging industry backdrop. According to the World Gold Council, high gold prices pushed Indian jewellery demand down 20% by volume in Q3 2026. Consumers shifted towards lighter, studded pieces, a trend that may have supported Shukra's top line but likely compressed unit margins.
A volatile path ahead
The company's performance has been erratic, with profits swinging between losses and meagre gains over the past two years. Its trailing twelve-month net profit margin stands at just 0.5%, reflecting this instability. With no clear segment breakdown in the results, it's difficult to isolate whether jewellery or real estate is the primary driver—or drag.
Investors have taken note of the operational uncertainty. The stock, which closed at ₹38.36 near the results date, trades at a price-to-earnings multiple of 266, a 467% premium to its industry peers, as per the payload. This lofty valuation appears disconnected from the current reality of razor-thin and volatile earnings.
Key Points
- Revenue growth of 39% YoY was overshadowed by an 86% plunge in net profit.
- Total expenses surged 67% from a year ago, collapsing the net profit margin from 18.8% to 2%.
- The company's earnings are highly volatile, with a TTM net profit margin of just 0.5%.
- The stock trades at a significant premium to the industry despite severe profitability challenges.
Hexa Perspective
This quarter underscores Shukra Bullions' fundamental challenge: an inability to convert sales into stable profits. The severe margin contraction suggests the business lacks pricing power or cost control, likely exacerbated by high gold prices and competitive pressures in jewellery.
The extreme valuation premium seems to ignore this earnings fragility. For the stock to justify its multiple, the company must demonstrate it can grow revenue without a proportionate explosion in costs—a feat it has not achieved in recent quarters. Until then, the gap between price and performance remains stark.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.