SJS Enterprises Q2 FY27 Profit Dips 22% Sequentially as Land Sale Gain Fades
SJS Enterprises posted a 35% yearly profit jump but a sharp sequential drop as a one-time land sale gain from the prior quarter was not repeated.
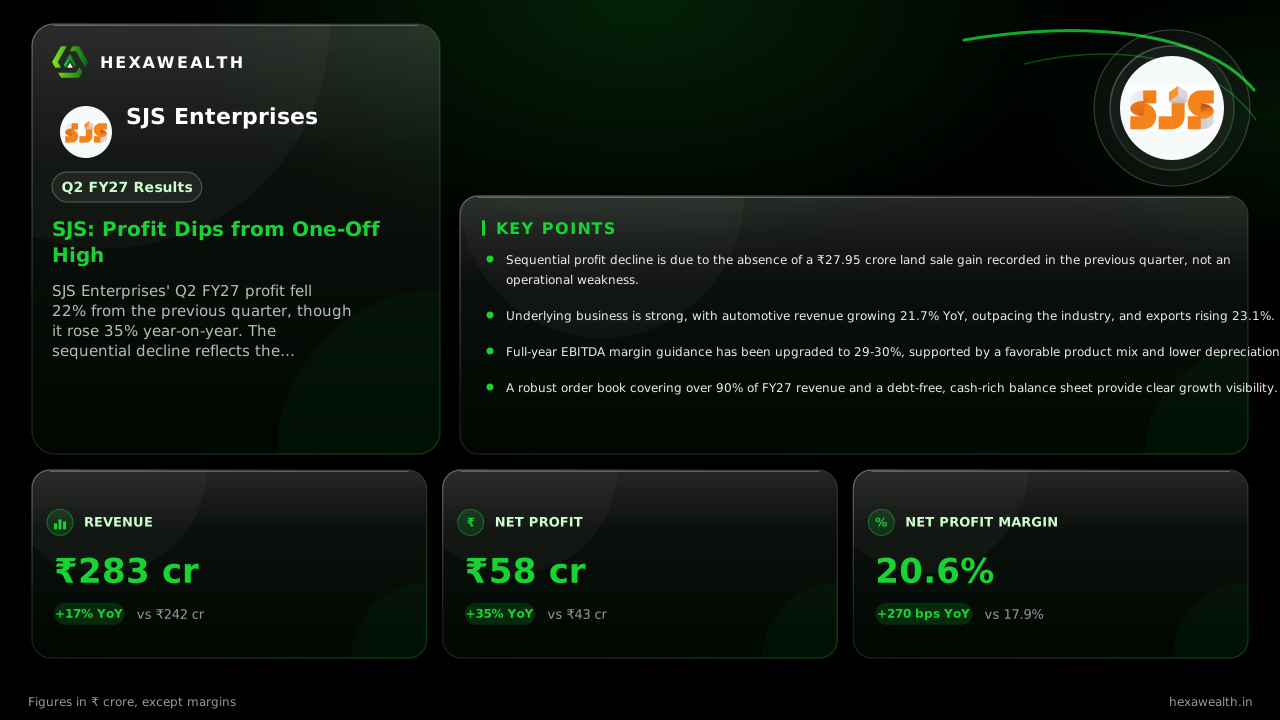
SJS Enterprises' Q2 FY27 profit fell 22% from the previous quarter, though it rose 35% year-on-year. The sequential decline reflects the absence of a one-off land sale gain, while underlying operations grew on strong automotive demand and exports.
SJS Enterprises’ story this quarter is one of two comparisons. Against a strong year-ago period, its core business of automotive aesthetics delivered robust growth. But the more telling view is sequential, where a significant one-off gain has now passed.
Revenue rose 16.9% year-on-year to ₹282.73 crore, while net profit climbed 34.8% to ₹58.33 crore. The net profit margin improved 270 basis points to 20.6%. Sequentially, however, profit fell 21.6% from ₹74.42 crore, and the margin dropped 790 basis points.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 282.73 | 261.00 |
| Profit (₹ Cr) | 58.33 | 74.42 |
| Net Profit Margin (%) | 20.6 | 28.5 |
The one-off that flattered Q1
The sharp sequential profit decline is not an operational setback. According to a filing noted by Blacklitt, the previous quarter included an exceptional item of ₹27.95 crore from the sale of a freehold land and building. This one-time gain in June 2026 made Q1's 28.5% net margin an unsustainable peak.
Stripping that out, the underlying profit trajectory remains healthy. The company's automotive business grew 21.7% year-on-year, outpacing industry production growth of 17.8%, as per the Scanx.trade report. Exports, a key focus, rose 23.1% and now contribute 10% of revenue.
A margin story driven by depreciation
Operational efficiency is showing. The EBITDA margin expanded 144 basis points year-on-year to 31.0%, reports Arthneeti. A key driver, as noted by Scanx.trade, was a 21.2% yearly drop in depreciation expense, as some assets became fully depreciated. This provided a direct boost to profitability independent of sales volume.
Management has raised its full-year EBITDA margin guidance to 29-30%, up from the earlier 27-28% range. This reflects confidence in cost control and a richer product mix from new export wins with Stellantis, Whirlpool, and Toyota Middle East.
The runway is visible
Visibility for the rest of the year is high. The company's order book for FY27 execution covers over 90% of its forecasted revenue. Management expects to grow revenue at 1.2 to 1.5 times the underlying passenger vehicle and motorcycle industry growth.
Capacity is being added to meet this demand. A ₹45 crore expansion at the Bengaluru plant is set for commercial production in Q3 FY27, as reported by Sahi.com. The balance sheet, with a net cash position of ₹331.9 crore, funds this growth without debt.
Key Points
- Sequential profit decline is due to the absence of a ₹27.95 crore land sale gain recorded in the previous quarter, not an operational weakness.
- Underlying business is strong, with automotive revenue growing 21.7% YoY, outpacing the industry, and exports rising 23.1%.
- Full-year EBITDA margin guidance has been upgraded to 29-30%, supported by a favorable product mix and lower depreciation.
- A robust order book covering over 90% of FY27 revenue and a debt-free, cash-rich balance sheet provide clear growth visibility.
Hexa Perspective
This quarter confirms SJS Enterprises' core strength: consistently growing faster than the auto industry it supplies. The market is now weighing a normalized profit run-rate against the elevated valuation from last quarter's one-off-aided peak. The raised margin guidance and secured order book suggest the underlying momentum is intact. The key watchpoint is the seamless ramp-up of new capacity to convert this strong pipeline into sustained, high-quality earnings over the coming quarters.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.