Sigma Solve (SIGMA) Q2 FY27 Profit Crashes 91% as One-Time Income Vanishes
Sigma Solve's Q2 net profit fell 91% sequentially as a large one-time income gain from the prior quarter disappeared, revealing underlying revenue pressure.
Sigma Solve's Q2 FY27 profit plummeted 91% from the previous quarter, falling to ₹1.13 crore. The crash follows the evaporation of a large one-time 'other income' gain that had flattered Q1 results, while core revenue also declined year-on-year.
For Sigma Solve, a strong prior quarter built on a one-off gain set up a harsh reality check. The September quarter saw profit collapse as that boost disappeared, while the core IT services business continued to face a tough demand environment.
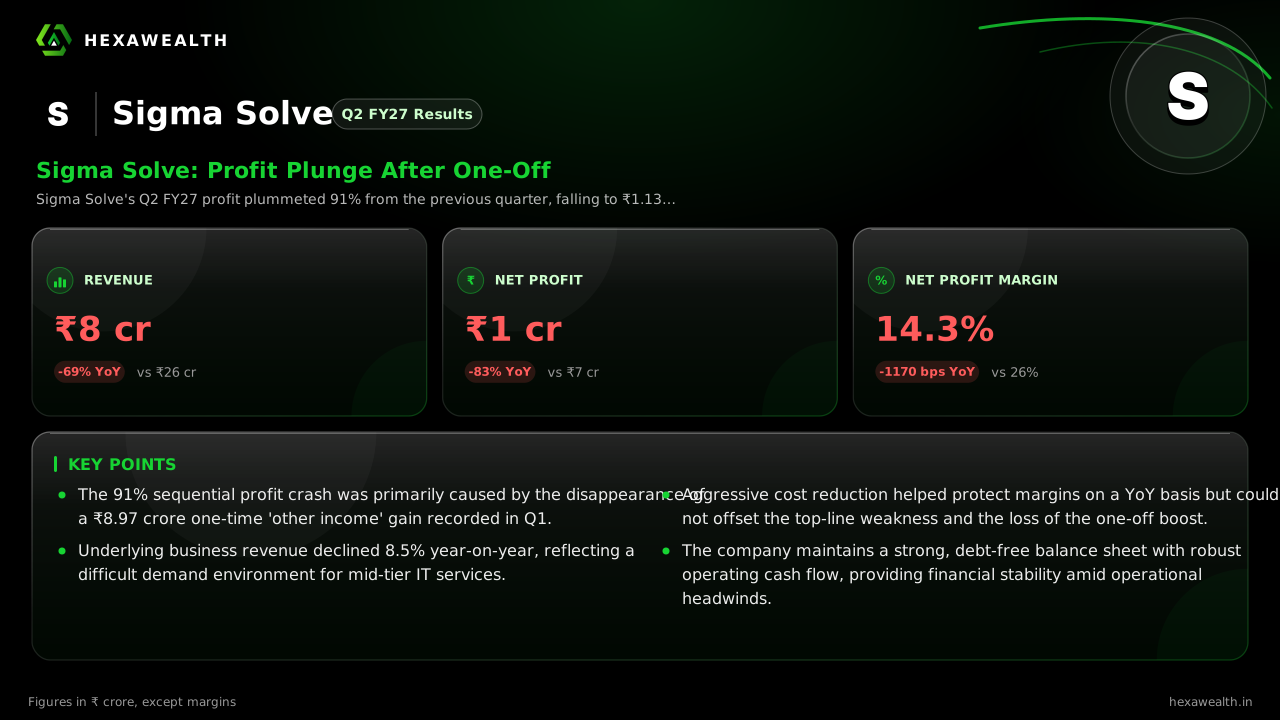
The numbers show a stark sequential reversal. Revenue fell 66% quarter-on-quarter to ₹7.88 crore, while net profit crashed 91% to ₹1.13 crore. The net profit margin plunged to 14.3% from an inflated 54.6% in Q1. Year-on-year comparisons are also weak, with revenue down 69% and profit down 83%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 7.88 | 23.03 |
| Profit (₹ Cr) | 1.13 | 12.57 |
| Net Profit Margin | 14.3% | 54.6% |
The One-Off That Distorted the Trend
The extreme QoQ swing is almost entirely due to 'other income'. According to data from flashfinance.news, this line item fell 99.8% sequentially to just ₹0.02 crore. In Q1, a one-time gain of ₹8.97 crore, as reported by Equity Bulls, had massively inflated total income and profit.
With that gain gone, the underlying business performance is laid bare. The company's revenue from operations, a clearer gauge of demand, declined 8.5% year-on-year to ₹23.41 crore, reports scanx.trade. Cost cuts provided some offset, but could not prevent the steep fall in absolute profit.
A Tough Market for Mid-Tier IT
The revenue decline reflects a challenging sector backdrop. A Crisil Ratings report cited by IANS notes that AI disruptions and weak discretionary spending will keep IT services growth muted for the next two fiscal years. Mid-tier firms like Sigma Solve face particular pressure on talent and pricing.
Despite the weak quarter, the balance sheet remains solid. The company generated positive operating cash flow of ₹13.05 crore in H1 FY27, per scanx.trade, and holds negligible debt. This financial stability provides a cushion, but does not solve the growth problem.
Key Points
- The 91% sequential profit crash was primarily caused by the disappearance of a ₹8.97 crore one-time 'other income' gain recorded in Q1.
- Underlying business revenue declined 8.5% year-on-year, reflecting a difficult demand environment for mid-tier IT services.
- Aggressive cost reduction helped protect margins on a YoY basis but could not offset the top-line weakness and the loss of the one-off boost.
- The company maintains a strong, debt-free balance sheet with robust operating cash flow, providing financial stability amid operational headwinds.
Hexa Perspective
The quarter reveals a company caught between a fading one-time tailwind and a slow-burn sectoral squeeze. The valuation, at a P/E of 15.7 against an industry average of 19.2, already prices in significant uncertainty.
The path forward hinges on revenue stabilization. Further cost cuts have limited runway, and the quality of the order book will be critical. Investors are weighing a clean but weak operating performance against the risk that the current demand drought persists longer than the balance sheet can comfortably support.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.