Repono (REPONO) Q4 FY26 Profit Jumps 43% But Cash Flow Remains a Drag
The oil storage specialist posted strong revenue and profit growth for the March quarter, but a deep operating cash outflow and rising receivables highlight a key challenge.
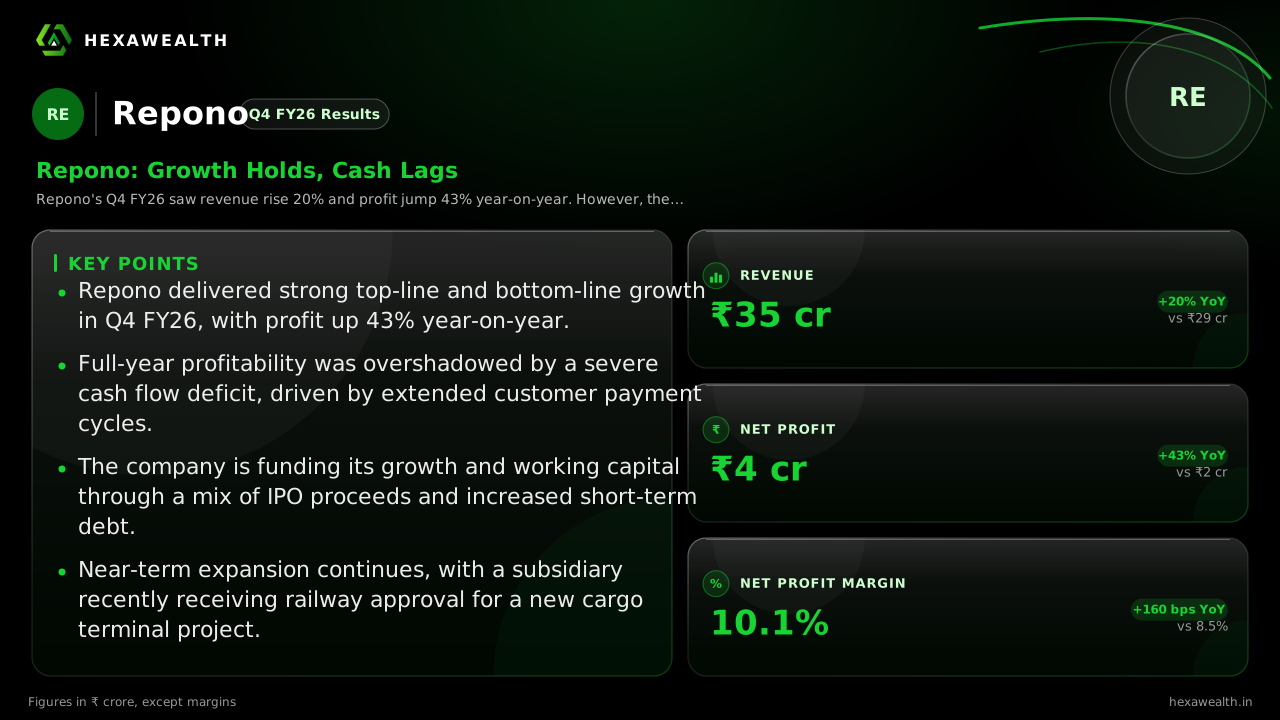
Repono's Q4 FY26 saw revenue rise 20% and profit jump 43% year-on-year. However, the full-year picture reveals a significant cash flow deficit, with operations consuming ₹15 crore despite a ₹6.6 crore profit.
For Repono, a specialist in operating oil and gas storage terminals, growth has been the consistent headline. The March quarter closed a year of explosive expansion, with revenue and profit surging from a much smaller base. Yet beneath this top-line strength, the cash conversion story tells a more complex tale of a business scaling while its working capital stretches.
The numbers show a quarter of robust performance. Revenue for Q4 FY26 reached ₹34.78 crore, up 19.9% from a year ago. Profit grew even faster, climbing 42.9% to ₹3.53 crore. This capped a full year where revenue multiplied over five times and profit over twelve times compared to FY23, albeit from a low base.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 22.12
- Revenue (₹ Cr), Q4 FY25: 29.00
- Revenue (₹ Cr), Q2 FY26: 30.49
- Revenue (₹ Cr), Q4 FY26: 34.78
- Profit (₹ Cr), Q2 FY25: 2.63
- Profit (₹ Cr), Q4 FY25: 2.47
- Profit (₹ Cr), Q2 FY26: 3.23
- Profit (₹ Cr), Q4 FY26: 3.53
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 22.12
- Revenue (₹ Cr), Q4 FY25: 29.00
- Revenue (₹ Cr), Q2 FY26: 30.49
- Revenue (₹ Cr), Q4 FY26: 34.78
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 2.63
- Profit (₹ Cr), Q4 FY25: 2.47
- Profit (₹ Cr), Q2 FY26: 3.23
- Profit (₹ Cr), Q4 FY26: 3.53
Net Profit Margin
- Net Profit Margin, Q2 FY25: 11.9%
- Net Profit Margin, Q4 FY25: 8.5%
- Net Profit Margin, Q2 FY26: 10.6%
- Net Profit Margin, Q4 FY26: 10.1%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 34.78YoY +20% | 29.00 |
| Profit (₹ Cr) | 3.53YoY +43% | 2.47 |
| Net Profit Margin | 10.1%YoY +19% | 8.5% |
The Margin Squeeze Behind Growth
While annual profit margins improved, the quarterly trend shows pressure. The net profit margin dipped 50 basis points from the September quarter. A report from MCapital notes higher employee costs are weighing on margins. Furthermore, depreciation expense surged 63% sequentially, likely linked to the company's ongoing capital expenditure program funded by its recent IPO proceeds.
Where the Profit Isn't Becoming Cash
The most striking figure from the full year is the cash flow. Despite a ₹6.58 crore net profit for FY26, cash flow from operations was deeply negative at ₹15.13 crore. This divergence is largely attributed to a build-up in receivables. Data from Newboard indicates debtor days stretched to 86 in FY26, meaning clients are taking nearly three months to pay on average.
This working capital drag is being funded. The company's short-term borrowings have risen, and it has utilised a significant portion of its IPO funds for working capital needs, as confirmed in a November 2026 board meeting outcome covered by MCapital. The market's read appears balanced, with the stock showing little sustained reaction immediately post-results.
Live Chart
· REPONO
(BSE)
ISIN: INE15WN01014
Key Points
- Repono delivered strong top-line and bottom-line growth in Q4 FY26, with profit up 43% year-on-year.
- Full-year profitability was overshadowed by a severe cash flow deficit, driven by extended customer payment cycles.
- The company is funding its growth and working capital through a mix of IPO proceeds and increased short-term debt.
- Near-term expansion continues, with a subsidiary recently receiving railway approval for a new cargo terminal project.
Hexa Perspective
The quarter confirms Repono's ability to win business and convert it to profit within its capital-light, service-heavy model. The concern is the model's cash conversion efficiency at scale. With receivables days climbing consistently, each new rupee of revenue ties up capital for longer.
The path forward hinges on whether this cash outflow is a temporary feature of rapid growth or a structural aspect of dealing with large, slow-paying clients in the oil sector. Investors are weighing solid profit growth against the need for continued external funding, with the stock's valuation at a steep discount to the industry average reflecting this tension.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.