(RAMCOCEM) Q2 FY27 Ramco Cements Profit Halves Despite 10% Revenue Growth
The cement maker's September quarter profit fell 48% year-on-year as soaring fuel and packing costs from the West Asia conflict squeezed margins.
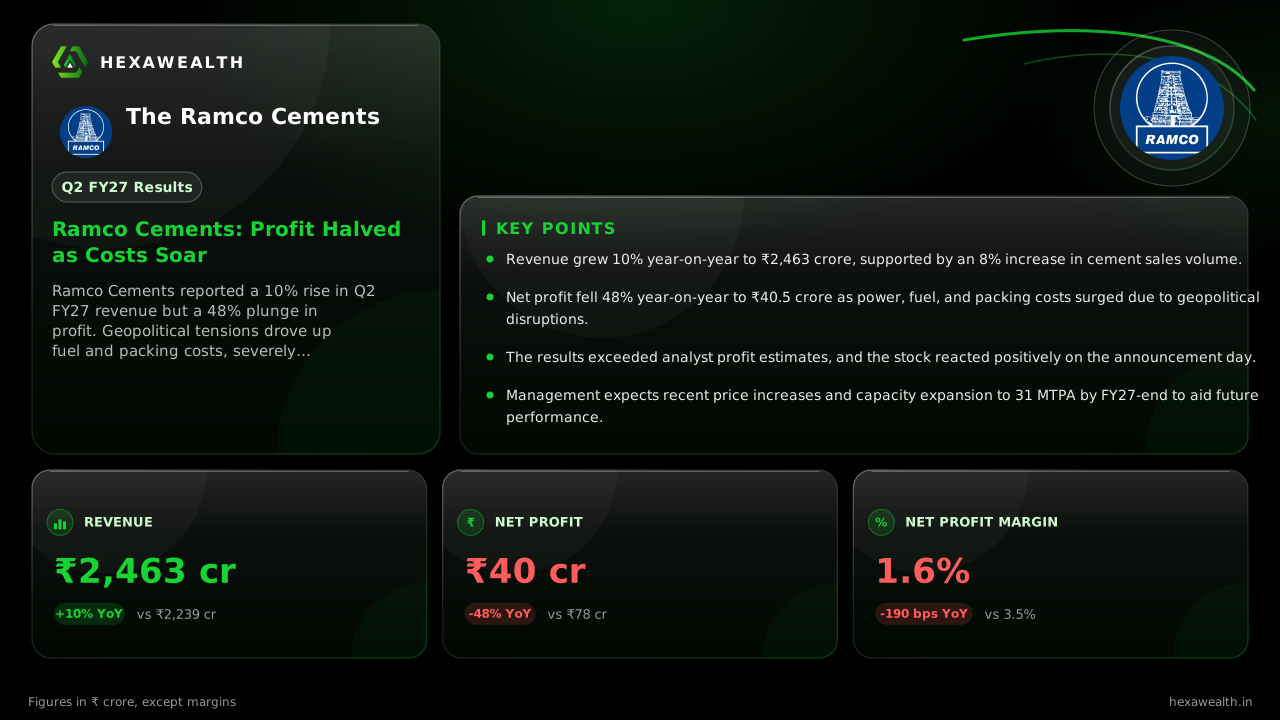
Ramco Cements reported a 10% rise in Q2 FY27 revenue but a 48% plunge in profit. Geopolitical tensions drove up fuel and packing costs, severely compressing margins despite healthy volume growth.
For cement producers, the ability to pass on rising costs defines a quarter. The Ramco Cements saw its sales volumes grow 8% to 4.74 million tonnes, driving a 10% revenue increase. Yet, profit before tax nearly halved, revealing a margin squeeze that volume could not overcome.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 2,462.75YoY +10% | 2,273.05 | 2,238.74 |
| Profit (₹ Cr) | 40.46YoY -48% | 31.24 | 77.88 |
| PAT Margin | 1.6%YoY -54% | 1.4% | 3.5% |
Sequentially, profit improved 30% from a low base. The net profit margin, however, remains a thin 1.6%, down 190 basis points from a year ago.
Why the top line did not reach the bottom
The gap between sales and profit was filled by a 13% jump in total expenses. According to CNBC-TV18, power and fuel cost per tonne surged 36% year-on-year to ₹1,397. Blended fuel consumption cost hit $140 per tonne, up from $122, worsened by a 10% rupee depreciation.
Packing material costs also rose sharply. Informist Media reported a 30% year-on-year increase linked to higher polymer prices. The company also incurred a ₹33 crore cost from a disputed Tamil Nadu limestone levy, paid under protest.
A market reading the fine print
Despite the profit decline, the print beat analyst estimates. Informist Media noted the net profit of ₹381.8 million comfortably exceeded the expected ₹176.7 million. Revenue also came in ahead of projections.
This beat, coupled with management's guidance for price increases in October, likely supported the stock. Shares closed over 5% higher on the results day, according to Informist.
Brokerages acknowledged the beat but see near-term pressure. Motilal Oswal retained a 'Neutral' rating with a target of ₹850, citing high coal costs. Antique Stock Broking lowered its target to ₹890 but kept a 'Hold', calling the performance weak.
The path to recovery
Management is banking on price hikes and capacity expansion. Motilal Oswal's report notes cement prices increased across south and east regions in October. The company is also holding lower fuel inventory, awaiting a correction.
Capacity is targeted to reach 31 million tonnes per annum by March 2027. Full-year capital expenditure guidance stands at ₹800 crore, as per the company's investor presentation. A disciplined capex and ongoing non-core asset monetization are expected to support debt reduction.
Key Points
- Revenue grew 10% year-on-year to ₹2,463 crore, supported by an 8% increase in cement sales volume.
- Net profit fell 48% year-on-year to ₹40.5 crore as power, fuel, and packing costs surged due to geopolitical disruptions.
- The results exceeded analyst profit estimates, and the stock reacted positively on the announcement day.
- Management expects recent price increases and capacity expansion to 31 MTPA by FY27-end to aid future performance.
Hexa Perspective
This quarter underscores a cement industry truism: volume growth alone cannot defend profitability against runaway input costs. The sequential profit improvement is a fragile base, dependent on the sustainability of October's price hikes in a seasonally stronger quarter. Investors are weighing the company's operational execution and debt reduction plans against a still-volatile cost outlook. The margin recovery thesis now hinges on a dual track: successful price realization in the market and a meaningful retreat in global fuel prices.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.