PVV Infra (PVVINFRA) Q2 FY27 Profit Slumps 61% as Costs Bite into Thin Margins
The infrastructure firm's revenue grew 2.3% YoY, but a sharp rise in material costs and interest expense led to a steep 61% fall in net profit for Q2 FY27.
PVV Infra's September quarter shows a stark divergence: revenue inched up 2.3% year-on-year, but net profit plunged 61%. Surging material costs and a sudden interest expense crushed margins, while cash flow turned negative as receivables swelled.
For an infrastructure EPC company, the quarter is judged on its ability to convert project execution into profit. PVV Infra's Q2 FY27 showed that conversion breaking down, with revenue growth failing to reach the bottom line.
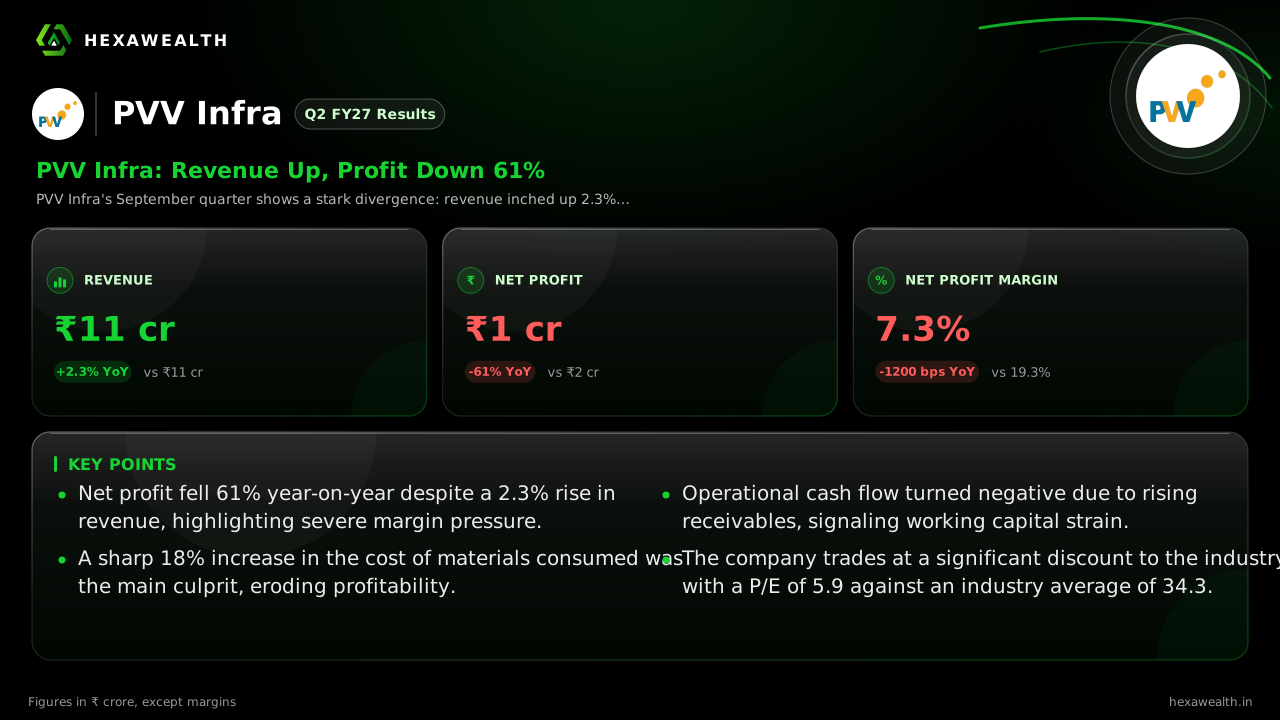
The numbers tell a story of severe margin compression. Revenue was ₹11.18 crore, a slight 2.3% increase from last year. Profit, however, collapsed to ₹0.82 crore, down 61% year-on-year. The net profit margin shrank by 1200 basis points to just 7.3%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Revenue (₹ Cr), Q2 FY26: 10.93
Revenue (₹ Cr), Q3 FY26: 16.24
Revenue (₹ Cr), Q4 FY26: 21.64
Revenue (₹ Cr), Q1 FY27: 8.50
Revenue (₹ Cr), Q2 FY27: 11.18
Profit (₹ Cr), Q2 FY26: 2.11
Profit (₹ Cr), Q3 FY26: 4.21
Profit (₹ Cr), Q4 FY26: 0.09
Profit (₹ Cr), Q1 FY27: 0.77
Profit (₹ Cr), Q2 FY27: 0.82
Revenue (₹ Cr)
Revenue (₹ Cr), Q2 FY26: 10.93
Revenue (₹ Cr), Q3 FY26: 16.24
Revenue (₹ Cr), Q4 FY26: 21.64
Revenue (₹ Cr), Q1 FY27: 8.50
Revenue (₹ Cr), Q2 FY27: 11.18
Profit (₹ Cr)
Profit (₹ Cr), Q2 FY26: 2.11
Profit (₹ Cr), Q3 FY26: 4.21
Profit (₹ Cr), Q4 FY26: 0.09
Profit (₹ Cr), Q1 FY27: 0.77
Profit (₹ Cr), Q2 FY27: 0.82
Metric
CurrentQ2 FY27
PreviousQ1 FY27
Same quarter LYQ2 FY26
Revenue (₹ Cr)
11.18YoY +2.3%
8.50
10.93
Profit (₹ Cr)
0.82YoY -61%
0.77
2.11
PAT Margin (%)
7.3YoY -62%
9.1
19.3
The cost surge that erased profits
The primary driver was a sharp rise in input costs. According to a report by scanx.trade, the cost of materials consumed jumped to ₹8.43 crore from ₹7.15 crore a year ago. This 18% increase significantly outpaced the modest revenue growth.
A new and notable pressure came from finance costs, which surged to ₹0.21 crore from a negligible ₹0.02 crore last year. This suggests the company may be taking on more debt to fund operations or new projects.
A cash flow warning signal
Perhaps more concerning than the profit drop is the state of cash generation. While the company reported a profit, its operational cash flow turned negative. Scanx.trade notes this was driven by a significant increase in trade receivables, meaning revenue was recognized but cash wasn't collected.
Live Chart
· PVVINFRA
(BSE)
ISIN: INE428B01021
This points to potential working capital stress, a critical issue for capital-intensive contractors. The company's current ratio of 0.51, as per the payload, confirms tight liquidity.
A quiet outlook in a tough market
Management provided no forward guidance in the latest filings, according to stockfin.ai. This silence comes amid a challenging environment for affordable housing and industrial EPC, where rising construction costs are squeezing viability.
Industry reports, like one from CareEdge cited by Asianet News, note that prolonged high crude prices could raise construction costs by 2-3%, weighing further on players like PVV Infra.
Key Points
Net profit fell 61% year-on-year despite a 2.3% rise in revenue, highlighting severe margin pressure.
A sharp 18% increase in the cost of materials consumed was the main culprit, eroding profitability.
Operational cash flow turned negative due to rising receivables, signaling working capital strain.
The company trades at a significant discount to the industry, with a P/E of 5.9 against an industry average of 34.3.
“
Hexa Perspective
This quarter underscores a fundamental operational challenge. Revenue growth is meaningless if it comes at the expense of profitability and cash flow. The margin collapse from over 19% to 7% in a year is a dramatic shift that demands explanation.
The path forward hinges on two factors: securing new projects at better margins and improving cash collection to ease the working capital crunch. Until those are demonstrated, the deep valuation discount reflects justified investor skepticism about the business's current economics.
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
Frequently asked questions
What were PVV Infra's Q2 FY27 results?
PVV Infra reported revenue of ₹11.18 crore and a net profit of ₹0.82 crore for the quarter ended September 2026. While revenue grew 2.3% year-on-year, net profit fell sharply by 61.1% due to significantly higher costs.
Why did PVV Infra's Q2 FY27 profit fall 61% year-on-year?
PVV Infra's Q2 FY27 profit fell 61% primarily due to a sharp increase in the cost of materials consumed, which rose to ₹8.43 crore from ₹7.15 crore a year ago. This cost surge, alongside a new interest expense, severely compressed profit margins.
What caused the 1200 basis point collapse in PVV Infra's net profit margin in Q2 FY27?
The 1200 basis point margin collapse for PVV Infra in Q2 FY27 was caused by costs rising much faster than revenue. The cost of materials consumed jumped 18% year-on-year, significantly outpacing the 2.3% revenue growth and eroding profitability.
Was the 31.5% QoQ revenue growth for PVV Infra in Q2 FY27 driven by a specific project?
The quarterly results filing and related reports from Investywise and scanx.trade do not specify a particular project driving the 31.5% sequential revenue growth. The growth appears to be a recovery from a low base in the previous quarter (Q1 FY27 revenue was ₹8.5 crore).
Why did PVV Infra's interest expense surge in Q2 FY27?
PVV Infra's finance costs surged to ₹0.21 crore in Q2 FY27 from a negligible ₹0.02 crore last year. While not explicitly stated, this significant increase suggests the company may have taken on new debt to fund its operations or capital expenditures during the period.
What is the status of PVV Infra's order book as of Q2 FY27?
The Q2 FY27 results announcement did not disclose a current order book value. A separate filing noted the company secured a ₹2.49 crore work order from NHLML in July 2026, but there is no visibility on a larger backlog to sustain future revenue.
Does PVV Infra have sufficient working capital given its low current ratio?
PVV Infra's current ratio of 0.51 indicates working capital is tight, with current liabilities exceeding current assets. Reports from scanx.trade also note negative operating cash flow in Q2 due to rising receivables, further stressing liquidity for operations.
What was PVV Infra management's guidance for FY27?
PVV Infra's management did not provide any forward-looking guidance on revenue, margins, or growth in the Q2 FY27 results filings or associated commentary, as noted in an analysis by stockfin.ai.
Is PVV Infra planning any major capacity expansion or capex?
There is no announcement of major capacity expansion in the recent results. However, scanx.trade reported significant cash outflows for investing activities, including loans to other parties and investment in property, plant, and equipment.
Did PVV Infra's Q2 FY27 results beat analyst estimates?
The available research from Investywise and flashfinance.news does not cite specific analyst estimates for PVV Infra's Q2 FY27 results, so a beat or miss cannot be determined. The reports focus on the steep year-on-year decline in profit.
Have any major brokerages changed their rating for PVV Infra after Q2 results?
The research conducted did not uncover any reports of major brokerages changing their rating or target price for PVV Infra immediately following the Q2 FY27 results announcement.
How did PVV Infra's stock price react to the Q2 FY27 results?
Specific day-of reaction data isn't provided, but flashfinance.news noted the broader market median was up 0.6% post-results. PVV Infra's stock had fallen 52.3% over the past year leading up to the announcement.
Are there any specific project delays or client concentration risks affecting PVV Infra?
A report by scanx.trade on a recent ₹2.49 crore order noted a high client concentration risk, as the awarding client (NHLML) represented 100% of the visible near-term backlog. It also flagged execution risk due to low margins and negative historical cash flow.
What caused the sharp sequential drop in revenue from Q4 FY26 to Q1 FY27?
The payload shows revenue fell from ₹21.64 crore in Q4 FY26 to ₹8.50 crore in Q1 FY27. The research does not specify a cause, but such volatility is typical in project-based businesses and may indicate the completion of a large project in Q4 without immediate replacement.
Were there any one-off gains in PVV Infra's Q2 FY26 profit of ₹2.11 crore?
Reports from Tradebrains and Balaji Equities on PVV Infra's Q2 FY26 results highlight massive year-on-year growth percentages from a very low base but do not mention any exceptional or one-off items that inflated the ₹2.11 crore profit for that quarter.