Purple United Sales (PURPLEUTED) Q2 FY27 Profit Slips 20% as Expansion Costs Outpace Revenue
The kids' fashion retailer posted 104% YoY revenue growth, but a sharp rise in interest and employee costs drove a sequential profit drop and margin squeeze.
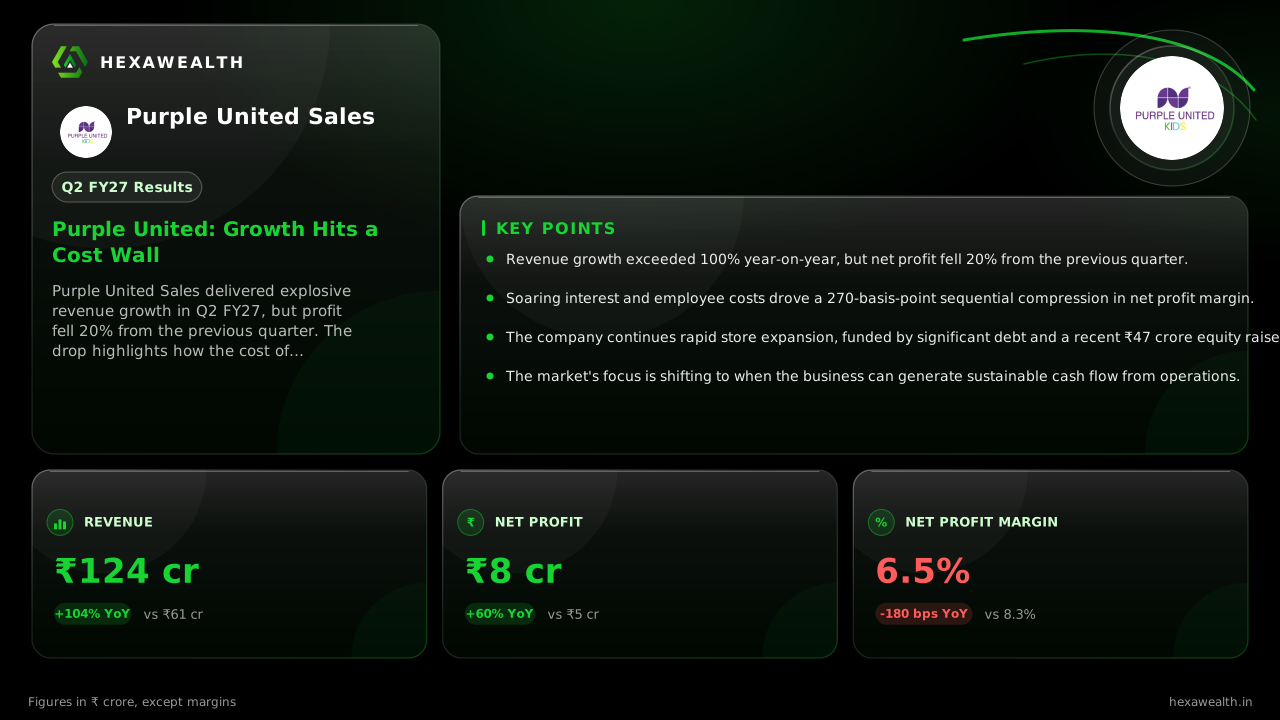
Purple United Sales delivered explosive revenue growth in Q2 FY27, but profit fell 20% from the previous quarter. The drop highlights how the cost of funding rapid store expansion is now biting into profitability.
For Purple United Sales, growth is no longer just about opening stores. The kids' fashion retailer's second quarter shows the cost of that ambition arriving ahead of the payoff. Revenue more than doubled year-on-year, but profit fell sharply from the previous quarter as expenses for new outlets and the debt to fund them surged.
The numbers tell a story of two speeds. Revenue hit ₹123.7 crore, up 104% from a year ago and 13% from the March quarter. Yet net profit fell to ₹8.1 crore, down 20% sequentially even as it rose 60% year-on-year. The net profit margin compressed to 6.5%, down 270 basis points from the prior quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 72.63
- Revenue (₹ Cr), Q2 FY26: 60.73
- Revenue (₹ Cr), Q4 FY26: 109.90
- Revenue (₹ Cr), Q2 FY27: 123.66
- Profit (₹ Cr), Q4 FY25: 7.18
- Profit (₹ Cr), Q2 FY26: 5.05
- Profit (₹ Cr), Q4 FY26: 10.14
- Profit (₹ Cr), Q2 FY27: 8.09
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY25: 72.63
- Revenue (₹ Cr), Q2 FY26: 60.73
- Revenue (₹ Cr), Q4 FY26: 109.90
- Revenue (₹ Cr), Q2 FY27: 123.66
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY25: 7.18
- Profit (₹ Cr), Q2 FY26: 5.05
- Profit (₹ Cr), Q4 FY26: 10.14
- Profit (₹ Cr), Q2 FY27: 8.09
Net Profit Margin
- Net Profit Margin, Q4 FY25: 9.9%
- Net Profit Margin, Q2 FY26: 8.3%
- Net Profit Margin, Q4 FY26: 9.2%
- Net Profit Margin, Q2 FY27: 6.5%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 123.66YoY +104% | 60.73 |
| Profit (₹ Cr) | 8.09YoY +60% | 5.05 |
| Net Profit Margin | 6.5%YoY -22% | 8.3% |
Why Profitability Is Under Pressure
The margin squeeze stems from costs rising faster than sales. Total expenses jumped 18% quarter-on-quarter, outpacing the 13% revenue growth. Two items stood out: interest expense soared 64% to ₹9.6 crore, and employee costs rose 18% to ₹15.7 crore.
According to a report from newboard.in, borrowings ballooned to ₹86.7 crore by March 2026 to fund store expansion. Each new store requires about ₹70 lakh for fit-out and initial stock. This heavy reliance on debt is now flowing directly to the income statement, eroding margins.
The Expansion Engine and Its Fuel
Management remains committed to aggressive growth. On a May 2026 earnings call, Managing Director Jatinder Dev Seth said the company aims to double its store footprint in FY27 and target 100% annual revenue growth for two years, as noted by Inve.money. The store count reached 130 by October.
Live Chart
· PURPLEUTED
(BSE)
ISIN: INE0P5R01014
This growth is being funded by a mix of debt and fresh equity. In October, the company allotted shares and warrants to raise ₹47.2 crore, as reported by Alfafinder.com. The capital is needed; a Crisil Ratings analysis cited by Fibre2Fashion notes the broader apparel sector faces margin pressure from rising cotton and operating costs.
A Market Waiting for Cash Flow
The stock lacks coverage from major brokerages, and institutional ownership is minimal. Data from The Economic Times shows FIIs hold 0% and DIIs just 0.34% as of September 2026. Investors appear to be watching for a crucial milestone: the company turning cash flow positive.
Management has guided for operations to generate cash within 12 to 18 months from May 2026, per the newboard.in report. Until that happens, the disconnect between reported profits and cash burn will remain a key concern for the market.
Key Points
- Revenue growth exceeded 100% year-on-year, but net profit fell 20% from the previous quarter.
- Soaring interest and employee costs drove a 270-basis-point sequential compression in net profit margin.
- The company continues rapid store expansion, funded by significant debt and a recent ₹47 crore equity raise.
- The market's focus is shifting to when the business can generate sustainable cash flow from operations.
Hexa Perspective
This quarter lays bare the trade-off in Purple United's model. The revenue engine is powerful, driven by a successful pivot to owned retail. Yet profitability is being sacrificed to fund that growth, with interest expense becoming a material drag.
The path forward hinges on two factors: the pace at which new stores mature to contribute meaningfully to profit, and the company's ability to moderate its reliance on debt. Management's guidance for positive operating cash flow in the coming year is the line to watch. If achieved, it could validate the expansion strategy. If delayed, the cost of capital could further weigh on already-thin margins.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.