NDL Ventures (NDLVENTURE) Q2 FY27 Profit Jumps on Merger, but High Debt Clouds Outlook
The Hinduja Leyland Finance merger transformed NDL Ventures' scale, but a massive interest bill and a weak balance sheet raise sustainability questions.
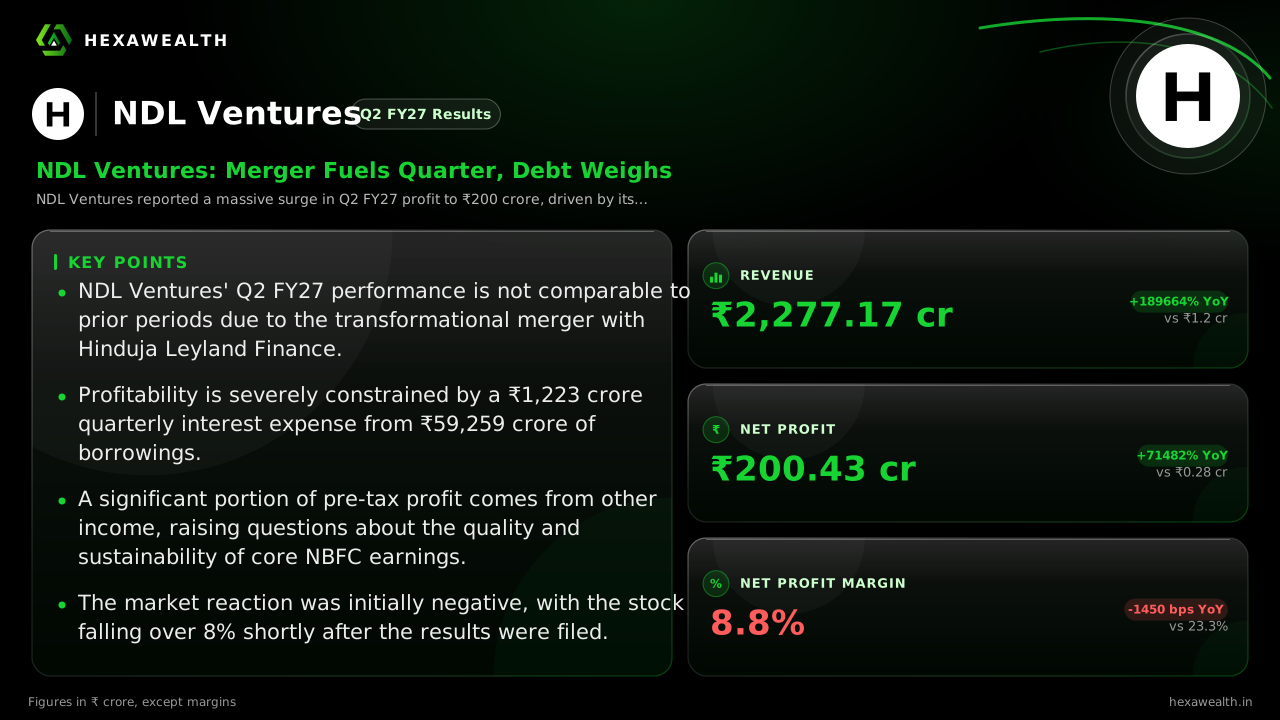
NDL Ventures reported a massive surge in Q2 FY27 profit to ₹200 crore, driven by its merger with Hinduja Leyland Finance. However, a ₹1,223 crore interest expense and heavy reliance on other income highlight significant structural challenges.
NDL Ventures' September quarter results mark a complete transformation, but one that comes with a steep price tag. The company's consolidation of Hinduja Leyland Finance has created a financial services entity, yet the underlying economics reveal a business under severe pressure from its own balance sheet.
The numbers showcase the scale change. Revenue soared to ₹2,277 crore from just ₹1.2 crore a year ago, while net profit reached ₹200.4 crore. The catch lies in the margins and the cost structure that delivered them.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1.20
- Revenue (₹ Cr), Q3 FY26: 1.26
- Revenue (₹ Cr), Q4 FY26: 1.27
- Revenue (₹ Cr), Q1 FY27: 1.27
- Revenue (₹ Cr), Q2 FY27: 2,277.17
- Profit (₹ Cr), Q2 FY26: 0.28
- Profit (₹ Cr), Q3 FY26: 0.23
- Profit (₹ Cr), Q4 FY26: 0.15
- Profit (₹ Cr), Q1 FY27: 0.09
- Profit (₹ Cr), Q2 FY27: 200.43
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 1.20
- Revenue (₹ Cr), Q3 FY26: 1.26
- Revenue (₹ Cr), Q4 FY26: 1.27
- Revenue (₹ Cr), Q1 FY27: 1.27
- Revenue (₹ Cr), Q2 FY27: 2,277.17
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 0.28
- Profit (₹ Cr), Q3 FY26: 0.23
- Profit (₹ Cr), Q4 FY26: 0.15
- Profit (₹ Cr), Q1 FY27: 0.09
- Profit (₹ Cr), Q2 FY27: 200.43
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26: 23.3
- Net Profit Margin (%), Q3 FY26: 18.5
- Net Profit Margin (%), Q4 FY26: 12.0
- Net Profit Margin (%), Q1 FY27: 7.0
- Net Profit Margin (%), Q2 FY27: 8.8
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 2,277.17YoY +189664% | 1.27 | 1.20 |
| Profit (₹ Cr) | 200.43YoY +71482% | 0.09 | 0.28 |
| Net Profit Margin (%) | 8.8YoY -62% | 7.0 | 23.3 |
The Merger's Heavy Toll
The primary driver was the merger with Hinduja Leyland Finance, effective April 1, 2026. MarketPing notes the results were prepared after giving effect to this scheme, which brought in a large loan book and assets. This instantly shifted the company from a tiny media operation to a mid-sized NBFC.
However, the new business came with a massive ₹59,259 crore in borrowings. The interest cost alone was ₹1,223 crore for the quarter, as reported by AlphaTribe. This enormous fixed charge consumed most of the operating profit, compressing the net margin to 8.8%, far below the 23.3% from a year ago when the company was minuscule.
A Question of Earnings Quality
A MarketsMojo analysis flags a critical concern: earnings quality. Other income of ₹87.3 crore contributed over 30% of the profit before tax. For an NBFC, such heavy reliance on non-core income raises doubts about the sustainability of profits from its core lending operations.
Live Chart
· NDLVENTURE
(BSE)
ISIN: INE353A01023
The balance sheet shows the strain. The company's current ratio is a tight 0.29, indicating limited short-term liquidity against obligations. While the stock closed nearly flat on the results day, MarketPing data shows it fell sharply in the minutes after the filing, suggesting investor unease.
Key Points
- NDL Ventures' Q2 FY27 performance is not comparable to prior periods due to the transformational merger with Hinduja Leyland Finance.
- Profitability is severely constrained by a ₹1,223 crore quarterly interest expense from ₹59,259 crore of borrowings.
- A significant portion of pre-tax profit comes from other income, raising questions about the quality and sustainability of core NBFC earnings.
- The market reaction was initially negative, with the stock falling over 8% shortly after the results were filed.
Hexa Perspective
This quarter is a reset, not an operating result. The reported figures are the first snapshot of a completely different company. The story now hinges on whether the acquired loan book can generate enough net interest income to cover its own massive cost of funds.
The high debt load and thin equity base create a fragile structure. Any stress in asset quality could quickly amplify losses. Investors are rightly looking past the headline profit surge to the underlying leverage, which will dictate all future performance.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.