Meenakshi Steel (MEENST) Q2 FY27 Profit Crashes 81% as Borrowing Costs Swallow Income
The NBFC's quarterly profit fell to ₹0.11 crore as surging interest expenses consumed over 94% of its total income, highlighting a severe margin squeeze.
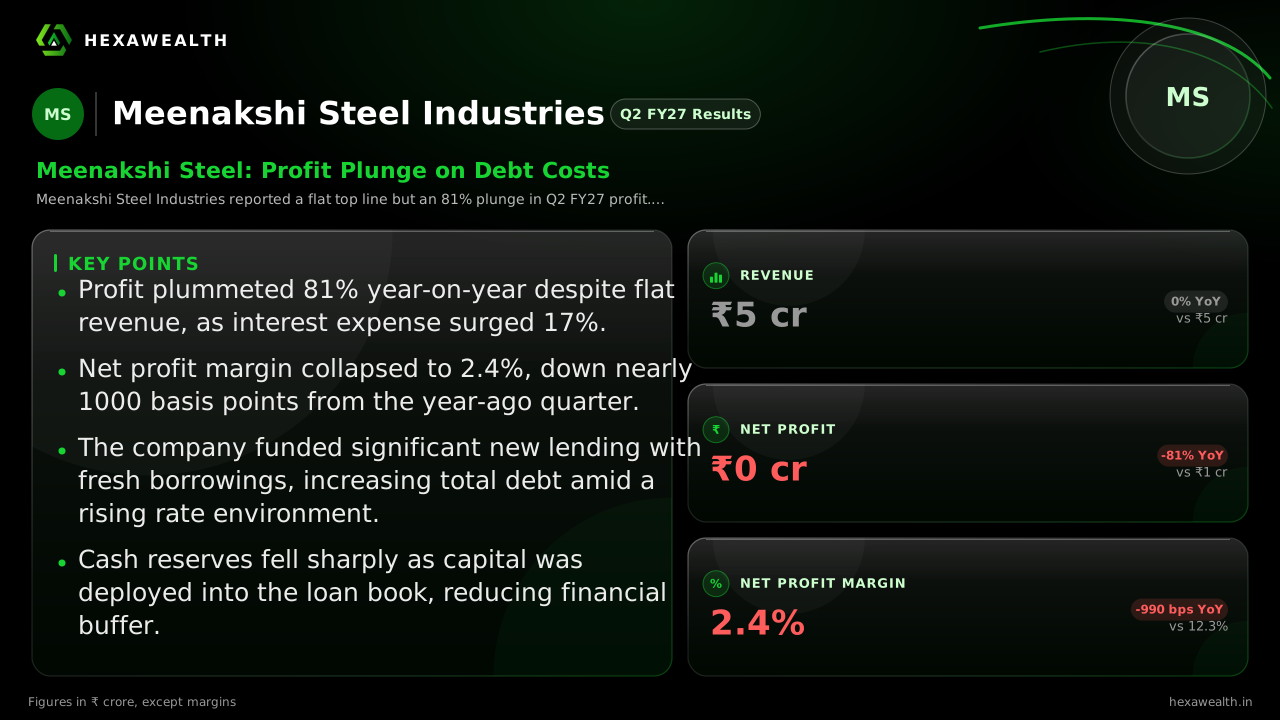
Meenakshi Steel Industries reported a flat top line but an 81% plunge in Q2 FY27 profit. Surging finance costs, which rose nearly 17% year-on-year, devoured nearly all operating income, slashing the net profit margin to just 2.4%.
For a non-banking finance company, the spread between what it earns on loans and what it pays to fund them is everything. Meenakshi Steel Industries’ second quarter shows that spread collapsing under the weight of its own debt. Profit before tax fell 79% year-on-year to ₹0.17 crore, as a stable revenue line of ₹4.81 crore was entirely consumed by rising costs.
The numbers tell a story of stagnation being overwhelmed by expense. Revenue was exactly flat compared to last September. Yet profit fell to ₹0.11 crore, down 81% from a year ago and 59% from the June quarter. The net profit margin, once a healthy 12.3%, has been compressed to just 2.4%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 4.81
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 5.80
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 4.23
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 4.72
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 4.81
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.59
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 0.79
- Profit (₹ Cr), Q4 FY26 (Mar 2026): -0.49
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 0.27
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.11
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 4.81
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 5.80
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 4.23
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 4.72
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 4.81
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.59
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 0.79
- Profit (₹ Cr), Q4 FY26 (Mar 2026): -0.49
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 0.27
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 0.11
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep 2025): 12.3%
- Net Profit Margin, Q3 FY26 (Dec 2025): 13.6%
- Net Profit Margin, Q4 FY26 (Mar 2026): -11.6%
- Net Profit Margin, Q1 FY27 (Jun 2026): 5.7%
- Net Profit Margin, Q2 FY27 (Sep 2026): 2.4%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 4.81 | 4.72 |
| Profit (₹ Cr) | 0.11 | 0.27 |
| Net Profit Margin | 2.4% | 5.7% |
Why the bottom line vanished
A single line item explains the devastation: interest expense. Finance costs surged 16.9% year-on-year to ₹4.54 crore, according to the company's filings. A report from ScanX notes these costs now constitute over 94% of total income for the quarter. The company is essentially working to service its debt, with little left for shareholders.
This cost surge came even as the company aggressively lent more. ScanX reported the company granted ₹17.46 crore in new loans during the half-year, funded by raising ₹12 crore in fresh borrowings. Total debt climbed to ₹187 crore. In a rising rate environment, that new debt is immediately more expensive.
A tougher funding climate ahead
The timing could not be worse. The broader NBFC sector is facing higher funding costs as the Reserve Bank of India tightens policy. An Economic Times report from November notes corporate bond yields rose sharply in October, making market borrowings more expensive. For a company like Meenakshi Steel, reliant on such funding, the margin pressure is direct and intense.
Live Chart
· MEENST
(BSE)
ISIN: INE721V01019
There is no relief in sight from other income, which turned negative this quarter. Nor from asset quality, which remains an opaque risk given the company's focus on corporate lending and equity investments. With cash reserves depleted to fund lending, as noted by ScanX, financial flexibility is narrowing.
Key Points
- Profit plummeted 81% year-on-year despite flat revenue, as interest expense surged 17%.
- Net profit margin collapsed to 2.4%, down nearly 1000 basis points from the year-ago quarter.
- The company funded significant new lending with fresh borrowings, increasing total debt amid a rising rate environment.
- Cash reserves fell sharply as capital was deployed into the loan book, reducing financial buffer.
Hexa Perspective
This quarter lays bare a fundamental vulnerability. Meenakshi Steel’s business model is acutely sensitive to the cost of debt, which is rising just as it takes on more. The 2.4% margin offers no cushion against further rate hikes or credit losses. For profitability to recover, the company must either earn significantly more on its new loans or find cheaper funding—both challenging in the current climate. Investors are left weighing whether the aggressive loan growth will eventually yield returns, or simply compound the cost problem.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.