Marksans Pharma (MARKSANS) Q2 FY27 Profit Dips 10% QoQ Despite Record Revenue
The drugmaker's sales crossed ₹900 crore for the first time, but a sequential profit decline highlights margin pressure from rising costs.
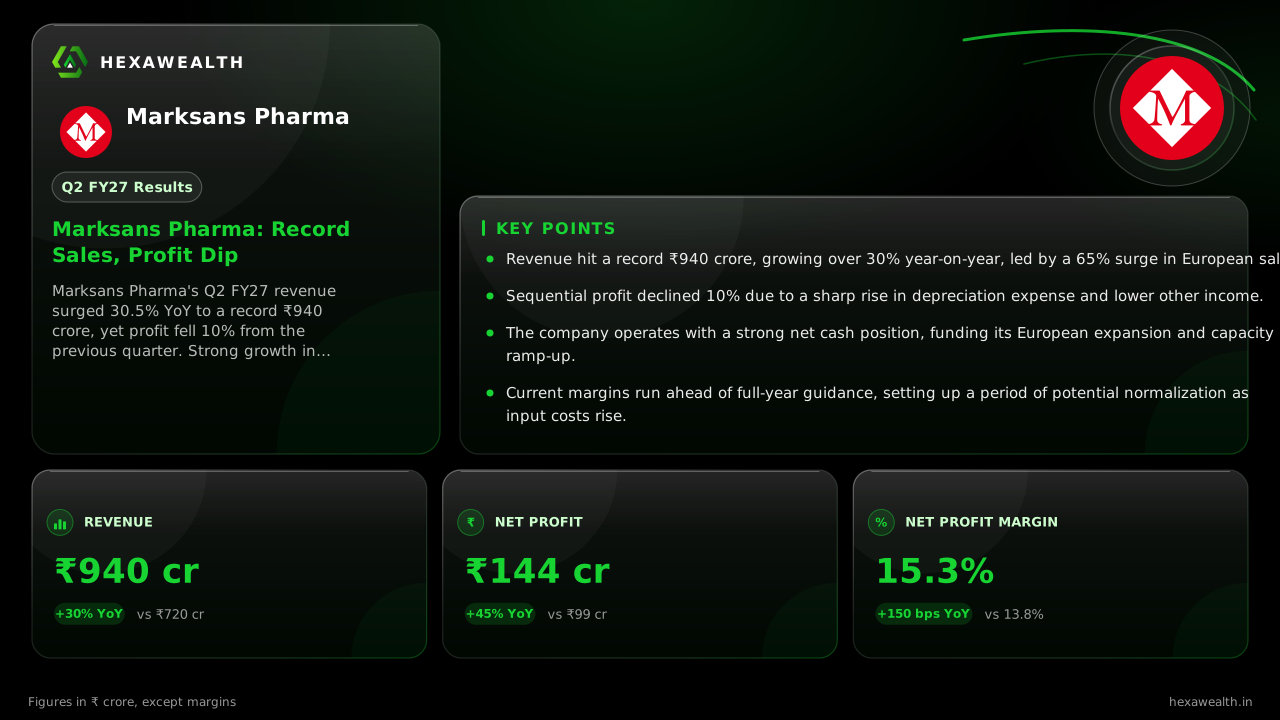
Marksans Pharma's Q2 FY27 revenue surged 30.5% YoY to a record ₹940 crore, yet profit fell 10% from the previous quarter. Strong growth in Europe and North America was offset by a sharp jump in depreciation and a drop in other income.
For Marksans Pharma, the story of the September quarter is one of powerful top-line momentum meeting a sudden cost squeeze. Revenue crossed the ₹900 crore milestone for the first time, driven by a surging European business, but profit slipped sequentially as the company absorbed the costs of its expansion.
The numbers show a clear split. Revenue grew 30.5% year-on-year and 11.8% from the June quarter to ₹940.2 crore. Profit, however, rose 44.8% over last year but fell 10% sequentially to ₹143.5 crore. The net profit margin compressed by 370 basis points from the previous quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 940.17 | 840.80 |
| Profit (₹ Cr) | 143.53 | 159.41 |
| Net Profit Margin (%) | 15.3 | 19.0 |
Where the growth came from
Europe was the standout performer, with revenue jumping 64.9% year-on-year to ₹405 crore, according to the company's investor presentation cited by Arthneeti. This was powered by organic expansion and contributions from the recently acquired QliniQ B.V. North America, the largest market, grew a more modest 8.7% to a record ₹421 crore.
The costs that bit into profit
Two items explain most of the quarter-on-quarter profit decline. First, depreciation surged 29.1% to ₹32.1 crore, a move the Arthneeti report links to recent capacity expansion. Second, other income fell 28.6% to ₹18.2 crore. Stockwatch.live notes the prior quarter's other income included a ₹12 crore net forex gain, a tailwind that did not repeat.
These were not one-off expenses but structural increases from growth investments. The company's EBITDA margin of 22.8%, reported by Sahi, remains well above its full-year guidance band of 20-21%.
The runway ahead
Management's focus is on scaling its newly built European front-end and utilizing its expanded 26-billion-unit annual capacity, now operating near 50%. The cash-rich balance sheet, with over ₹1,100 crore, provides fuel for both organic launches and more acquisitions like Germany's ABCnow GmbH.
The key watchpoint is margin normalization. Gross margin, still near 58.5%, is above the 55-56% level management has guided as sustainable for the year, per Stockwatch.live. As low-cost inventory depletes and raw material cost inflation works through, this compression is the next test for profitability.
Key Points
- Revenue hit a record ₹940 crore, growing over 30% year-on-year, led by a 65% surge in European sales.
- Sequential profit declined 10% due to a sharp rise in depreciation expense and lower other income.
- The company operates with a strong net cash position, funding its European expansion and capacity ramp-up.
- Current margins run ahead of full-year guidance, setting up a period of potential normalization as input costs rise.
Hexa Perspective
The quarter confirms Marksans Pharma's successful pivot to a direct, front-end model in Europe, which is delivering explosive growth. The sequential profit dip, however, underscores that this scaling is not free—it comes with upfront costs for depreciation and integration.
Investors are weighing a top line growing ahead of plan against a profitability peak that may have passed for this cycle. The stock's 57% one-year run already prices in strong execution. The next leg depends on whether European margins can hold as the business scales, and if US growth can re-accelerate to match the pace set overseas.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.