Lalithaa Jewellery (LALITHAA) Q1 FY27 Profit Drops 22% as Costs Outpace Revenue Growth
The jeweller's first results as a listed company show a 26% revenue surge, but profit fell sharply as material and finance costs rose faster than sales.
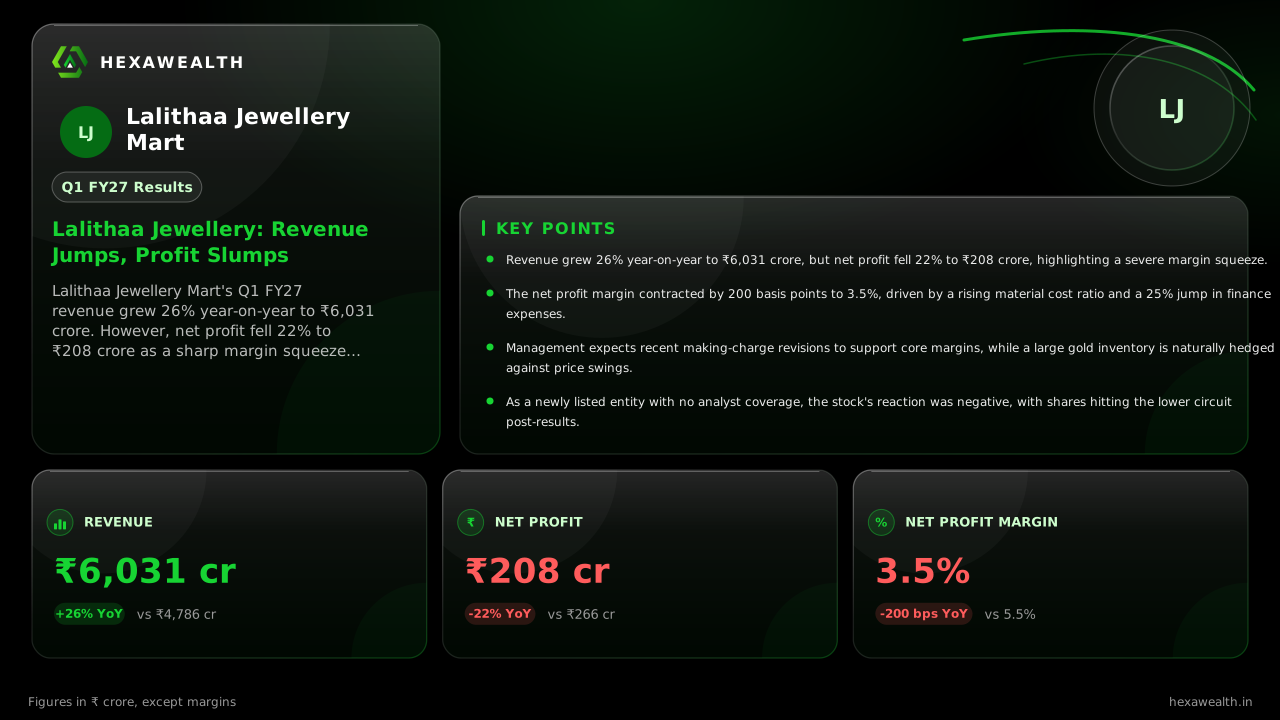
Lalithaa Jewellery Mart's Q1 FY27 revenue grew 26% year-on-year to ₹6,031 crore. However, net profit fell 22% to ₹208 crore as a sharp margin squeeze from higher costs overshadowed top-line strength.
For a newly listed jeweller, the first quarterly report sets the tone. Lalithaa Jewellery Mart's debut showed the market a business growing fast on paper, but struggling to convert that growth into earnings. Revenue climbed 26% from a year ago, yet profit fell by more than a fifth.
The scorecard reveals the tension. Net profit margin compressed by 200 basis points to 3.5%, a level well below the company's FY26 average of 4.0%. The sequential drop from a strong March quarter was even steeper, though that reflects typical seasonality after the wedding period.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q1 FY26 (Jun 2025): 4,786.11
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 6,501.82
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 6,031.23
- Profit (₹ Cr), Q1 FY26 (Jun 2025): 265.57
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 345.66
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 208.22
Revenue (₹ Cr)
- Revenue (₹ Cr), Q1 FY26 (Jun 2025): 4,786.11
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 6,501.82
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 6,031.23
Profit (₹ Cr)
- Profit (₹ Cr), Q1 FY26 (Jun 2025): 265.57
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 345.66
- Profit (₹ Cr), Q1 FY27 (Jun 2026): 208.22
Net Profit Margin (%)
- Net Profit Margin (%), Q1 FY26 (Jun 2025): 5.5
- Net Profit Margin (%), Q4 FY26 (Mar 2026): 5.3
- Net Profit Margin (%), Q1 FY27 (Jun 2026): 3.5
| Metric | CurrentQ1 FY27 (Jun 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 6,031.23 | 6,501.82 |
| Profit (₹ Cr) | 208.22 | 345.66 |
| Net Profit Margin (%) | 3.5 | 5.3 |
Why the growth didn't reach the bottom line
A cost-led profitability squeeze was the clear culprit. According to Stockwatch.live, the net material cost ratio rose to 90.8% of revenue from 87.0% a year ago. Finance costs also jumped 25% year-on-year. Together, these pushed total expenses up nearly 30%, far outpacing the 26% revenue gain.
The pressure was not from weak demand. Flash Finance notes 92% of revenue still comes from gold jewellery, with 62% sourced from Tier II and III cities. Growth was value-led, supported by store expansion. The issue was that stable gold prices during the quarter, as per CompoundingAI, caused a more than 90% year-on-year drop in inventory gains that had previously flattered margins.
A natural hedge and a management lever
Management highlighted a key balance sheet strength. The company's ₹10,407 crore gold inventory is substantially hedged by customer advances and supplier credit, limiting exposure to gold-price volatility. They also pointed to a 20 basis point improvement in the core gross margin from making charges.
Live Chart
· LALITHAA
(BSE)
ISIN: INE0K9O01026
Revisions to these making charges, implemented in late FY26 and early FY27, are expected to support underlying margins going forward. This is the primary lever management has guided for margin recovery, as noted in the company's post-results commentary.
The market's read on a new listing
With the stock having listed just in August, there were no formal analyst estimates to beat or miss. The market reaction, however, was telling. Following the results, shares hit a 5% lower circuit, as reported by Tradebrains. Investors judged the margin compression as a clear cost-led miss despite the top-line strength.
The lack of broker coverage means the stock's near-term trajectory will hinge on demonstrating that the making-charge revisions can durably improve profitability in the coming quarters, especially with gold prices remaining volatile.
Key Points
- Revenue grew 26% year-on-year to ₹6,031 crore, but net profit fell 22% to ₹208 crore, highlighting a severe margin squeeze.
- The net profit margin contracted by 200 basis points to 3.5%, driven by a rising material cost ratio and a 25% jump in finance expenses.
- Management expects recent making-charge revisions to support core margins, while a large gold inventory is naturally hedged against price swings.
- As a newly listed entity with no analyst coverage, the stock's reaction was negative, with shares hitting the lower circuit post-results.
Hexa Perspective
The quarter frames Lalithaa's central challenge: scaling a value-focused, gold-heavy business in a volatile cost environment. The 26% revenue growth confirms demand and distribution strength, particularly in smaller cities. Yet, the margin collapse shows how sensitive profits are when inventory gains vanish and funding costs rise.
The path forward depends on two factors. First, whether the making-charge revisions can lift the core margin enough to offset the absence of inventory gains. Second, how effectively the ₹1,200 crore IPO proceeds can reduce reliance on costlier debt. Until these show results, earnings will remain under pressure even if the top line keeps growing.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.