Kaarya Facilities (KAARYAFSL) Q2 FY27 Profit Edges Higher Despite Falling Revenue
The facility manager posted a modest profit gain as cost cuts offset a double-digit revenue decline, but a sharp rise in debt-funded interest expense squeezed margins.
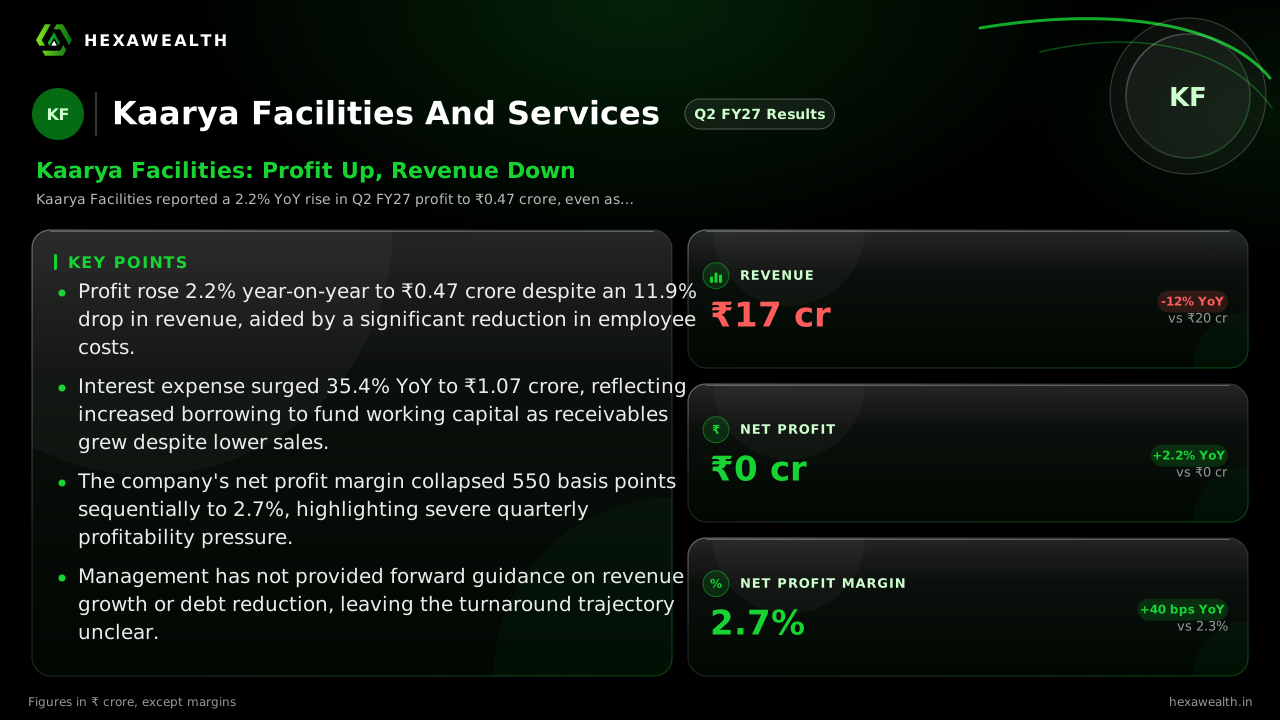
Kaarya Facilities reported a 2.2% YoY rise in Q2 FY27 profit to ₹0.47 crore, even as revenue fell 11.9%. Lower employee costs provided a buffer, but surging interest expense and weak collections pressured cash flow.
For a facility management company, steady service contracts are the lifeblood. Kaarya Facilities entered its second quarter with that foundation showing cracks, as revenue fell while the cost of funding its operations jumped sharply.
The September quarter saw revenue drop to ₹17.41 crore, down 11.9% from a year ago. Profit before tax, however, rose 28.3% to ₹0.59 crore. This apparent resilience came from a deep cut in the largest cost—employee expenses fell 13.8% year-on-year, according to a scanx.trade report.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 16.95
- Revenue (₹ Cr), Q4 FY25: 21.15
- Revenue (₹ Cr), Q2 FY26: 19.76
- Revenue (₹ Cr), Q4 FY26: 19.13
- Revenue (₹ Cr), Q2 FY27: 17.41
- Profit (₹ Cr), Q2 FY25: 0.48
- Profit (₹ Cr), Q4 FY25: 1.23
- Profit (₹ Cr), Q2 FY26: 0.46
- Profit (₹ Cr), Q4 FY26: 1.56
- Profit (₹ Cr), Q2 FY27: 0.47
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 16.95
- Revenue (₹ Cr), Q4 FY25: 21.15
- Revenue (₹ Cr), Q2 FY26: 19.76
- Revenue (₹ Cr), Q4 FY26: 19.13
- Revenue (₹ Cr), Q2 FY27: 17.41
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 0.48
- Profit (₹ Cr), Q4 FY25: 1.23
- Profit (₹ Cr), Q2 FY26: 0.46
- Profit (₹ Cr), Q4 FY26: 1.56
- Profit (₹ Cr), Q2 FY27: 0.47
Net Profit Margin
- Net Profit Margin, Q2 FY25: 2.8%
- Net Profit Margin, Q4 FY25: 5.8%
- Net Profit Margin, Q2 FY26: 2.3%
- Net Profit Margin, Q4 FY26: 8.2%
- Net Profit Margin, Q2 FY27: 2.7%
| Metric | CurrentQ2 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|
| Revenue (₹ Cr) | 17.41YoY -12% | 19.76 |
| Profit (₹ Cr) | 0.47YoY +2.2% | 0.46 |
| Net Profit Margin | 2.7%YoY +17% | 2.3% |
The cost cut that masked a cash crunch
Slashed payrolls kept the profit figure stable, but they tell only half the story. The other half is a 35.4% surge in interest costs, which hit ₹1.07 crore. This jump reflects a more troubling trend: the company is borrowing to cover a growing working capital gap.
Trade receivables rose even as sales fell, a divergence noted by multibagg.ai. This points to slower customer payments. To bridge this cash shortfall, Kaarya more than doubled its long-term borrowings in just six months, according to the same report.
A silent outlook in a noisy market
Management has provided no explicit strategy for growth or deleveraging, says a StockFin.ai analysis. This leaves investors with little to gauge the future beyond the immediate financials. The broader industry, however, is projected to grow at a 10.8% CAGR for outsourced services, per a UDS Group presentation.
Live Chart
· KAARYAFSL
(BSE)
ISIN: INE282Y01016
Kaarya's challenge is to capture that growth while fixing its balance sheet. With finance costs now consuming a larger share of a shrinking revenue pie, the margin for error is thin. The path to stability runs through better collections, not just more debt.
Key Points
- Profit rose 2.2% year-on-year to ₹0.47 crore despite an 11.9% drop in revenue, aided by a significant reduction in employee costs.
- Interest expense surged 35.4% YoY to ₹1.07 crore, reflecting increased borrowing to fund working capital as receivables grew despite lower sales.
- The company's net profit margin collapsed 550 basis points sequentially to 2.7%, highlighting severe quarterly profitability pressure.
- Management has not provided forward guidance on revenue growth or debt reduction, leaving the turnaround trajectory unclear.
Hexa Perspective
The quarter presents a paradox of accounting profit versus financial health. Kaarya managed to show a slight profit increase by cutting its largest operational cost. Yet, the underlying cash engine is sputtering.
Rising debt to fund receivables is a costly substitute for operational efficiency. Until collections improve and the company generates cash from its core services, the reported profit will remain vulnerable to the next interest rate hike or a further delay in payments. The story here is less about the profit line and more about the sustainability of the model that produced it.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.