Jujhar Logistics (JUJHARLOGI) Q2 FY27 Profit Jumps 4,221% on Logistics Pivot
The company's Q2 FY27 results show a complete transformation, with revenue surging past ₹49 crore as its new car-carrier business takes over from legacy chemicals.
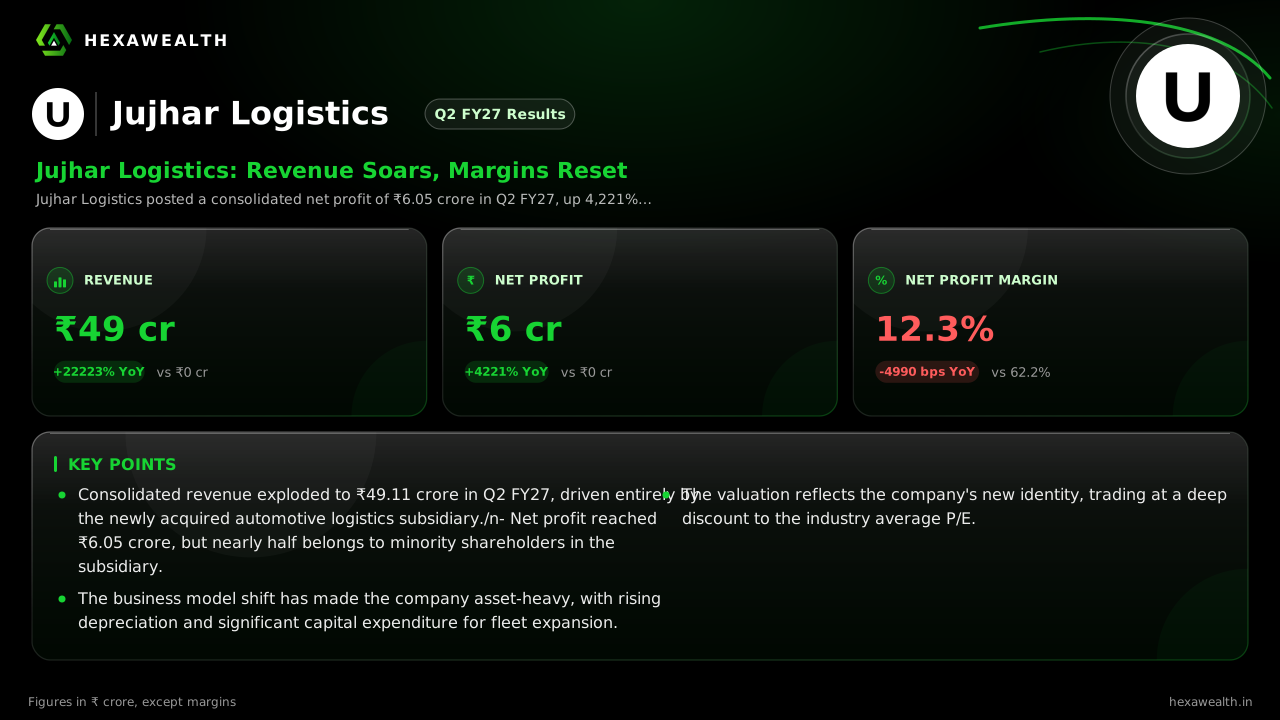
Jujhar Logistics posted a consolidated net profit of ₹6.05 crore in Q2 FY27, up 4,221% year-on-year. The explosive growth stems from its strategic pivot into automotive logistics following an acquisition last year.
Jujhar Logistics is no longer the chemicals trader it was a year ago. Its September quarter numbers tell the story of a complete business reinvention, where an acquisition has turned a near-dormant entity into a growing automotive logistics player.
The company reported a consolidated net profit of ₹6.05 crore for Q2 FY27, a staggering 4,221% leap from the ₹0.14 crore earned in the same quarter last year. Revenue soared to ₹49.11 crore from a mere ₹0.22 crore a year ago. Sequentially, both top and bottom lines grew healthily by 8% and 15.5%, respectively.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 0.22
- Revenue (₹ Cr), Q3 FY26: 22.18
- Revenue (₹ Cr), Q4 FY26: 52.22
- Revenue (₹ Cr), Q1 FY27: 45.49
- Revenue (₹ Cr), Q2 FY27: 49.11
- Profit (₹ Cr), Q2 FY26: 0.14
- Profit (₹ Cr), Q3 FY26: 2.74
- Profit (₹ Cr), Q4 FY26: 5.31
- Profit (₹ Cr), Q1 FY27: 5.24
- Profit (₹ Cr), Q2 FY27: 6.05
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 0.22
- Revenue (₹ Cr), Q3 FY26: 22.18
- Revenue (₹ Cr), Q4 FY26: 52.22
- Revenue (₹ Cr), Q1 FY27: 45.49
- Revenue (₹ Cr), Q2 FY27: 49.11
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 0.14
- Profit (₹ Cr), Q3 FY26: 2.74
- Profit (₹ Cr), Q4 FY26: 5.31
- Profit (₹ Cr), Q1 FY27: 5.24
- Profit (₹ Cr), Q2 FY27: 6.05
Net Profit Margin (%)
- Net Profit Margin (%), Q2 FY26: 62.2
- Net Profit Margin (%), Q3 FY26: 12.3
- Net Profit Margin (%), Q4 FY26: 10.2
- Net Profit Margin (%), Q1 FY27: 11.5
- Net Profit Margin (%), Q2 FY27: 12.3
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 49.11YoY +22223% | 45.49 | 0.22 |
| Profit (₹ Cr) | 6.05YoY +4221% | 5.24 | 0.14 |
| Net Profit Margin (%) | 12.3YoY -80% | 11.5 | 62.2 |
The acquisition driving the surge
This astronomical growth is not organic. According to reports from ScanX Trade and Alfafinder, it is due to the November 2025 acquisition of a 51% stake in Jujhar Logistic and Travels Limited, a car-carrier operator. The subsidiary, which serves major automakers, was consolidated into the results, transforming the revenue base. On a standalone basis, the parent company's revenue was just ₹2.32 crore this quarter.
The new logistics business is asset-heavy, which reshapes the cost profile. Depreciation rose 12% quarter-on-quarter, reflecting the capital-intensive fleet. While the net profit margin improved 80 basis points from Q1, it collapsed by 50 percentage points year-on-year. This is because the year-ago margin of 62% was on a tiny, nearly inactive revenue base, not a comparable business.
Funding an asset-heavy future
Cash flow from operations was robust at ₹27 crore for the half-year ended September, notes ScanX Trade. However, investing cash outflow was even larger at ₹31 crore, driven by purchases of fixed assets. This indicates the company is funding its fleet expansion, which aligns with a reported fivefold increase in borrowings over two years. The debt-to-equity ratio stands at a manageable 0.75.
Live Chart
· JUJHARLOGI
(BSE)
ISIN: INE198N01017
The market has taken note of the transformation. The stock traded at ₹204.45 on November 5, and while no major brokerages have published fresh ratings, the company now trades at a P/E of 9.8, a significant discount to the industry average of 41.5.
Key Points
- Consolidated revenue exploded to ₹49.11 crore in Q2 FY27, driven entirely by the newly acquired automotive logistics subsidiary./n- Net profit reached ₹6.05 crore, but nearly half belongs to minority shareholders in the subsidiary.
- The business model shift has made the company asset-heavy, with rising depreciation and significant capital expenditure for fleet expansion.
- The valuation reflects the company's new identity, trading at a deep discount to the industry average P/E.
Hexa Perspective
The quarter confirms Jujhar Logistics is now a logistics company, with its chemicals past effectively wound down. The growth trajectory is real but comes with the economics of its new industry—lower margins than the anomalous prior-year period and high capital intensity.
The key question is sustainability. Profit growth must now come from operational efficiency and scale within the logistics network, not just consolidation. With strong operating cash flow but heavy investment outflows, the balance between growth funding and financial leverage will be critical to watch in the coming quarters.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.