JSW Dulux (JSWDULUX) Q2 FY27 Profit Crashes 96% as Last Year's Windfall Vanishes
The paints maker's Q2 profit fell 96% year-on-year, a stark reversal from a one-time gain, while underlying margins were squeezed by raw material inflation.
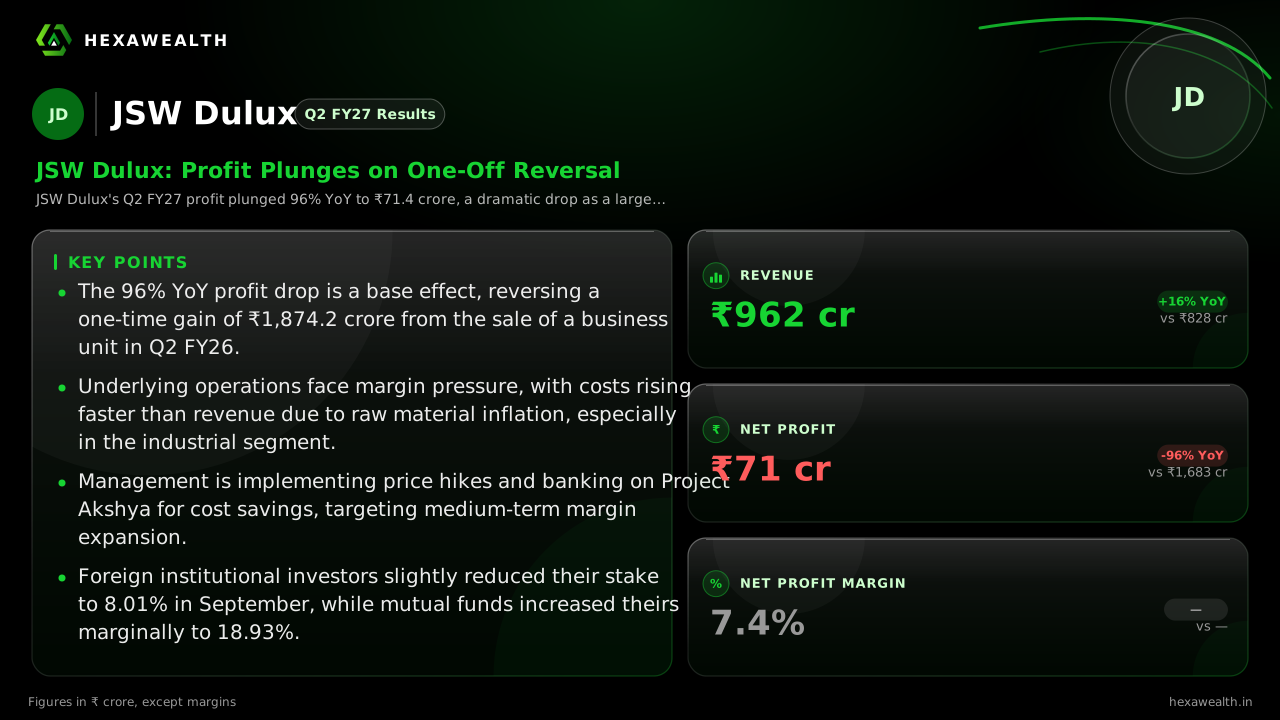
JSW Dulux's Q2 FY27 profit plunged 96% YoY to ₹71.4 crore, a dramatic drop as a large one-off gain from last year vanished. Revenue grew 16.2%, but margins faced pressure from elevated raw material costs.
For JSW Dulux, the September quarter was a story of two realities. The headline profit collapse is a mirage, a simple reversal of last year's extraordinary windfall. The real story is whether its underlying business can grow profitably amid industry-wide cost pressures.
Revenue grew 16.2% year-on-year to ₹961.9 crore, supported by a 21% volume surge. Yet, net profit plummeted 95.8% to ₹71.4 crore. This stark contrast is almost entirely due to the absence of a ₹1,874.2 crore pre-tax gain from selling its Powder Coatings business last year, as noted by The Economic Times.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 827.6
- Revenue (₹ Cr), Q3 FY26: 907.7
- Revenue (₹ Cr), Q4 FY26: 883.3
- Revenue (₹ Cr), Q1 FY27: 965.0
- Revenue (₹ Cr), Q2 FY27: 961.9
- Profit (₹ Cr), Q2 FY26: 1682.8
- Profit (₹ Cr), Q3 FY26: 74.3
- Profit (₹ Cr), Q4 FY26: 125.7
- Profit (₹ Cr), Q1 FY27: 79.7
- Profit (₹ Cr), Q2 FY27: 71.4
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 827.6
- Revenue (₹ Cr), Q3 FY26: 907.7
- Revenue (₹ Cr), Q4 FY26: 883.3
- Revenue (₹ Cr), Q1 FY27: 965.0
- Revenue (₹ Cr), Q2 FY27: 961.9
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 1682.8
- Profit (₹ Cr), Q3 FY26: 74.3
- Profit (₹ Cr), Q4 FY26: 125.7
- Profit (₹ Cr), Q1 FY27: 79.7
- Profit (₹ Cr), Q2 FY27: 71.4
Net Profit Margin
- Net Profit Margin, Q2 FY26: –
- Net Profit Margin, Q3 FY26: 8.2%
- Net Profit Margin, Q4 FY26: 14.2%
- Net Profit Margin, Q1 FY27: 8.3%
- Net Profit Margin, Q2 FY27: 7.4%
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 961.9YoY +16% | 965.0 | 827.6 |
| Profit (₹ Cr) | 71.4YoY -96% | 79.7 | 1682.8 |
| Net Profit Margin | 7.4% | 8.3% | – |
Even on a normalized basis, profitability is under strain. The company's net profit margin slipped 90 basis points from the June quarter. Total expenses rose 18.7% YoY, outpacing revenue growth.
The Squeeze Beneath the Surface
Raw material inflation is the primary culprit. Management, in the earnings call, cited elevated crude oil prices and a weaker rupee as key headwinds. To offset this, the company implemented an average price increase of 7.9% during the quarter, according to a Rediff Money report.
The pain was more acute in the industrial paints segment. Yahoo Finance reported that raw material costs there rose 30-35% while price hikes were only 6-7%, creating a significant profitability lag. This segment, which makes up 40-43% of sales, dilutes overall margins more than peers with a decorative-heavy mix.
Live Chart
· JSWDULUX
(BSE)
ISIN: INE133A01029
A Path to Better Margins?
Management is banking on Project Akshya to turn the tide. This integration initiative with JSW Paints aims to unlock supply chain synergies. The company has already realized ₹7.3 crore in savings this quarter and targets savings contributing 7-10% of full-year EBITDA.
The medium-term goal is to lift the EBITDA margin from around 13% toward 15%. However, CEO Rajiv Rajgopal cautioned on the concall that achieving the original 13-14% target for FY27 is challenging with crude oil above $105.
Key Points
- The 96% YoY profit drop is a base effect, reversing a one-time gain of ₹1,874.2 crore from the sale of a business unit in Q2 FY26.
- Underlying operations face margin pressure, with costs rising faster than revenue due to raw material inflation, especially in the industrial segment.
- Management is implementing price hikes and banking on Project Akshya for cost savings, targeting medium-term margin expansion.
- Foreign institutional investors slightly reduced their stake to 8.01% in September, while mutual funds increased theirs marginally to 18.93%.
Hexa Perspective
This quarter resets the baseline, stripping away last year's distortion to reveal a company in a competitive fight. The 21% volume growth is commendable, showing the Dulux brand retains pull. Yet, the margin compression is real and the central challenge.
The next few quarters hinge on a delicate balance: passing on enough price to protect margins without choking the volume growth that is its current strength. Project Akshya's promised savings must materialize to provide a buffer. Until margins show a clear, sustained recovery, the stock's deep discount to the industry PE will likely persist.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.