Jhandewalas Foods (JFL) Q2 FY26 Revenue Jumps 150% as Profit Margin Shrinks
The dairy and sweets maker posted a sharp top-line expansion in Q2 FY26, but a faster rise in costs pushed its net profit margin down to 4%.
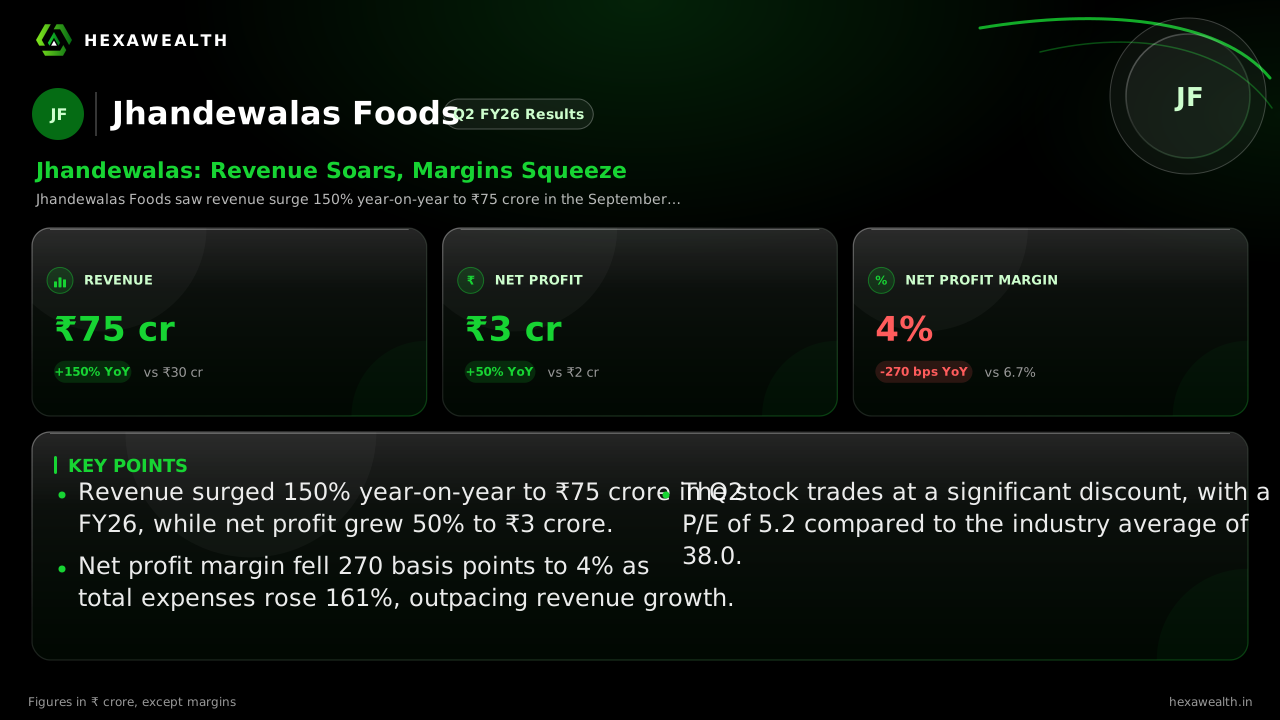
Jhandewalas Foods saw revenue surge 150% year-on-year to ₹75 crore in the September quarter. However, profit growth lagged at 50% as total expenses rose even faster, compressing the net profit margin.
For a traditional foods company, growth is a delicate balance between festive demand and the cost of milk. Jhandewalas Foods found the demand in Q2 FY26, but the costs proved harder to manage.
The quarter ended September 2025 saw revenue leap to ₹75 crore, a 150% increase from the same period last year. Net profit rose 50% to ₹3 crore. Yet, the net profit margin contracted by 270 basis points to just 4%, as total expenses surged 161%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY23: 8.0
- Revenue (₹ Cr), Q2 FY24: 10.0
- Revenue (₹ Cr), Q4 FY24: 16.0
- Revenue (₹ Cr), Q2 FY25: 30.0
- Revenue (₹ Cr), Q2 FY26: 75.0
- Profit (₹ Cr), Q4 FY23: 4.0
- Profit (₹ Cr), Q2 FY24: 0.0
- Profit (₹ Cr), Q4 FY24: 23.0
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 3.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY23: 8.0
- Revenue (₹ Cr), Q2 FY24: 10.0
- Revenue (₹ Cr), Q4 FY24: 16.0
- Revenue (₹ Cr), Q2 FY25: 30.0
- Revenue (₹ Cr), Q2 FY26: 75.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY23: 4.0
- Profit (₹ Cr), Q2 FY24: 0.0
- Profit (₹ Cr), Q4 FY24: 23.0
- Profit (₹ Cr), Q2 FY25: 2.0
- Profit (₹ Cr), Q2 FY26: 3.0
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY23: 50.0
- Net Profit Margin (%), Q2 FY24: 0.0
- Net Profit Margin (%), Q4 FY24: –
- Net Profit Margin (%), Q2 FY25: 6.7
- Net Profit Margin (%), Q2 FY26: 4.0
| Metric | CurrentQ2 FY26 | Same quarter LYQ2 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 75.0YoY +150% | 30.0 |
| Profit (₹ Cr) | 3.0YoY +50% | 2.0 |
| Net Profit Margin (%) | 4.0YoY -40% | 6.7 |
Why the profit didn't keep pace
A sharp rise in material costs was the primary driver behind the expense surge, according to a report by the Free Press Journal. This aligns with broader industry pressures, where raw milk and sugar prices have been escalating. The company's cost of goods sold expanded faster than its sales, eroding profitability.
The margin compression highlights a classic scale-up challenge. While revenue has grown dramatically from a low base, the business has not yet achieved operating leverage. Its trailing twelve-month net profit margin stands at 21.4%, showing how volatile quarterly profitability can be.
A valuation gap that reflects the risk
Investors have priced in this volatility and margin pressure. The stock trades at a P/E of 5.2, a steep 86% discount to the industry average of 38.0, as noted by Alfafinder.com. This gap underscores the market's skepticism about the sustainability of both growth and profits.
Live Chart
· JFL
(BSE)
ISIN: INE841Y01019
The discount may persist until the company demonstrates it can consistently convert top-line gains into bottom-line strength. For now, the valuation suggests the market sees more risk than reward in the current growth story.
Key Points
- Revenue surged 150% year-on-year to ₹75 crore in Q2 FY26, while net profit grew 50% to ₹3 crore.
- Net profit margin fell 270 basis points to 4% as total expenses rose 161%, outpacing revenue growth.
- The stock trades at a significant discount, with a P/E of 5.2 compared to the industry average of 38.0.
Hexa Perspective
The quarter presents a clear dichotomy: explosive sales growth met by even faster-rising costs. The core issue is whether this margin squeeze is a temporary side effect of rapid scaling or a structural challenge in a competitive, input-cost-sensitive industry.
The path to a re-rating is straightforward but difficult. Jhandewalas must prove it can hold or improve its 4% margin as it grows, turning revenue momentum into durable earnings power. Until then, the wide valuation gap against peers is likely to remain.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.