ISGEC Q2 FY27 Profit Rebounds 278% as Philippines Losses Narrow
ISGEC Heavy Engineering's Q2 profit surged from a weak base, but consolidated revenue dipped sequentially as project execution remained lumpy.
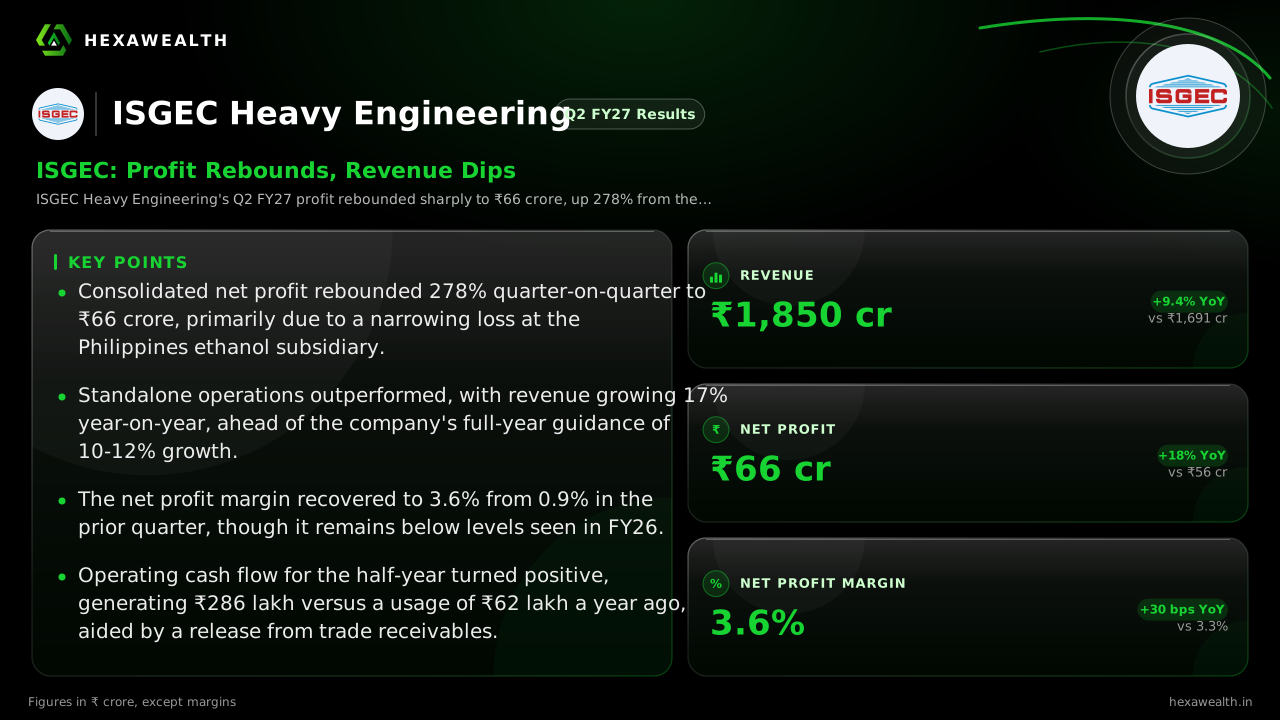
ISGEC Heavy Engineering's Q2 FY27 profit rebounded sharply to ₹66 crore, up 278% from the previous quarter. While standalone operations beat guidance, a narrowing loss at the Philippines ethanol plant drove the consolidated recovery.
For ISGEC Heavy Engineering, the story this quarter is a tale of two businesses. The core standalone operations are humming, but the group's earnings are still weighed down by a distant, loss-making asset. The September quarter shows progress on both fronts, with profitability rebounding sharply from a dismal June.
Consolidated revenue was ₹1,850 crore, up 9.4% from a year ago but down 6.5% from the previous quarter. Net profit, however, leapt to ₹66 crore, a 278% sequential jump. The net profit margin recovered to 3.6%, a 270 basis point improvement from Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin (%)
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,850.39YoY +9.4% | 1,980.00 | 1,691.09 |
| Profit (₹ Cr) | 66.19YoY +18% | 17.50 | 56.28 |
| Net Profit Margin (%) | 3.6YoY +9.1% | 0.9 | 3.3 |
A Strong Core Meets a Persistent Drag
The headline profit surge is largely a rebound from an exceptionally weak base. The prior quarter's profit of ₹17.5 crore was severely impacted by an ₹83 crore loss from the Philippines ethanol plant, as noted in the Q1 earnings call. This quarter, that segment loss narrowed to ₹60 crore, according to a Stockwatch report.
Meanwhile, the standalone business is performing ahead of plan. Management had guided for 10-12% revenue growth this fiscal year. Standalone revenue grew 17.2% year-on-year this quarter, comfortably beating that target, as per the same report. Both manufacturing and industrial projects segments hit their margin guidance bands.
The Outlook Hinges on Execution
The path forward depends on two separate tracks. The core business must maintain its execution momentum against a backdrop of lumpy project revenue. The company's ₹502 crore manufacturing capacity expansion, targeting ₹1,200 crore in annual revenue potential by FY29, is a key growth lever.
The bigger uncertainty remains the Philippines ethanol plant. While its losses are narrowing, it continues to be a significant drag. The company issued ₹61 crore in comfort letters for a joint venture this quarter, indicating ongoing financial support for group entities.
Key Points
- Consolidated net profit rebounded 278% quarter-on-quarter to ₹66 crore, primarily due to a narrowing loss at the Philippines ethanol subsidiary.
- Standalone operations outperformed, with revenue growing 17% year-on-year, ahead of the company's full-year guidance of 10-12% growth.
- The net profit margin recovered to 3.6% from 0.9% in the prior quarter, though it remains below levels seen in FY26.
- Operating cash flow for the half-year turned positive, generating ₹286 lakh versus a usage of ₹62 lakh a year ago, aided by a release from trade receivables.
Hexa Perspective
The quarter offers a clearer view of ISGEC's underlying strength, which had been obscured by subsidiary losses. The standalone business is tracking well, with margins on target and growth ahead of guidance. This provides a solid foundation.
Yet, the valuation at a 158% premium to the industry P/E suggests the market is pricing in a full turnaround. That requires the Philippines plant to move steadily toward breakeven and for the core business to sustain its outperformance. The next few quarters will test both assumptions, with project revenue volatility and subsidiary performance remaining key watchpoints.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.