Infonative Solutions (INFONATIVE) Q4 FY26 Profit Plunges 52% as Costs Overwhelm Revenue Growth
The IT services firm's annual revenue grew 6.2% but net profit collapsed due to a sharp surge in employee and interest expenses.
Infonative Solutions reported a 6.2% rise in FY26 revenue to ₹23.02 crore, but net profit fell 52% to ₹2.85 crore. The Q4 profit dropped 41.7% year-on-year as costs, particularly employee benefits, soared.
For a mid-tier IT services firm like Infonative Solutions, the story is often about managing costs to protect margins. The FY26 results show that story breaking down, with revenue growth overshadowed by a profit collapse.
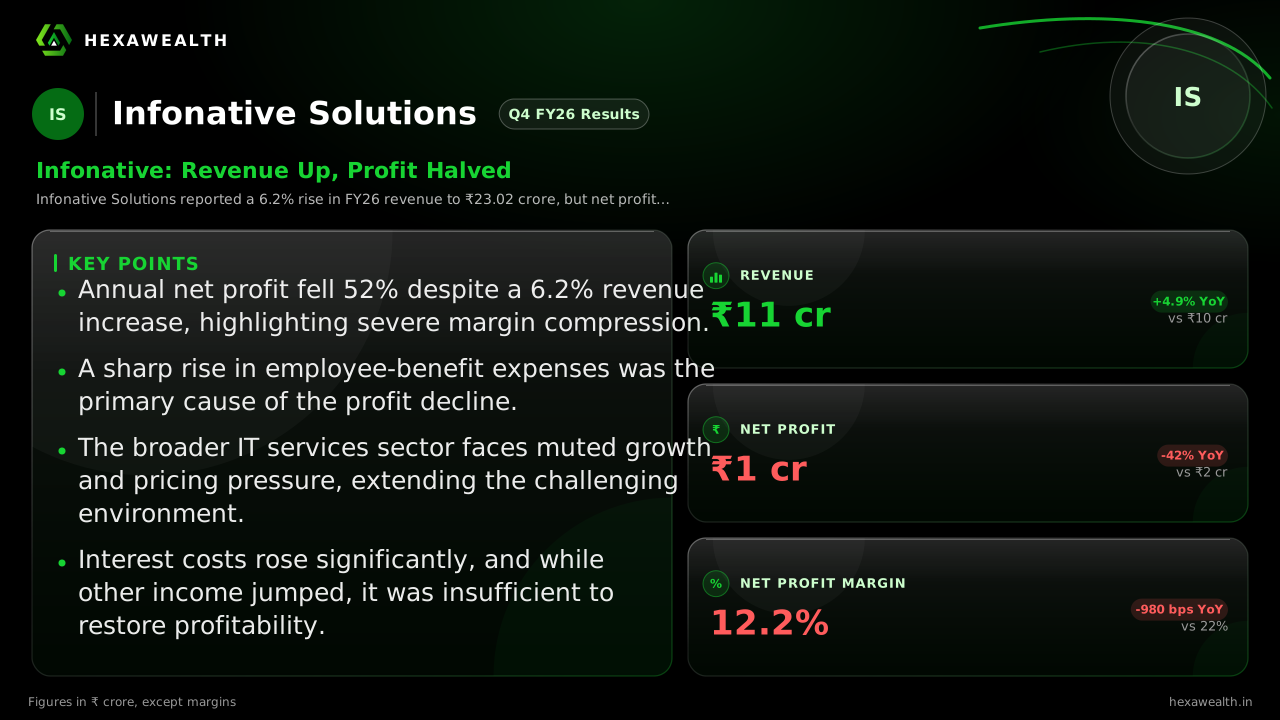
Annual revenue rose 6.2% to ₹23.02 crore, but net profit fell 52% to ₹2.85 crore. The March quarter saw a similar split: a 4.9% revenue gain to ₹10.95 crore, but a 41.7% drop in profit to ₹1.34 crore. The net profit margin, once at 22% a year ago, shrank to 12.2%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 7.17
- Revenue (₹ Cr), Q2 FY25: 11.23
- Revenue (₹ Cr), Q4 FY25: 10.44
- Revenue (₹ Cr), Q2 FY26: 12.07
- Revenue (₹ Cr), Q4 FY26: 10.95
- Profit (₹ Cr), Q4 FY24: 0.17
- Profit (₹ Cr), Q2 FY25: 3.64
- Profit (₹ Cr), Q4 FY25: 2.30
- Profit (₹ Cr), Q2 FY26: 1.52
- Profit (₹ Cr), Q4 FY26: 1.34
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 7.17
- Revenue (₹ Cr), Q2 FY25: 11.23
- Revenue (₹ Cr), Q4 FY25: 10.44
- Revenue (₹ Cr), Q2 FY26: 12.07
- Revenue (₹ Cr), Q4 FY26: 10.95
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 0.17
- Profit (₹ Cr), Q2 FY25: 3.64
- Profit (₹ Cr), Q4 FY25: 2.30
- Profit (₹ Cr), Q2 FY26: 1.52
- Profit (₹ Cr), Q4 FY26: 1.34
Net Profit Margin
- Net Profit Margin, Q4 FY24: 2.4%
- Net Profit Margin, Q2 FY25: 32.4%
- Net Profit Margin, Q4 FY25: 22.0%
- Net Profit Margin, Q2 FY26: 12.6%
- Net Profit Margin, Q4 FY26: 12.2%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 10.95YoY +4.9% | 10.44 |
| Profit (₹ Cr) | 1.34YoY -42% | 2.30 |
| Net Profit Margin | 12.2%YoY -45% | 22.0% |
The cost surge that erased profits
The primary driver was a 49.3% surge in total annual expenses, as reported by newboard.in. Employee-benefit expense was the largest disclosed cost movement, rising sharply according to multibagg.ai. This swamped the modest revenue increase.
Interest costs also jumped 70% year-on-year in Q4, reflecting higher borrowings. A 212% jump in other income provided some cushion but could not offset the core operating squeeze. The company's operating profit for the year fell 44.7%.
A muted outlook for the sector
The pressure is unlikely to ease soon. A Crisil Ratings report cited by ianslive.in suggests India's IT services sector growth will remain muted for two fiscals due to AI disruptions and weak spending. Clients are demanding price reductions of 20-30%, according to theweek.in.
Live Chart
· INFONATIVE
(BSE)
ISIN: INE12IB01015
For Infonative, this means the pricing and cost environment remains challenging. The company's strategy includes expanding AI-driven HRMS and LMS solutions, as outlined in its AGM, but near-term margin recovery looks difficult.
Key Points
- Annual net profit fell 52% despite a 6.2% revenue increase, highlighting severe margin compression.
- A sharp rise in employee-benefit expenses was the primary cause of the profit decline.
- The broader IT services sector faces muted growth and pricing pressure, extending the challenging environment.
- Interest costs rose significantly, and while other income jumped, it was insufficient to restore profitability.
Hexa Perspective
This quarter reveals a company caught between modest top-line growth and runaway costs. The near-50% expense jump is structural, not a one-off, suggesting a reset in its operating model is needed.
The valuation at a P/E of 11.2, a 72% discount to the industry, prices in this distress. Investors are weighing whether the new focus on AI solutions and the acquisition of Digital Benchers can stem the margin bleed before sector-wide headwinds intensify further.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.