All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 5 November 20262 min read

IMFA Q2 FY27 Profit Drops 23% QoQ as Expansion Costs Bite

The ferrochrome leader's net profit fell sequentially despite record production, as higher input costs and startup expenses squeezed margins.

By Abhinav Swaroop, CFA, Chief Business Officer: Hexawealth · Created 5 November 2026

IMFA's Q2 FY27 revenue grew 35% year-on-year to ₹968 crore, but profit fell 23% from the previous quarter. The drop highlights cost pressures from new capacity and rising input prices, even as production hit a record high.

For India’s largest ferrochrome producer, the September quarter was a story of two speeds. Record production from new furnaces pushed revenue sharply higher from a year ago, but the cost of that expansion arrived just as quickly, taking a direct bite out of quarterly profit.

Revenue for the quarter ended September 2026 was ₹968 crore, up 34.7% from the same period last year. Net profit stood at ₹148 crore, a 51.7% year-on-year jump. Sequentially, however, profit fell 23.2% from the June quarter, even as revenue was nearly flat. The net profit margin compressed by 480 basis points to 15.3%.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Net Profit Margin (%)

MetricCurrentQ2 FY27PreviousQ1 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr)
968.0YoY +35%
960.5
718.7
Profit (₹ Cr)
148.0YoY +52%
192.6
97.6
Net Profit Margin (%)
15.3YoY +13%
20.1
13.6

The Cost of Scaling Up

The sequential profit drop was driven by a sharp rise in expenses. Total costs increased 8.2% quarter-on-quarter. According to the company's investor presentation, cited by Investing.com, the cost per tonne of ferrochrome produced rose nearly 3%.

Management attributed this to higher metallurgical coke prices, greater reliance on costlier underground mining, and startup expenses at its new greenfield site. An ₹8 crore foreign exchange mark-to-market loss from rupee depreciation also played a role.

A Volume-Led Outlook

Despite the margin squeeze, the underlying volume story remains strong. Ferrochrome production hit a record 86,652 tonnes, up 32% year-on-year, as reported by Business Standard. Management expects output to cross 100,000 tonnes next quarter for the first time.

In an earnings call, Managing Director Subhrakant Panda said any near-term margin contraction would be “more than made up with volumes.” The company maintains its full-year production guidance of 380,000 tonnes.

Key Points

  • IMFA's Q2 profit fell 23% sequentially despite flat revenue, as costs rose 8.2%.
  • Higher input prices and startup expenses at new capacity drove a 480 bps drop in net profit margin.
  • Record quarterly production of 86,652 tonnes supports a volume-led growth outlook for the second half.
  • Management expects Q3 output to exceed 100,000 tonnes, aiming to offset margin pressure with higher sales.

Hexa Perspective

The quarter reveals the transition from a high-margin peak to a volume-driven growth phase. The 20%+ net margin of Q1 was likely an outlier, flattered by strong pricing and lower initial costs. Now, the business is normalizing as it absorbs the expenses of its aggressive expansion.

The critical question is whether the promised volume surge in Q3 and Q4 can fully offset the twin pressures of rising input costs and moderating selling prices. The company's integrated model provides a cost buffer, but the next few quarters will test its ability to deliver on volume targets while preserving profitability.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
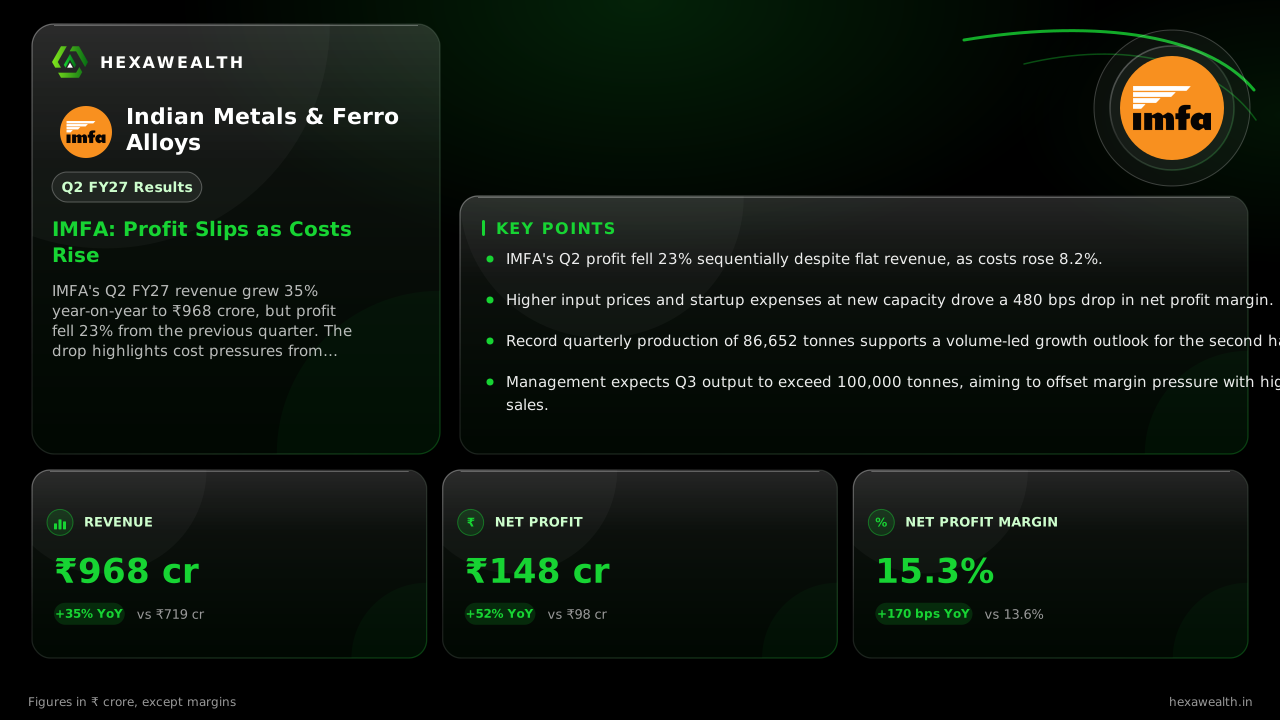
Indian Metals & Ferro Alloys (IMFA) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Indian Metals & Ferro Alloys' Q2 FY27 results?
Indian Metals & Ferro Alloys reported Q2 FY27 revenue of ₹968 crore, a 34.7% increase year-on-year. Net profit was ₹148 crore, up 51.7% from the same quarter last year, but down 23.2% from the previous quarter due to rising costs.
Why did IMFA's Q2 FY27 profit drop 23% sequentially?
IMFA's Q2 profit fell 23% quarter-on-quarter primarily due to higher costs. According to the company's investor presentation, this included increased prices for metallurgical coke, costlier underground mining, and startup expenses at its new greenfield project.
What was IMFA's net profit margin in Q2 FY27?
IMFA's net profit margin was 15.3% in Q2 FY27. This marked a 480 basis point decline from the previous quarter's 20.1% margin, reflecting the significant cost pressures the company faced during the period.
How much ferrochrome did IMFA produce in Q2 FY27?
IMFA achieved a record quarterly ferrochrome production of 86,652 tonnes in Q2 FY27, as reported by Business Standard. This was a 32% increase from the 65,671 tonnes produced in the same quarter the previous year.
What is IMFA's production guidance for FY27?
IMFA's management has maintained its production guidance of 380,000 tonnes of ferrochrome for FY27. They expect output to cross 100,000 tonnes in the third quarter for the first time, relying on volume growth to offset margin pressure.
What caused the 480 bps sequential drop in net profit margin for IMFA?
The 480 basis point drop in IMFA's Q2 net margin was driven by a rise in per-tonne production costs. Management, cited by Investing.com, attributed this to higher metallurgical coke prices, increased use of underground mining, and startup costs for new furnaces.
Did lower other income contribute to IMFA's Q2 profit drop?
Yes, lower other income was a contributing factor. Other income fell 61.3% sequentially to ₹5 crore in Q2 FY27, down from ₹12.9 crore in Q1. This reduction added to the pressure on the bottom line from higher operational costs.
Why did IMFA's total expenses rise 8.2% quarter-on-quarter?
IMFA's total expenses rose 8.2% QoQ due to several cost pressures. The company's presentation noted higher metallurgical coke prices, greater reliance on underground mining, startup expenses for new facilities, and an ₹8 crore forex impact.
What drove the significant YoY increase in interest and depreciation costs?
The year-on-year surge in interest (up 73%) and depreciation (up 78%) costs is linked to IMFA's major capacity expansion. Financing and capitalizing assets for new projects like the Kalinganagar greenfield site have increased these fixed charges.
What guidance did IMFA management provide for ferrochrome margins?
Management acknowledged that margins might tighten slightly in the near term due to rising input costs and moderating prices. However, they expect volume growth in the coming quarters to more than offset this pressure on absolute profitability.
How did IMFA's stock price react to the Q2 FY27 results?
Following the results announcement, IMFA's stock rose 2.97% to ₹1,132, as reported by Investing.com. The market reaction was modestly positive, focusing on record production and volume guidance despite the sequential profit decline.
IMFA Q2 profit drop
IMFA's Q2 FY27 net profit was ₹148 crore, a 23.2% drop from the ₹192.6 crore profit in Q1 FY27. The decline was driven by an 8.2% rise in total expenses, including higher input costs and startup expenses for new capacity.
IMFA Q2 FY27 results order book
While a specific order book figure was not detailed in the Q2 results, IMFA's management highlighted strong volume guidance. They expect to sell the increased output, with exports constituting about 84% of revenue and domestic demand from stainless steel makers rising.