IDFC Q1 FY25 Profit Plunges 68% as Merger and Provisions Bite
IDFC's Q1 FY25 profit fell sharply year-on-year as the company navigates its reverse merger with IDFC First Bank and faces higher credit costs.
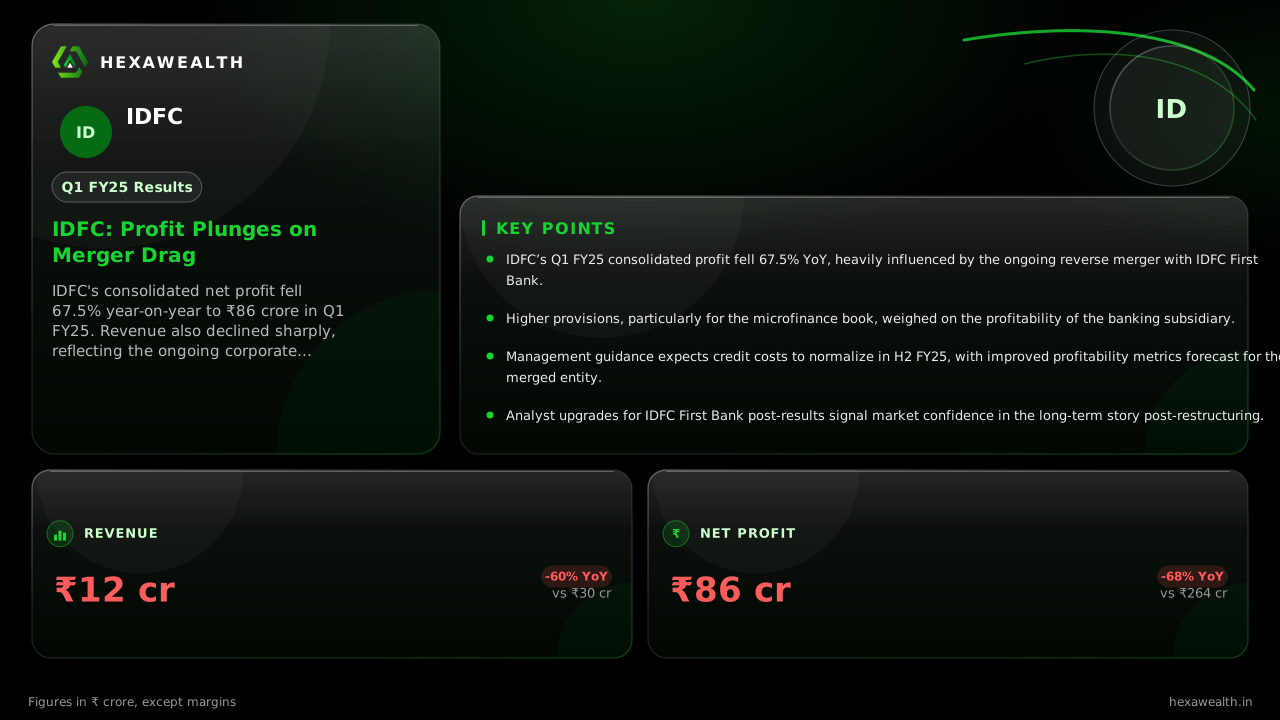
IDFC's consolidated net profit fell 67.5% year-on-year to ₹86 crore in Q1 FY25. Revenue also declined sharply, reflecting the ongoing corporate restructuring and stress in its microfinance portfolio.
IDFC’s first-quarter numbers are a snapshot of a company in transition. The reported figures, a sharp drop from last year, reflect the final stages of its reverse merger with IDFC First Bank and the financial toll of cleaning up its books.
The scorecard shows a steep decline. Consolidated net profit fell 67.5% from a year ago to ₹85.8 crore. Revenue dropped 60.2% to ₹11.9 crore. Sequentially, profit plunged 75% despite a 22% rise in revenue, underscoring the quarter's volatility.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q1 FY24: 29.91
- Revenue (₹ Cr), Q2 FY24: 36.67
- Revenue (₹ Cr), Q3 FY24: -7.65
- Revenue (₹ Cr), Q4 FY24: 9.77
- Revenue (₹ Cr), Q1 FY25: 11.89
- Profit (₹ Cr), Q1 FY24: 264.15
- Profit (₹ Cr), Q2 FY24: 223.54
- Profit (₹ Cr), Q3 FY24: 210.04
- Profit (₹ Cr), Q4 FY24: 347.85
- Profit (₹ Cr), Q1 FY25: 85.82
Revenue (₹ Cr)
- Revenue (₹ Cr), Q1 FY24: 29.91
- Revenue (₹ Cr), Q2 FY24: 36.67
- Revenue (₹ Cr), Q3 FY24: -7.65
- Revenue (₹ Cr), Q4 FY24: 9.77
- Revenue (₹ Cr), Q1 FY25: 11.89
Profit (₹ Cr)
- Profit (₹ Cr), Q1 FY24: 264.15
- Profit (₹ Cr), Q2 FY24: 223.54
- Profit (₹ Cr), Q3 FY24: 210.04
- Profit (₹ Cr), Q4 FY24: 347.85
- Profit (₹ Cr), Q1 FY25: 85.82
| Metric | CurrentQ1 FY25 | PreviousQ4 FY24 | Same quarter LYQ1 FY24 |
|---|---|---|---|
| Revenue (₹ Cr) | 11.89YoY -60% | 9.77 | 29.91 |
| Profit (₹ Cr) | 85.82YoY -68% | 347.85 | 264.15 |
The Merger Clears the Decks
The dramatic fall is largely structural. IDFC is executing a reverse merger, folding itself into IDFC First Bank. According to a StockScans report, this amalgamation, effective October 2024, will use tax benefits to set off legacy losses and simplify the corporate structure. The current quarter's financials bear the weight of this final clean-up.
Simultaneously, the underlying bank faced operational headwinds. The Economic Times reported that IDFC First Bank’s profit was pressured by a 109% year-on-year rise in provisions to ₹994 crore. This was primarily due to stress in the joint liability group (JLG) or microfinance portfolio, impacted by floods in Tamil Nadu.
A Path to Normalisation
Management expects this pain to be temporary. Guidance cited by Quartr indicates credit costs should normalize from the second half of FY25. The bank is also projecting its return on assets (RoA) to reach 1.2% by FY26 as profitability recovers post-merger.
Live Chart
· IDFC
(BSE)
ISIN: INE043D01016
The market reaction has been mixed, focusing on the future bank entity. After the results, brokerages like CLSA and Nomura upgraded IDFC First Bank, with CNBC TV18 reporting price target hikes, reflecting optimism for the post-merger earnings trajectory.
Key Points
- IDFC’s Q1 FY25 consolidated profit fell 67.5% YoY, heavily influenced by the ongoing reverse merger with IDFC First Bank.
- Higher provisions, particularly for the microfinance book, weighed on the profitability of the banking subsidiary.
- Management guidance expects credit costs to normalize in H2 FY25, with improved profitability metrics forecast for the merged entity.
- Analyst upgrades for IDFC First Bank post-results signal market confidence in the long-term story post-restructuring.
Hexa Perspective
The quarter underscores IDFC’s role as a holding company in its final act. The plunging consolidated numbers are less an indicator of operational failure and more a ledger of restructuring costs and one-time provisions. The investment case now hinges entirely on the success of IDFC First Bank.
For that, two things need to hold. First, the guidance on cooling credit costs must materialize in the coming quarters. Second, the merged entity must deliver on the promised operational efficiencies and growth to justify recent analyst upgrades. The transition is nearly complete, shifting the focus squarely to execution.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.