Icodex Publishing (ICODEX) Q4 FY26 Profit Plunges 66% as Expenses Double
Icodex Publishing's Q4 FY26 profit fell 66% year-on-year despite higher revenue, as a sharp rise in employee costs and other expenses crushed margins.
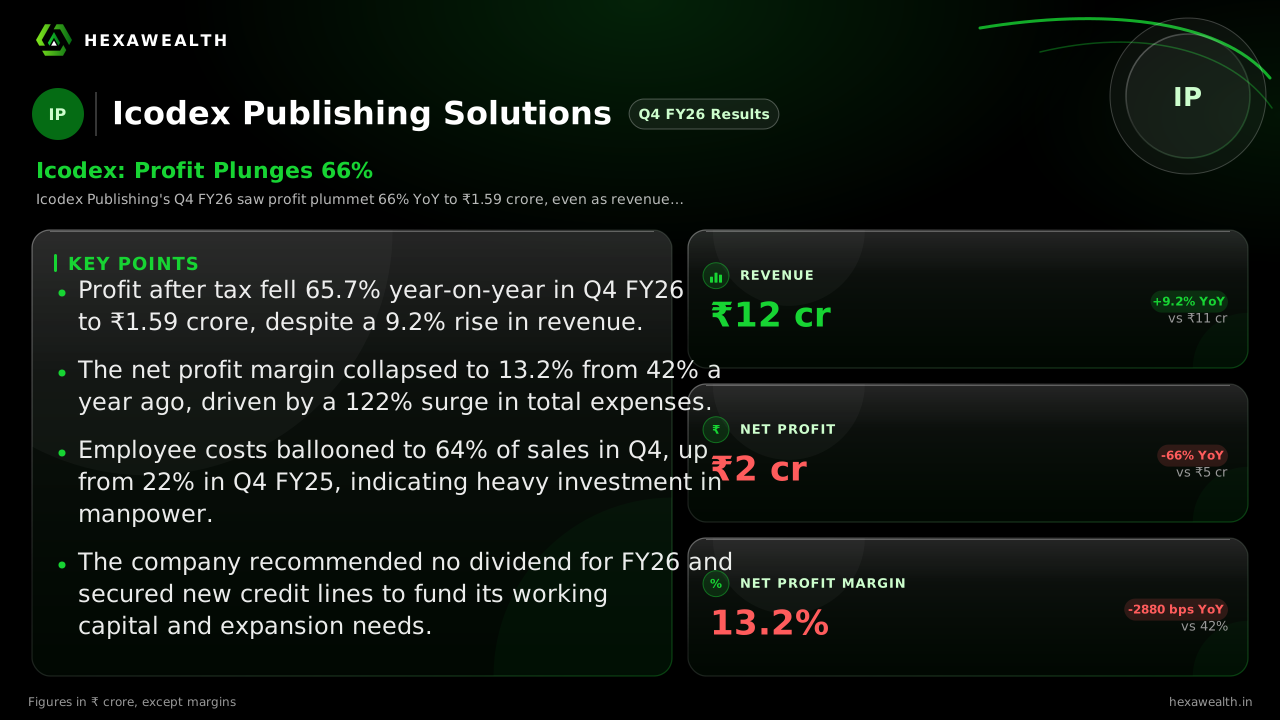
Icodex Publishing's Q4 FY26 saw profit plummet 66% YoY to ₹1.59 crore, even as revenue grew 9%. The collapse was driven by a 122% surge in total expenses, primarily employee costs, which slashed the net profit margin to 13.2%.
For Icodex Publishing, a strong top line has historically delivered robust profits. The March quarter broke that link, as higher sales were overwhelmed by a surge in costs, leaving investors to question the sustainability of its growth model.
Revenue for Q4 FY26 was ₹12.04 crore, up 9.2% from a year ago. Profit, however, collapsed 65.7% to ₹1.59 crore. The net profit margin fell to 13.2%, down from 42% in Q4 FY25. The full year told a similar story: revenue grew 18.5% to ₹25.93 crore, but profit fell 20.8% to ₹7.09 crore.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 10.84
- Revenue (₹ Cr), Q4 FY25: 11.03
- Revenue (₹ Cr), Q2 FY26: 13.89
- Revenue (₹ Cr), Q4 FY26: 12.04
- Profit (₹ Cr), Q2 FY25: 4.33
- Profit (₹ Cr), Q4 FY25: 4.63
- Profit (₹ Cr), Q2 FY26: 5.50
- Profit (₹ Cr), Q4 FY26: 1.59
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY25: 10.84
- Revenue (₹ Cr), Q4 FY25: 11.03
- Revenue (₹ Cr), Q2 FY26: 13.89
- Revenue (₹ Cr), Q4 FY26: 12.04
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY25: 4.33
- Profit (₹ Cr), Q4 FY25: 4.63
- Profit (₹ Cr), Q2 FY26: 5.50
- Profit (₹ Cr), Q4 FY26: 1.59
Net Profit Margin
- Net Profit Margin, Q2 FY25: 39.9%
- Net Profit Margin, Q4 FY25: 42.0%
- Net Profit Margin, Q2 FY26: 39.6%
- Net Profit Margin, Q4 FY26: 13.2%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 12.04YoY +9.2% | 11.03 |
| Profit (₹ Cr) | 1.59YoY -66% | 4.63 |
| Net Profit Margin | 13.2%YoY -69% | 42.0% |
The Employee Cost Surge
The margin collapse was driven by a 122% year-on-year jump in total expenses to ₹9.67 crore. Data from newboard.in shows employee costs as a percentage of sales soared to 64% in Q4 FY26, up from 22% a year earlier. This suggests significant investments in hiring or higher payouts, which drastically eroded operating profitability.
A One-Off Income Cushion
The profit figure would have been worse without a ₹0.54 crore boost from other income, a 315% jump from the previous quarter. This cushioned the bottom line but did not offset the core operating pressure. The company also faced higher interest costs and an elevated tax rate of 45.4%, as noted by Cruxal.
Funding Growth, Forgoing Dividends
With profitability under pressure, the company is conserving cash for expansion. The board recommended no dividend for FY26, citing future business plans. It also secured ₹10.80 crore in credit facilities from ICICI Bank in April 2026 for working capital and capex, as reported by ScanX.
Live Chart
· ICODEX
(BSE)
ISIN: INE111601014
Key Points
- Profit after tax fell 65.7% year-on-year in Q4 FY26 to ₹1.59 crore, despite a 9.2% rise in revenue.
- The net profit margin collapsed to 13.2% from 42% a year ago, driven by a 122% surge in total expenses.
- Employee costs ballooned to 64% of sales in Q4, up from 22% in Q4 FY25, indicating heavy investment in manpower.
- The company recommended no dividend for FY26 and secured new credit lines to fund its working capital and expansion needs.
Hexa Perspective
The quarter reveals a company in transition, sacrificing near-term margins to build capacity. The valuation, at a P/E of 8.3 against an industry average of 20.4, prices in this uncertainty. The critical question is whether these elevated costs are a one-time investment phase or a new, less profitable normal. For the stock to re-rate, Icodex must demonstrate that its revenue growth can outpace this new cost structure and restore its once-strong margins.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.