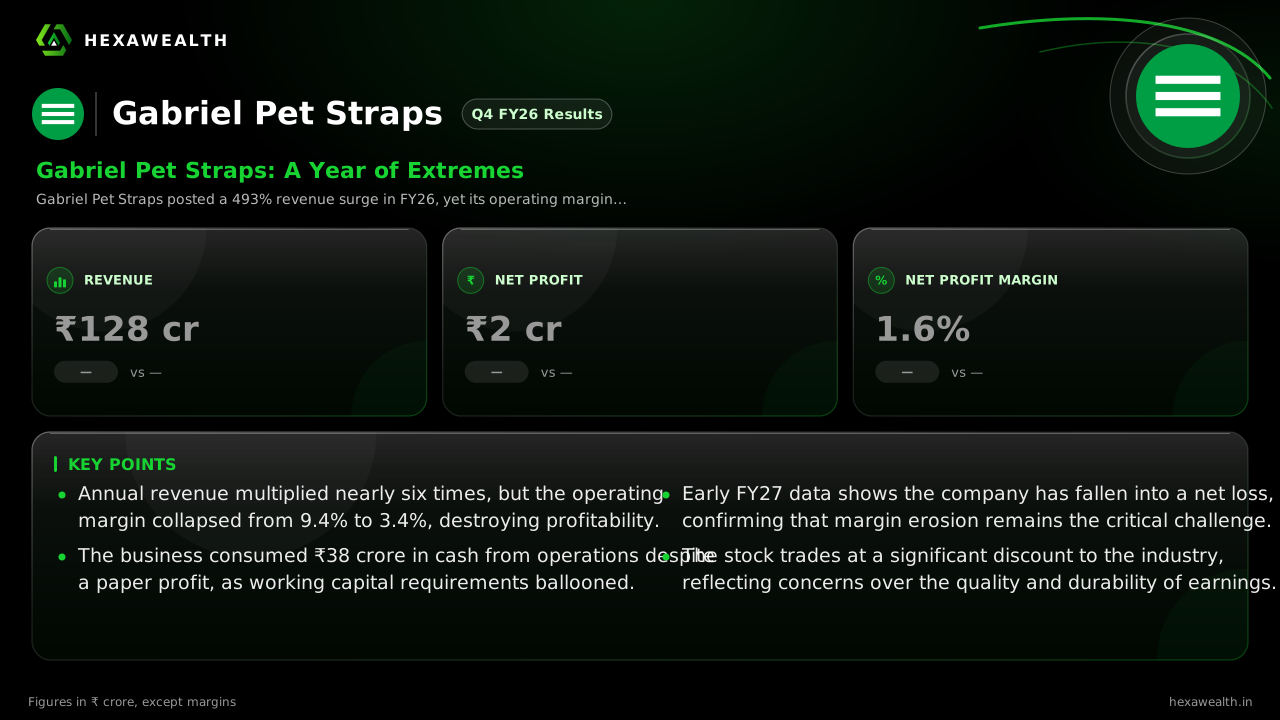
Gabriel Pet Straps (GPSL) Q4 FY26 Revenue Jumps 493% as Profitability Crumbles
The packaging firm's FY26 sales skyrocketed on massive volume, but a severe margin squeeze and negative cash flow reveal the cost of that growth.
Gabriel Pet Straps posted a 493% revenue surge in FY26, yet its operating margin collapsed to 2.4%. The final quarter saw a dramatic slowdown, with profit down 91% sequentially.
For a manufacturer of PET straps, a year of explosive growth should be a clear win. Gabriel Pet Straps' FY26 tells a more complex story, where a 493% revenue surge came at the steep price of collapsing profitability.
The numbers paint a year of extremes. Annual revenue vaulted to ₹182.85 crore from just ₹30.84 crore a year ago. Yet the operating margin nearly vanished, falling to 3.4% from 9.4%, as per the company's statements. The fourth quarter revealed a sharp deceleration, with revenue dropping 77% and profit plunging 91% from the September quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 546.0
- Revenue (₹ Cr), Q4 FY26: 128.0
- Profit (₹ Cr), Q2 FY26: 22.0
- Profit (₹ Cr), Q4 FY26: 2.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26: 546.0
- Revenue (₹ Cr), Q4 FY26: 128.0
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26: 22.0
- Profit (₹ Cr), Q4 FY26: 2.0
Net Profit Margin
- Net Profit Margin, Q2 FY26: 4.0%
- Net Profit Margin, Q4 FY26: 1.6%
| Metric | CurrentQ4 FY26 |
|---|---|
| Revenue (₹ Cr) | 128.0 |
| Profit (₹ Cr) | 2.0 |
| Net Profit Margin | 1.6% |
The Cost of Scaling Up
The staggering revenue jump was volume-led, but expenses grew even faster. Total expenses for the year ballooned by 536%, far outpacing the top-line growth. This suggests the company may have chased sales with aggressive pricing or faced higher input costs, eroding the profit from each rupee earned.
Data from Newboard.in shows the operating margin for the full year slumped to 2.4%, a fraction of the 9.0% recorded in FY25. The margin compression was severe in the second half, with the H2 FY26 operating margin at just 1.2%.
A Cash Flow Conundrum
Despite reporting a profit, the business burned cash. Cash flow from operations was deeply negative at ₹38.28 crore for FY26. This disconnect, highlighted by Moneycontrol, typically points to a buildup in working capital—money tied up in inventory and unpaid customer invoices.
Live Chart
· GPSL
(BSE)
ISIN: INE0QZF01012
The annual statements confirm a ₹42.68 crore increase in working capital. The company funded this growth and a ₹26.19 crore investment outflow largely through financing activities, raising nearly ₹60 crore.
What Comes After the Surge?
The outlook is clouded by the immediate aftermath. For H1 FY27, Alfafinder.com reports the company swung to a net loss of ₹7.8 crore despite revenue rising 181% year-on-year. This indicates the margin pressures that defined FY26 have intensified, not eased.
With no institutional analyst coverage noted for this SME stock, the market's read is reflected in valuation. The stock trades at a P/E of 13.4, a 64% discount to its industry peers, signaling deep skepticism about the sustainability of its earnings.
Key Points
- Annual revenue multiplied nearly six times, but the operating margin collapsed from 9.4% to 3.4%, destroying profitability.
- The business consumed ₹38 crore in cash from operations despite a paper profit, as working capital requirements ballooned.
- Early FY27 data shows the company has fallen into a net loss, confirming that margin erosion remains the critical challenge.
- The stock trades at a significant discount to the industry, reflecting concerns over the quality and durability of earnings.
Hexa Perspective
The FY26 report is a classic case of growth without grace. The revenue line tells a story of remarkable commercial execution, likely capitalizing on demand for recycled PET strapping. The profit and cash flow statements, however, reveal a business struggling with the economics of that scale.
The path forward hinges on whether this was a necessary investment phase to secure market share or a sign of a structurally low-margin operation. The steep sequential drop in Q4 and the loss in H1 FY27 lean toward the latter. Investors are right to price in a high degree of uncertainty until the company demonstrates it can convert its top-line momentum into sustainable cash earnings.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.