EPL Q2 FY27's Record Revenue Growth Masks a Profitability Squeeze
EPL posted its fastest-ever quarterly revenue growth of 30%, but profit rose just 4.6% as higher costs and European challenges bit into margins.
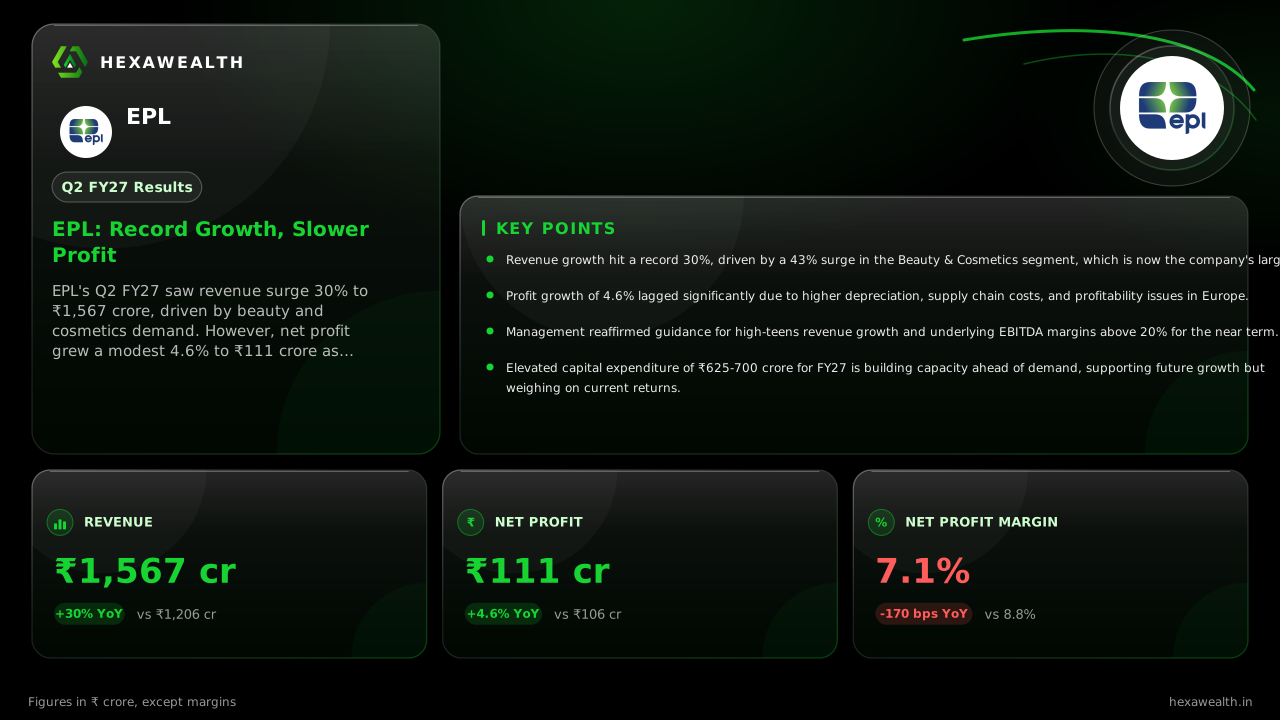
EPL's Q2 FY27 saw revenue surge 30% to ₹1,567 crore, driven by beauty and cosmetics demand. However, net profit grew a modest 4.6% to ₹111 crore as margins contracted, highlighting the cost of rapid expansion.
For a global packaging leader like EPL, the test is converting market share gains into earnings power. The September quarter delivered a record top-line sprint but left profitability trailing, revealing the cost of running ahead of demand.
Revenue surged 29.9% year-on-year to ₹1,567 crore, the company's fastest-ever pace. Profit after tax grew a more modest 4.6% to ₹111 crore. The net profit margin compressed 170 basis points to 7.1%, as expenses grew faster than sales.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 1,567.0YoY +30% | 1,387.9 | 1,205.9 |
| Profit (₹ Cr) | 111.0YoY +4.6% | 100.6 | 106.1 |
| Net Profit Margin | 7.1%YoY -19% | 7.2% | 8.8% |
Where the Growth Came From
The 30% revenue jump, as per the company's investor presentation, was led by a 42.9% surge in the Beauty & Cosmetics segment. For the first time, this category overtook Oral Care to become EPL's largest. Management told Investing.com that underlying growth, excluding commodity price pass-throughs, was a still-strong 20.3%, showing genuine volume and share gains.
Growth was broad-based geographically, with East Asia Pacific leading at over 40%. The company said it added more than 80 new customers in Beauty & Cosmetics, a sign its capacity investments are paying off.
The Costs That Ate the Profit
Total expenses rose 32.3% YoY, outpacing revenue. The Investing.com transcript notes the company incurred higher freight and inventory costs to ensure superior customer service during supply chain disruptions. More structurally, depreciation jumped 19.7% due to what management called "ahead-of-the-curve" capacity investments.
Europe was a specific pain point. While revenue there grew 30.4%, regulatory delays at a Poland facility forced costly outsourcing. The company expects it will take another three to four quarters for European margins to recover.
Funding the Future
Capital expenditure is running high to support this growth. First-half CapEx was ₹315 crore, nearly 90% higher than last year. Full-year spending is guided at ₹625-700 crore, focused on extruded tube capacity in China, India, and Europe.
This investment phase, funded partly by increased borrowings, pressures near-term cash flow. However, it builds the platform for what management confidently guides as "high-teens" revenue growth for the coming quarters.
Key Points
- Revenue growth hit a record 30%, driven by a 43% surge in the Beauty & Cosmetics segment, which is now the company's largest.
- Profit growth of 4.6% lagged significantly due to higher depreciation, supply chain costs, and profitability issues in Europe.
- Management reaffirmed guidance for high-teens revenue growth and underlying EBITDA margins above 20% for the near term.
- Elevated capital expenditure of ₹625-700 crore for FY27 is building capacity ahead of demand, supporting future growth but weighing on current returns.
Hexa Perspective
The quarter paints a clear picture of a company successfully investing for growth, with revenue momentum that is broad-based and sustainable. The tension lies in the timeline for profitability to catch up.
The margin compression is not from a failure to pass on input costs—management asserts full recovery—but from deliberate operating and capital spending to win market share. The payoff depends on European operations stabilizing as planned and the new capacity ramping up to drive operating leverage. For now, the market is weighing the robust top-line trajectory against the elevated costs required to sustain it.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.