Eighty Jewellers (EIGHTY) Q4 FY26 Profit Jumps 600% as Margins Recover
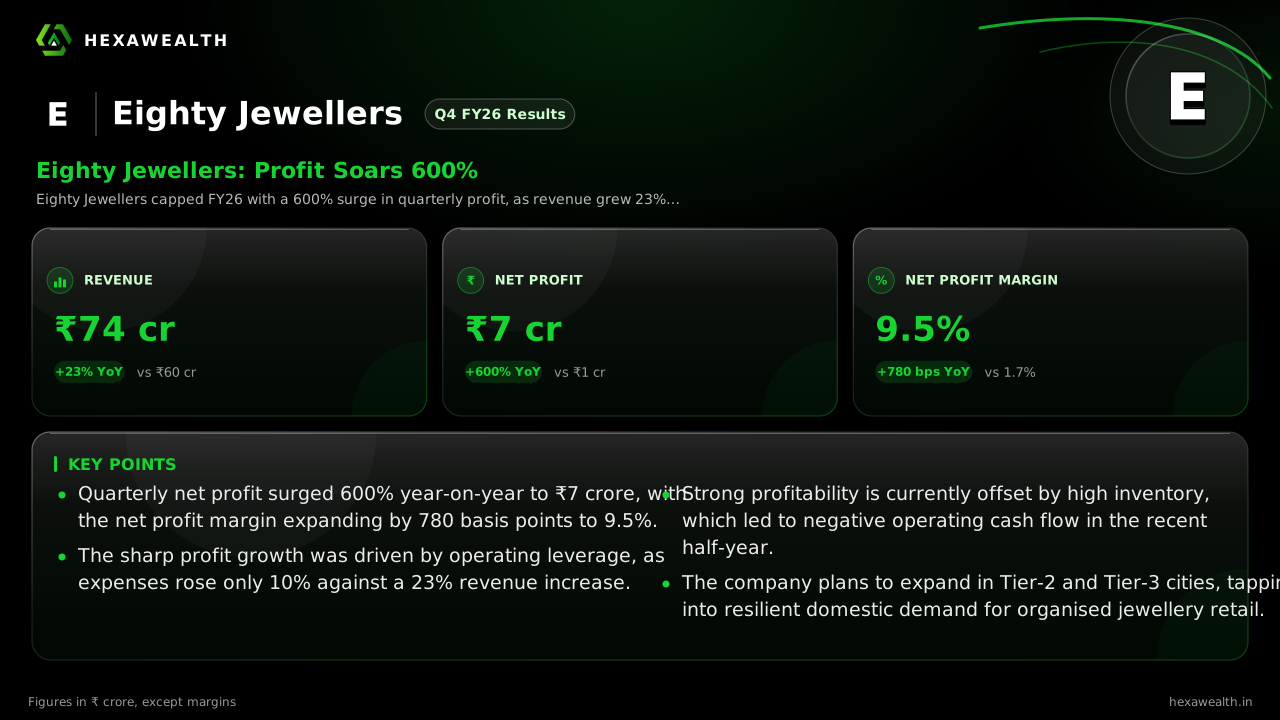
The jeweller's Q4 FY26 net profit surged to ₹7 crore, with margins expanding sharply from a low base as operating leverage kicked in.
Eighty Jewellers capped FY26 with a 600% surge in quarterly profit, as revenue grew 23% and net profit margin expanded to 9.5%. The annual profit jumped 426%, marking a sharp turnaround in profitability.
For a jewellery retailer, the past year was about navigating high gold prices and muted consumer volumes. Eighty Jewellers’ latest numbers show it has begun to turn that challenge into a story of margin recovery, with profit growth dramatically outpacing sales.
The March quarter revenue rose 23% year-on-year to ₹74 crore, while net profit surged 600% to ₹7 crore. The net profit margin expanded to 9.5%, up from just 1.7% a year earlier. Sequentially, both revenue and profit grew strongly, by 35% and 133% respectively.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 46.0
- Revenue (₹ Cr), Q2 FY25: 50.0
- Revenue (₹ Cr), Q4 FY25: 60.0
- Revenue (₹ Cr), Q2 FY26: 55.0
- Revenue (₹ Cr), Q4 FY26: 74.0
- Profit (₹ Cr), Q4 FY24: 1.0
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 1.0
- Profit (₹ Cr), Q2 FY26: 3.0
- Profit (₹ Cr), Q4 FY26: 7.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 46.0
- Revenue (₹ Cr), Q2 FY25: 50.0
- Revenue (₹ Cr), Q4 FY25: 60.0
- Revenue (₹ Cr), Q2 FY26: 55.0
- Revenue (₹ Cr), Q4 FY26: 74.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 1.0
- Profit (₹ Cr), Q2 FY25: 1.0
- Profit (₹ Cr), Q4 FY25: 1.0
- Profit (₹ Cr), Q2 FY26: 3.0
- Profit (₹ Cr), Q4 FY26: 7.0
Net Profit Margin
- Net Profit Margin, Q4 FY24: 2.2%
- Net Profit Margin, Q2 FY25: 2.0%
- Net Profit Margin, Q4 FY25: 1.7%
- Net Profit Margin, Q2 FY26: 5.5%
- Net Profit Margin, Q4 FY26: 9.5%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 74.0YoY +23% | 60.0 |
| Profit (₹ Cr) | 7.0YoY +600% | 1.0 |
| Net Profit Margin | 9.5%YoY +459% | 1.7% |
The operating leverage payoff
The margin expansion was driven by operating leverage, as expenses grew at a slower pace than sales. According to data from Newboard, the operating profit margin for the second half of FY26 reached 13.6%, a significant jump from 3.4% in the same period last year. This suggests better cost control and pricing power as sales volumes improved.
A cash flow catch
This profit surge, however, has not yet translated into strong operating cash flow. A report from Multibagg.ai notes that for the half-year ended September 2026, the company reported negative operating cash flow of ₹1.55 crore due to a significant inventory build-up. Inventory days have climbed to 209, according to Newboard, indicating cash is tied up in stock.
The road ahead
Management, in its annual report cited by FinancialFilings, aims to expand its retail footprint in Tier-2 and Tier-3 cities in Central India. The broader industry outlook offers a mixed picture. A Crisil Ratings report highlighted by The Week expects domestic jewellery demand to grow 12-15% this fiscal, supporting organised retailers, even as lab-grown diamonds reshape entry-level segments.
Live Chart
· EIGHTY
(BSE)
ISIN: INE0KSN01014
Key Points
- Quarterly net profit surged 600% year-on-year to ₹7 crore, with the net profit margin expanding by 780 basis points to 9.5%.
- The sharp profit growth was driven by operating leverage, as expenses rose only 10% against a 23% revenue increase.
- Strong profitability is currently offset by high inventory, which led to negative operating cash flow in the recent half-year.
- The company plans to expand in Tier-2 and Tier-3 cities, tapping into resilient domestic demand for organised jewellery retail.
Hexa Perspective
The quarter marks a decisive shift from top-line struggle to bottom-line delivery for Eighty Jewellers. The margin recovery from a deeply depressed base is the core story, showing the business can retain significantly more from each rupee of sales. The sustainability of this hinges on maintaining sales momentum to keep utilising operating leverage, especially with wedding and festive demand as tailwinds.
The inventory-heavy balance sheet and negative cash flow highlight the working capital intensity of the model. Investors are weighing a sharp earnings rebound against the capital required to fund growth and stock, with the stock trading at a significant discount to the industry average P/E.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.