All posts

Follow Us

LinkedInInstagramX
Quarterly ResultsArchiveLast updated 17 November 20262 min read

Ducol Organics (DUCOL) Q2 FY27 Profit Dives 46% as Revenue Slumps and Debt Costs Rise

Ducol Organics' Q2 profit fell 46% sequentially as standalone revenue dropped sharply and debt from recent acquisitions weighed on margins.

By Abhinav Singhvi, Founder & CEO Hexawealth · Created 17 November 2026

Ducol Organics reported a sharp decline in both revenue and profit for Q2 FY27, with profit falling 46% from the previous quarter. The drop comes despite recent acquisitions, as higher interest costs and lower other income squeezed margins.

Ducol Organics is navigating a transition, using acquisitions to build a specialty chemicals platform beyond its core pigment business. The September quarter shows that shift is still costly, with the old business slowing and the new one yet to deliver full operating leverage.

Standalone revenue fell 32% from the March quarter to ₹48.71 crore, pulling net profit down 46% to ₹2.15 crore. Compared to last year, sales were down 25% and profit fell 28%. The net profit margin slipped to 4.4%, down 120 basis points sequentially.

Revenue & profit

Revenue (₹ Cr)

Profit (₹ Cr)

Revenue & profitQ2 FY25 39.00, Q4 FY25 39.00, Q2 FY26 65.00, Q4 FY26 72.00, Q2 FY27 48.71. Q2 FY25 3.00, Q4 FY25 2.00, Q2 FY26 3.00, Q4 FY26 4.00, Q2 FY27 2.15020406080Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Revenue (₹ Cr), Q2 FY25: 39.00
  • Revenue (₹ Cr), Q4 FY25: 39.00
  • Revenue (₹ Cr), Q2 FY26: 65.00
  • Revenue (₹ Cr), Q4 FY26: 72.00
  • Revenue (₹ Cr), Q2 FY27: 48.71
  • Profit (₹ Cr), Q2 FY25: 3.00
  • Profit (₹ Cr), Q4 FY25: 2.00
  • Profit (₹ Cr), Q2 FY26: 3.00
  • Profit (₹ Cr), Q4 FY26: 4.00
  • Profit (₹ Cr), Q2 FY27: 2.15

Revenue (₹ Cr)

Revenue (₹ Cr)Q2 FY25 39.00, Q4 FY25 39.00, Q2 FY26 65.00, Q4 FY26 72.00, Q2 FY27 48.71020406080Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Revenue (₹ Cr), Q2 FY25: 39.00
  • Revenue (₹ Cr), Q4 FY25: 39.00
  • Revenue (₹ Cr), Q2 FY26: 65.00
  • Revenue (₹ Cr), Q4 FY26: 72.00
  • Revenue (₹ Cr), Q2 FY27: 48.71

Profit (₹ Cr)

Profit (₹ Cr)Q2 FY25 3.00, Q4 FY25 2.00, Q2 FY26 3.00, Q4 FY26 4.00, Q2 FY27 2.1502468Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Profit (₹ Cr), Q2 FY25: 3.00
  • Profit (₹ Cr), Q4 FY25: 2.00
  • Profit (₹ Cr), Q2 FY26: 3.00
  • Profit (₹ Cr), Q4 FY26: 4.00
  • Profit (₹ Cr), Q2 FY27: 2.15

Net Profit Margin (%)

Net Profit Margin (%)Q2 FY25 7.7, Q4 FY25 5.1, Q2 FY26 4.6, Q4 FY26 5.6, Q2 FY27 4.40%5%10%15%20%Q2 '25Q4 '25Q2 '26Q4 '26Q2 '27
  • Net Profit Margin (%), Q2 FY25: 7.7
  • Net Profit Margin (%), Q4 FY25: 5.1
  • Net Profit Margin (%), Q2 FY26: 4.6
  • Net Profit Margin (%), Q4 FY26: 5.6
  • Net Profit Margin (%), Q2 FY27: 4.4
MetricCurrentQ2 FY27Same quarter LYQ2 FY26
Revenue (₹ Cr)
48.71YoY -25%
65.00
Profit (₹ Cr)
2.15YoY -28%
3.00
Net Profit Margin (%)
4.4YoY -4.3%
4.6

Why the top line shrank

A sharp 74% drop in other income and a 38% year-on-year jump in interest expense compounded the revenue decline. According to the company's investor presentation cited by Arthneeti, the higher finance cost of ₹1.79 crore for the half-year is due to acquisition-related borrowings. Long-term borrowings rose from ₹23.11 crore in March to ₹40.21 crore in September.

The acquisition story behind the numbers

The weak standalone print contrasts with a stronger consolidated picture, which includes recent buys Bitumag and Xchem. Management, in its maiden earnings call summarized by ALFA Finder, said H1 consolidated revenue was ₹112.26 crore, up 74% year-on-year and driven by these acquisitions. The call summary notes the acquired units currently deliver 9-10% EBITA margins, below the 12-15% target.

A long runway for integration

With the new businesses running at just 30-35% capacity, the path to better margins relies on utilization and cross-selling. Management targets at least a 10.5% consolidated EBITDA margin for FY27, as reported by Sovrenn. They see no need for major new capacity, expecting growth from better use of existing plants.

Live Chart

· DUCOL

(BSE)

ISIN: INE0LZO01015

Key Points

  • Standalone revenue fell 32% quarter-on-quarter and 25% year-on-year, reflecting weakness in the core pigment dispersion business.
  • Net profit declined more sharply, down 46% QoQ, as higher interest costs and lower other income pressured margins.
  • The company's growth story now hinges on newly acquired construction chemical units, which are currently operating at low utilization.
  • Management's medium-term target is to triple revenue to ₹400-500 crore within three years, driven by these acquisitions.

Hexa Perspective

The quarter lays bare the tension in Ducol's strategy. The core business is contracting just as debt-funded acquisitions add cost. The promise is in the long runway of the new units, but the near term is a squeeze. Investors are being asked to fund a transition where the payoff depends entirely on execution—ramping utilization, achieving cross-sales, and managing a higher debt load. The stock's 32% decline over the past year suggests the market is pricing in that execution risk.

Share or follow HexaWealth

Also read

Want this applied to your portfolio?

Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.
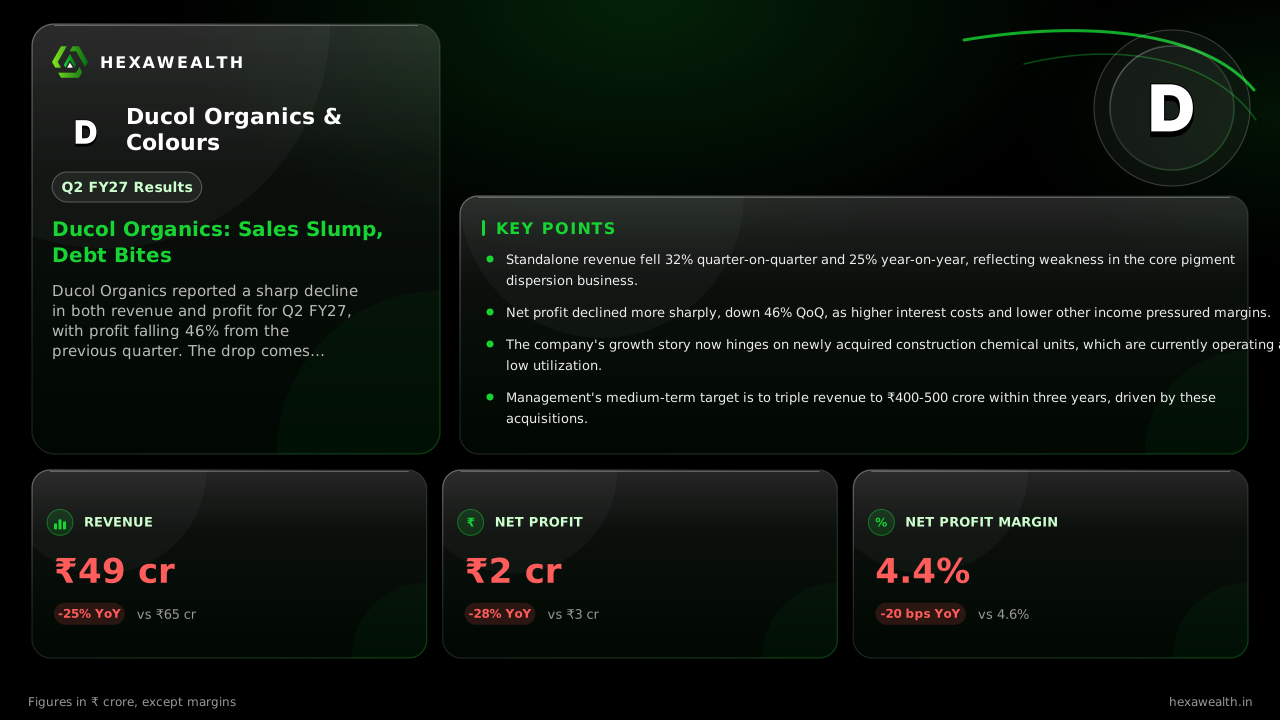
Ducol Organics & Colours (DUCOL) Q2 FY27 results, revenue and profits.

Frequently asked questions

What were Ducol Organics' Q2 FY27 results?
For Q2 FY27 (quarter ended September 2026), Ducol Organics reported standalone revenue of ₹48.71 crore and a net profit of ₹2.15 crore. Revenue fell 25% year-on-year and 32% from the previous quarter, while profit declined 28% YoY and 46% sequentially.
Why did Ducol Organics' Q2 FY27 profit drop?
Ducol Organics' Q2 profit fell due to a sharp decline in standalone revenue and higher financing costs. Interest expense rose 38% year-on-year due to debt taken for acquisitions, while other income dropped 74%. This squeezed the net profit margin down to 4.4%.
What was Ducol Organics' net profit margin in Q2 FY27?
Ducol Organics' net profit margin was 4.4% for Q2 FY27 (quarter ended September 2026). This represents a decline of 120 basis points from the previous quarter (Q4 FY26) and 20 basis points from the same quarter last year.
Why did Ducol Organics' interest expense increase in Q2 FY27?
Ducol Organics' interest expense rose 38% year-on-year in Q2 FY27 due to borrowings taken on to fund recent acquisitions. According to the company's investor presentation, acquisition-related finance costs added ₹1.79 crore in H1 FY27, increasing total debt.
What guidance did Ducol Organics management give for future quarters?
In its Q2 FY27 concall, Ducol management targeted a consolidated EBITDA margin of at least 10.5% for FY27. They aim to triple revenue from acquired businesses, reaching a ₹400-500 crore top line within three years, as reported by Sovrenn and ALFA Finder.
What is the status of Ducol Organics' capacity expansion?
Management stated there is no requirement for major new capacity. According to a blog by Perivis, refurbishment spending of ₹5-7 crore is planned. The focus is on raising utilization of recently acquired units, which are currently at 30-35% capacity.
Did Ducol Organics Q2 FY27 results beat analyst estimates?
The company's maiden earnings call provided no prior guidance for comparison. The standalone results showed a significant sequential decline, while the consolidated H1 performance, driven by acquisitions, showed strong growth but with margins below target levels.
What caused the 74% drop in other income for Ducol Organics?
Ducol Organics' other income fell 74% year-on-year in Q2 FY27 to ₹0.52 crore, from ₹2.0 crore in Q2 FY26. This sharp decline contributed to the overall drop in total income and profit, though the specific cause was not detailed in available reports.
What is Ducol Organics' debt position after Q2 FY27?
As of September 2026, Ducol Organics' long-term borrowings stood at ₹40.21 crore, up from ₹23.11 crore in March 2026, as per its investor presentation. Short-term borrowings also increased slightly. This debt was raised primarily to fund acquisitions.
What is the demand outlook for Ducol Organics' pigment business?
The broader pigments market in India is projected to grow at a 4.1% CAGR through 2032, as per a Ken Research report. However, Ducol's standalone revenue decline suggests company-specific challenges or a strategic shift away from its traditional pigment dispersion segment.
Ducol Organics Q2 profit drop
Ducol Organics' Q2 FY27 standalone net profit dropped 46% quarter-on-quarter and 28% year-on-year to ₹2.15 crore. The decline was driven by a 32% sequential fall in revenue to ₹48.71 crore and increased interest costs from acquisition-related debt.
Ducol Organics September quarter profit
For the September 2026 quarter (Q2 FY27), Ducol Organics reported a standalone net profit of ₹2.15 crore. This marks a 28% decrease from the ₹3.0 crore profit earned in the September 2025 quarter, as revenue fell 25% over the same period.