Droneacharya (DRONACHRYA) Q4 FY26 Profit Hangs by a Thread as Revenue Plunges 58% in FY26
The drone services firm posted a slim annual profit despite a dramatic revenue collapse, raising questions about its path to sustainable growth.
Droneacharya Aerial Innovations reported a 58% plunge in FY26 revenue to ₹14.67 crore. Its net profit was a wafer-thin ₹0.37 crore, saved by a steep cut in expenses and higher other income.
For Droneacharya, FY26 was a year of severe contraction. The drone services and training company managed to turn a small annual profit, but only after its revenue more than halved and it slashed costs deeply, a pattern that questions the durability of its business model.
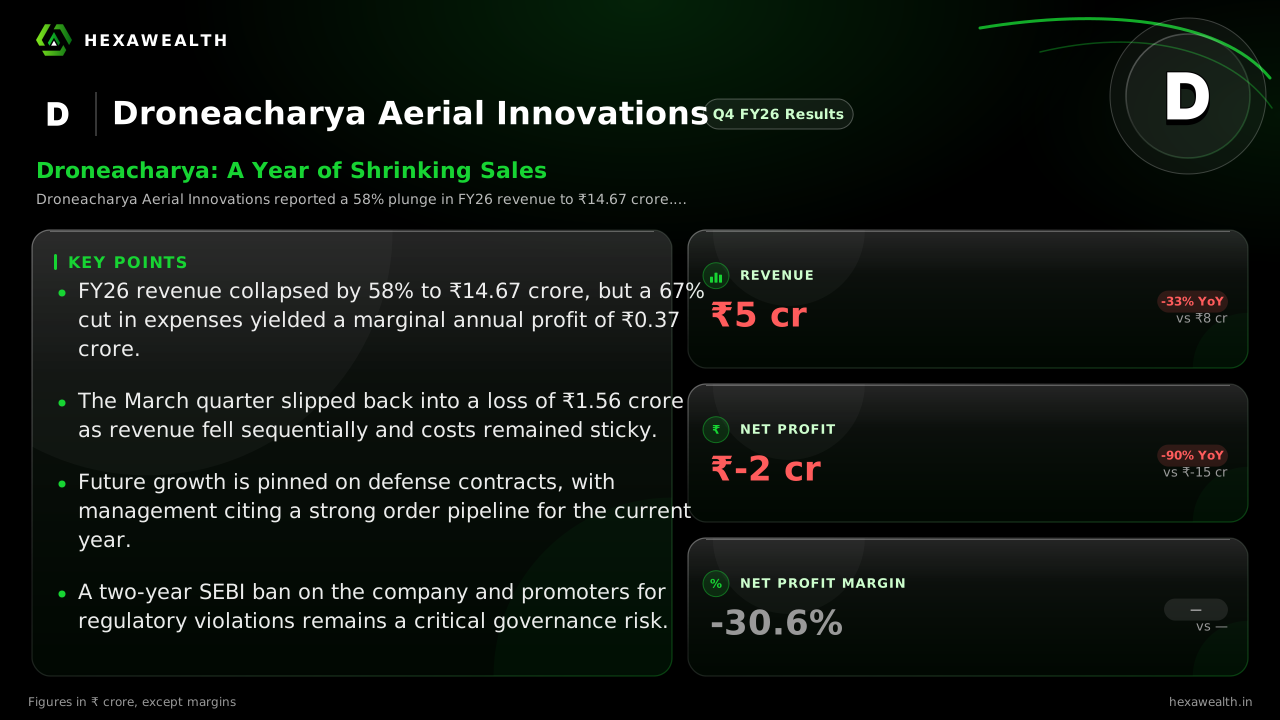
The numbers tell a story of sharp decline. Annual revenue fell 58% to ₹14.67 crore, while the March quarter revenue dropped 33% year-on-year to ₹5.09 crore. The company swung to a net loss of ₹1.56 crore in Q4 FY26 from a profit of ₹1.94 crore in the previous September quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 14.36
- Revenue (₹ Cr), Q2 FY25: 26.90
- Revenue (₹ Cr), Q4 FY25: 7.62
- Revenue (₹ Cr), Q2 FY26: 9.58
- Revenue (₹ Cr), Q4 FY26: 5.09
- Profit (₹ Cr), Q4 FY24: 2.12
- Profit (₹ Cr), Q2 FY25: 1.51
- Profit (₹ Cr), Q4 FY25: -14.98
- Profit (₹ Cr), Q2 FY26: 1.94
- Profit (₹ Cr), Q4 FY26: -1.56
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 14.36
- Revenue (₹ Cr), Q2 FY25: 26.90
- Revenue (₹ Cr), Q4 FY25: 7.62
- Revenue (₹ Cr), Q2 FY26: 9.58
- Revenue (₹ Cr), Q4 FY26: 5.09
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 2.12
- Profit (₹ Cr), Q2 FY25: 1.51
- Profit (₹ Cr), Q4 FY25: -14.98
- Profit (₹ Cr), Q2 FY26: 1.94
- Profit (₹ Cr), Q4 FY26: -1.56
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 5.09YoY -33% | 7.62 |
| Profit (₹ Cr) | -1.56YoY +90% | -14.98 |
| Net Margin (%) | -30.6 | - |
The Cost-Cut That Saved the Year
The annual profit of ₹0.37 crore was entirely propped up by aggressive cost-cutting. According to data from The Economic Times, total expenses plunged 67% in FY26 to ₹17.77 crore. This dramatic reduction, far outpacing the revenue fall, turned a massive loss in FY25 into a slim profit.
This austerity, however, could not prevent a Q4 loss. High depreciation and employee costs continued to pressure margins as sales dwindled. The quarterly net profit margin swung from a positive 20.3% in September to negative 30.6% in March.
A Pipeline of Hope Amid Regulatory Clouds
Management, cited by Indian Startup News, points to a robust order pipeline from defense and enterprise customers for FY27. The company has secured several orders from the Indian Army, including one worth ₹71.2 million noted by MarketScreener. This defense focus is now the central growth narrative.
Live Chart
· DRONACHRYA
(BSE)
ISIN: INE0MQD01015
Yet, a significant regulatory overhang persists. In November 2026, SEBI barred the company and its promoters from the securities market for two years, alleging IPO fund diversion and misleading announcements, as reported by The Economic Times. This casts a long shadow over governance and investor trust.
Key Points
- FY26 revenue collapsed by 58% to ₹14.67 crore, but a 67% cut in expenses yielded a marginal annual profit of ₹0.37 crore.
- The March quarter slipped back into a loss of ₹1.56 crore as revenue fell sequentially and costs remained sticky.
- Future growth is pinned on defense contracts, with management citing a strong order pipeline for the current year.
- A two-year SEBI ban on the company and promoters for regulatory violations remains a critical governance risk.
Hexa Perspective
The FY26 numbers reveal a company surviving on cost control, not growth. The defense order book offers a potential lifeline, but converting it into steady, profitable revenue is the next hurdle. The severe SEBI action complicates this path, as it undermines credibility with both clients and investors.
The stock's valuation, at a P/E of 182.8 against an industry average of 94.4, prices in a rapid recovery that these results do not yet support. Investors are betting on the defense story materializing before the cash from past orders runs out.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.