Citius TransNet (CITIUSINVT) Q2 FY27 Revenue Jumps 49% in First Full Quarter of Operations
The infrastructure trust's first full quarter of operations drove a major revenue increase, though heavy depreciation keeps the bottom line in the red.
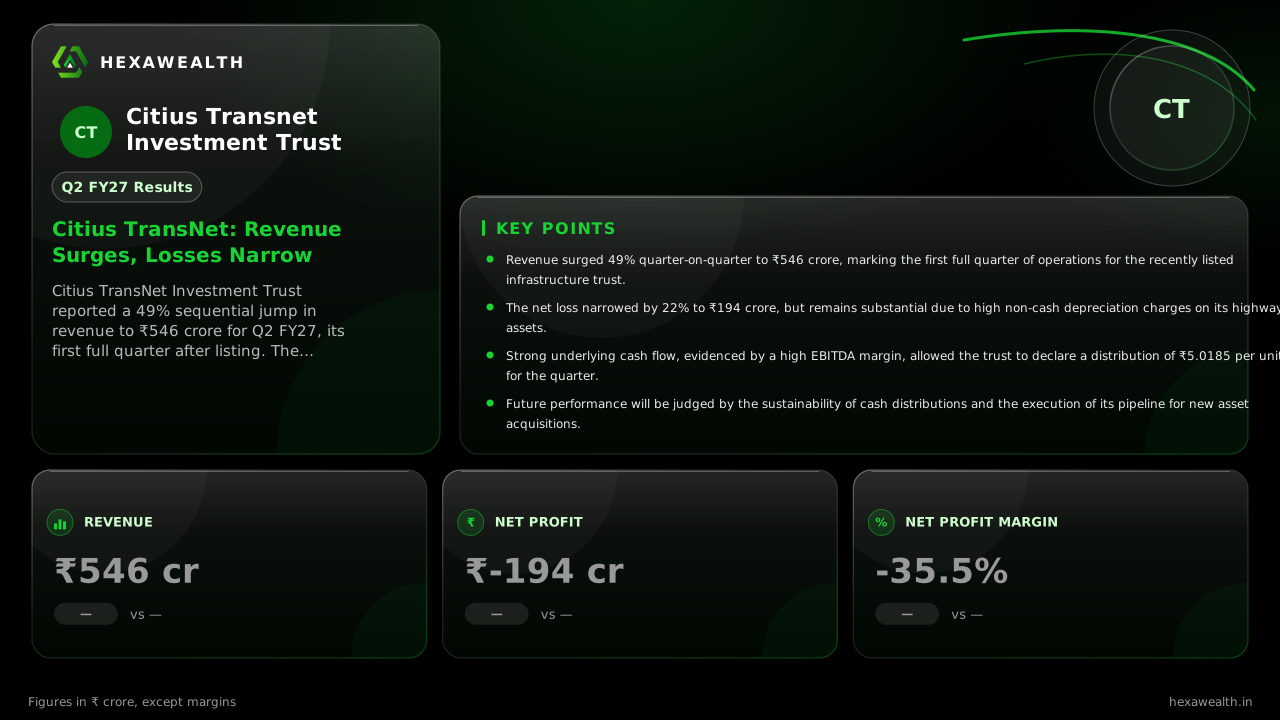
Citius TransNet Investment Trust reported a 49% sequential jump in revenue to ₹546 crore for Q2 FY27, its first full quarter after listing. The net loss narrowed by 22% to ₹194 crore, weighed by substantial non-cash depreciation charges.
For a newly listed infrastructure trust, the first full quarter of operations is the real test of its asset portfolio. Citius TransNet Investment Trust passed that test on the top line, with revenue surging nearly 50% as its 10 highway SPVs began contributing fully. Yet, the statutory profit and loss statement tells a story of heavy upfront accounting costs, keeping the bottom line deep in the red.
The numbers show a business ramping up. Revenue climbed to ₹546 crore in the September quarter, up from ₹366 crore in June. The net loss improved to ₹194 crore from ₹249 crore. A look at the recent trajectory shows the trust moving from virtually no activity to significant revenue generation.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY26: 0.0
- Revenue (₹ Cr), Q1 FY27: 365.86
- Revenue (₹ Cr), Q2 FY27: 546.0
- Profit (₹ Cr), Q4 FY26: -3.0
- Profit (₹ Cr), Q1 FY27: -248.72
- Profit (₹ Cr), Q2 FY27: -194.0
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY26: 0.0
- Revenue (₹ Cr), Q1 FY27: 365.86
- Revenue (₹ Cr), Q2 FY27: 546.0
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY26: -3.0
- Profit (₹ Cr), Q1 FY27: -248.72
- Profit (₹ Cr), Q2 FY27: -194.0
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 |
|---|---|---|
| Period Ended | September 2026 | June 2026 |
| Revenue (₹ Cr) | 546.0 | 365.86 |
| Profit (₹ Cr) | -194.0 | -248.72 |
Why the loss persists despite strong cash flow
The gap between the growing revenue and the persistent loss is almost entirely due to non-cash charges. According to a report by ScanX, the trust booked a massive ₹3,848 crore in depreciation and amortization for the quarter. This is standard for highway concessions, where intangible assets are amortized heavily in the early years.
This means the underlying operations are far healthier than the net loss suggests. The same ScanX report notes the trust's EBITDA margin was a robust 71.7%, indicating strong operational cash generation. This cash flow supports the quarterly distribution to unitholders, which was declared at ₹5.0185 per unit.
The outlook hinges on cash distributions
With profitability on a statutory basis years away due to accounting rules, the investment case rests on cash distributions and asset growth. The trust has already taken steps to support near-term payouts, with unitholders approving a move to add debt-funded maintenance costs back into its distributable cash flow calculation, as noted by Flash Finance.
Live Chart
· CITIUSINVT
(BSE)
ISIN: INE2Q7823014
Its leverage, with a net borrowing ratio of 33.85% per ScanX, provides room for growth. The trust also holds a Right of First Offer on 11 more highway projects, which could expand its asset base and future cash flows.
Key Points
- Revenue surged 49% quarter-on-quarter to ₹546 crore, marking the first full quarter of operations for the recently listed infrastructure trust.
- The net loss narrowed by 22% to ₹194 crore, but remains substantial due to high non-cash depreciation charges on its highway assets.
- Strong underlying cash flow, evidenced by a high EBITDA margin, allowed the trust to declare a distribution of ₹5.0185 per unit for the quarter.
- Future performance will be judged by the sustainability of cash distributions and the execution of its pipeline for new asset acquisitions.
Hexa Perspective
Citius TransNet's quarter confirms the operational viability of its portfolio, with revenue scaling as expected. The story here is one of cash flow versus accounting profit. Investors are being paid a yield from robust operational earnings, even as the P&L shows deep losses.
The path forward is clear: stability in toll collections and annuity payments to maintain distributions, and prudent use of debt capacity to acquire new assets from its pipeline. The trust's success will be measured in distribution per unit, not earnings per share, for the foreseeable future.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.