BITS Q2 FY27 Profit Doubles on Cost Cuts as Revenue Growth Stalls
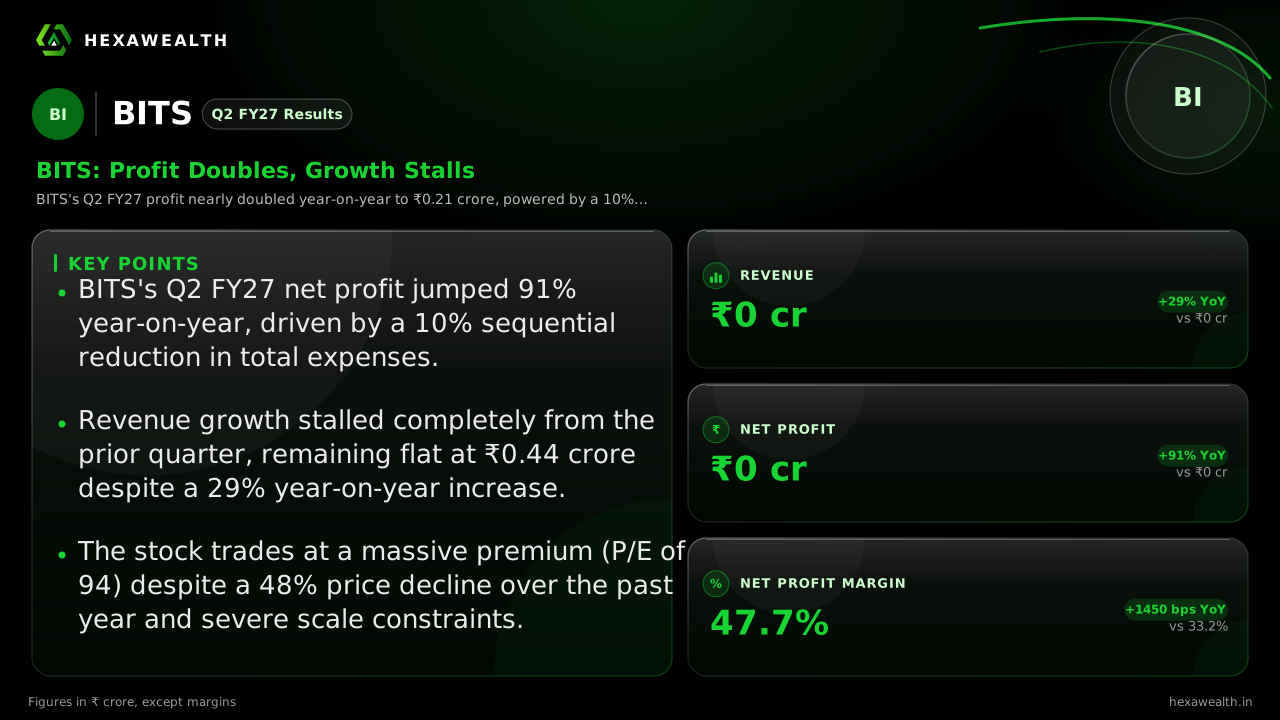
BITS reported a 91% surge in Q2 FY27 net profit, driven by sharp expense control, but sequential revenue growth hit zero, highlighting scale challenges.
BITS's Q2 FY27 profit nearly doubled year-on-year to ₹0.21 crore, powered by a 10% sequential drop in expenses. However, revenue remained flat from the previous quarter at ₹0.44 crore, underscoring the micro-cap education firm's struggle to scale.
For a micro-cap education firm like BITS, the story is often one of growth versus scale. The September quarter delivered a stark illustration of that tension, with profitability soaring even as the top line stopped moving.
Revenue for Q2 FY27 was ₹0.44 crore, a solid 29% higher than the year-ago period but identical to the June quarter. Profit, however, leapt 91% year-on-year and 17% sequentially to ₹0.21 crore. The profit surge was powered entirely by cost discipline, with total expenses falling 10% from the prior quarter.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 0.44YoY +29% | 0.43 | 0.34 |
| Profit (₹ Cr) | 0.21YoY +91% | 0.18 | 0.11 |
| Net Profit Margin | 47.7%YoY +44% | 40.5% | 33.2% |
Where the profit came from
The margin expansion was operational, not a one-off. According to MarketPing, EBITDA jumped 20% quarter-on-quarter to ₹0.24 crore. The company controlled employee costs, which MarketsMojo noted were marginally lower, while other expenses fell sharply. This efficiency drove the net profit margin up 720 basis points to 47.7%.
The growth ceiling that remains
Despite the profit jump, the flat sequential revenue is a red flag. MarketsMoji's analysis pointed to the company's "severe scale limitations," with an annualised revenue run-rate still below ₹2 crore. This tiny base restricts investment in technology and market expansion, creating a cycle that's hard to break. The business operates in a single segment, offering no diversification to fuel a breakout.
The market's reaction has been brutally clear. The stock is down over 48% in the past year, trading at a P/E of 94 against an industry average of 14. This extreme valuation disconnect, as highlighted by research, reflects deep scepticism about the sustainability of growth at this scale.
Key Points
- BITS's Q2 FY27 net profit jumped 91% year-on-year, driven by a 10% sequential reduction in total expenses.
- Revenue growth stalled completely from the prior quarter, remaining flat at ₹0.44 crore despite a 29% year-on-year increase.
- The stock trades at a massive premium (P/E of 94) despite a 48% price decline over the past year and severe scale constraints.
Hexa Perspective
The quarter presents a classic micro-cap dilemma: impressive operating leverage on a minuscule base, but no evidence of breaking out of it. The cost cuts that flattered profit this quarter are not a repeatable annual strategy. For the narrative to change, BITS must demonstrate sequential revenue momentum, not just yearly comparisons. Until then, the stock's extreme valuation premium looks like a legacy of speculation, not a bet on fundamental scalability. Investors are weighing whether this is a niche operator hitting its ceiling or a business on the cusp of finding a new gear.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.