Mrs. Bectors (BECTORFOOD) Q2 FY27 Profit Jumps 26% as Margins Widen
The biscuit and bakery maker posted strong Q2 FY27 results, with profit growth outpacing revenue on the back of improved operational efficiency.
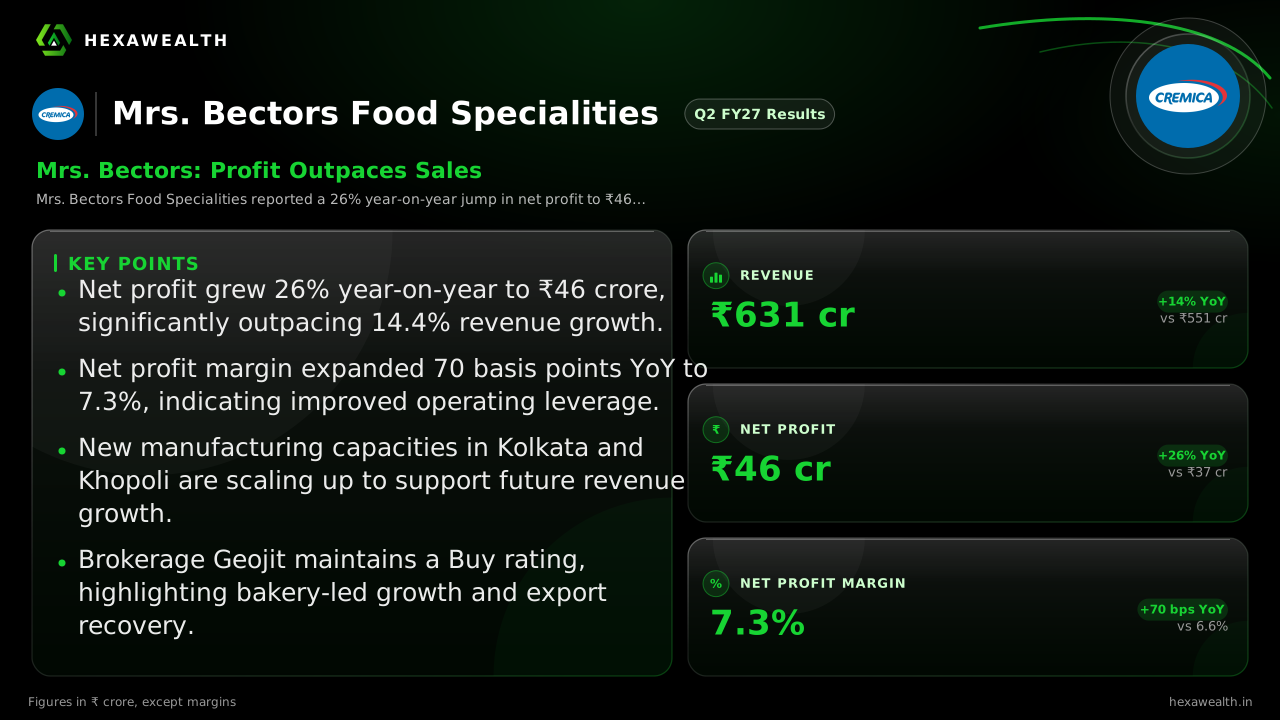
Mrs. Bectors Food Specialities reported a 26% year-on-year jump in net profit to ₹46 crore for Q2 FY27. Revenue grew 14.4% to ₹631 crore, with margins expanding despite rising costs.
Mrs. Bectors entered the second half of FY27 with momentum, as its September quarter delivered a clear sign of operating leverage. Profit grew faster than sales, a shift that points to the company’s capacity investments beginning to pay off.
Revenue reached ₹631 crore, up 14.4% from a year ago and 15% from the June quarter. Net profit rose 26% year-on-year to ₹46 crore, lifting the net profit margin by 70 basis points to 7.3%. The business is building scale.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 | PreviousQ1 FY27 | Same quarter LYQ2 FY26 |
|---|---|---|---|
| Revenue (₹ Cr) | 631.0YoY +14% | 548.8 | 551.4 |
| Profit (₹ Cr) | 46.0YoY +26% | 38.8 | 36.5 |
| Net Profit Margin | 7.3%YoY +11% | 7.1% | 6.6% |
Why Margins Expanded Despite Higher Costs
Total expenses rose 13.5% year-on-year, but profit grew faster. According to CNBC-TV18, EBITDA margin improved 50 basis points to 13.1%. This suggests better cost management and a favorable sales mix.
The company’s bakery segment, including the English Oven brand, and its strategic export supply to Walmart are key growth drivers. Management had warned Q2 would face sharper input cost inflation, but pricing actions and operational efficiencies provided a cushion.
The Capacity Bet and Its Timeline
Growth is supported by new plants in Kolkata and Khopoli. A report from StoxBox notes these facilities, plus a planned Bangalore expansion, could support revenue potential of ₹3,400-3,500 crore.
Current annual capex is around ₹200 crore, funded 60% from internal accruals. The comfortable debt-to-equity ratio of 0.1 provides room for this expansion without straining the balance sheet.
What the Market Is Watching
The stock closed at ₹208.16 on November 4, the day the results were approved. Brokerage Geojit retained a Buy rating with a target of ₹290 in a September update, citing capacity-led growth visibility.
Key risks remain input cost inflation and the pace of new capacity utilisation. Management targets a 14% EBITDA margin by Q4 FY27, a goal investors will track closely.
Key Points
- Net profit grew 26% year-on-year to ₹46 crore, significantly outpacing 14.4% revenue growth.
- Net profit margin expanded 70 basis points YoY to 7.3%, indicating improved operating leverage.
- New manufacturing capacities in Kolkata and Khopoli are scaling up to support future revenue growth.
- Brokerage Geojit maintains a Buy rating, highlighting bakery-led growth and export recovery.
Hexa Perspective
This quarter shows Mrs. Bectors moving from a pure top-line growth story to one where margins are beginning to respond to scale. The 70-basis-point margin expansion, while modest, is a positive signal after years of capacity investment.
The thesis now hinges on execution. Can the company fill its new plants on schedule and hit its 14% EBITDA margin target by year-end? Input costs remain a wild card, but the low debt level provides a buffer to navigate volatility.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.