Ajooni Biotech (AJOONI) Q2 FY27 Profit Squeezed as Costs Outpace Record Sales
The animal feed maker's revenue more than doubled year-on-year, but a sharp rise in raw material and finance costs cut net profit by 45%.
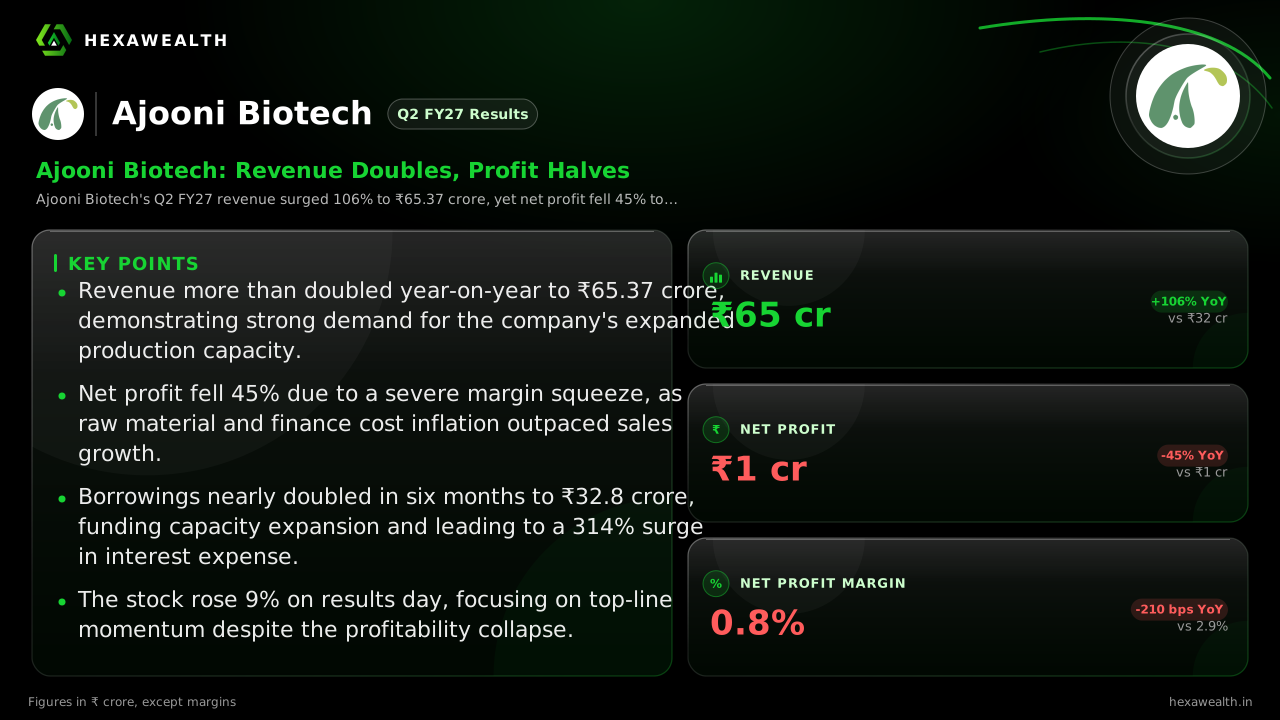
Ajooni Biotech's Q2 FY27 revenue surged 106% to ₹65.37 crore, yet net profit fell 45% to ₹0.51 crore. Soaring input and interest costs severely compressed margins, overshadowing the top-line growth from its expanded capacity.
For Ajooni Biotech, scaling up has come with a painful squeeze. The animal feed manufacturer's September quarter revenue more than doubled from a year ago, a clear sign its expanded capacity is finding a market. Yet, the cost of that growth has gutted profitability, with net profit nearly halving.
The numbers tell a story of two diverging lines. Revenue reached ₹65.37 crore, up 106% year-on-year and 3% from the June quarter. Profit, however, fell 45% to ₹0.51 crore, though it improved 19% sequentially. The net profit margin collapsed to 0.8%, down 210 basis points from last year.
Revenue & profit
Revenue (₹ Cr)
Net Profit (₹ Cr)
Net Profit Margin
| Metric | CurrentQ2 FY27 (Sep '26) | PreviousQ1 FY27 (Jun '26) |
|---|---|---|
| Revenue (₹ Cr) | 65.37 | 63.49 |
| Net Profit (₹ Cr) | 0.51 | 0.43 |
| Net Profit Margin | 0.8% | 0.7% |
Why the growth didn't reach the bottom line
Total expenses surged 112%, even faster than revenue. According to MarketPing, the cost of materials consumed jumped 118.5% to ₹54.48 crore. This reflects volatile prices for key inputs like maize and soybean meal, which a DairyNews report says were 15-20% more expensive in September 2026 than a year earlier.
Financing the expansion added another heavy burden. Interest expense rocketed 314% year-on-year to ₹0.71 crore, while depreciation rose 276% to ₹0.92 crore. This stems from the new ₹16.5 crore manufacturing unit in Khanna, Punjab, which Flash Finance reports has tripled annual capacity to 180,000 MT. Borrowings nearly doubled to ₹32.8 crore in six months to fund this growth and working capital.
The market's muted reaction
Despite the stark profit decline, the stock closed 9.1% higher at ₹3.13 on results day. The sharp revenue growth likely provided some solace. Analyst coverage remains sparse; Sharpely notes no active brokerage recommendations or price targets for the stock.
The company carries a 'BB+' credit rating from CRISIL, indicating moderate risk. Institutional investors are absent, with promoter holding at 30.53% and the rest largely with retail shareholders, as per Laabh data.
Key Points
- Revenue more than doubled year-on-year to ₹65.37 crore, demonstrating strong demand for the company's expanded production capacity.
- Net profit fell 45% due to a severe margin squeeze, as raw material and finance cost inflation outpaced sales growth.
- Borrowings nearly doubled in six months to ₹32.8 crore, funding capacity expansion and leading to a 314% surge in interest expense.
- The stock rose 9% on results day, focusing on top-line momentum despite the profitability collapse.
Hexa Perspective
Ajooni Biotech is caught in a classic growth trap. Its new capacity is driving impressive sales, but the business lacks pricing power to pass on rampant input cost inflation. With net profit margin at 0.8%—a fraction of its trailing average—the model is fragile.
The next few quarters hinge on whether raw material costs ease or the company can achieve better operational leverage from its higher scale. Until then, profitability will remain under severe pressure, making the current revenue surge a high-cost endeavor.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.