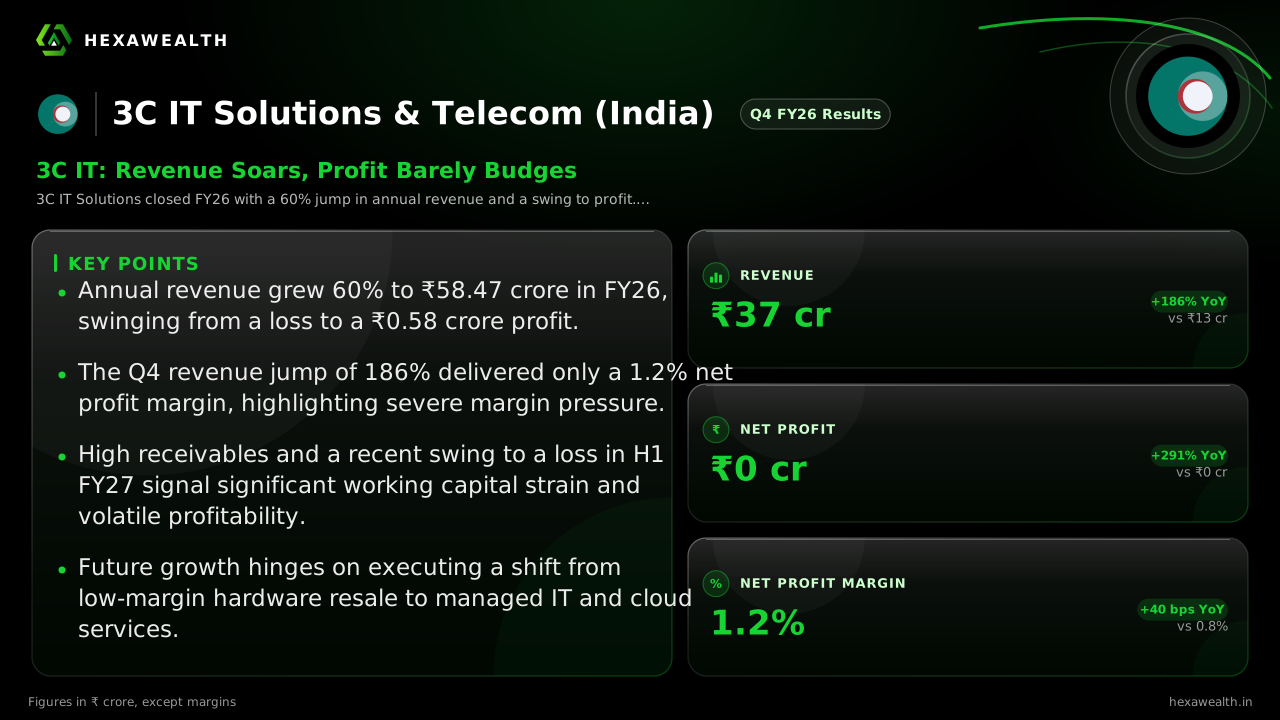
3C IT Solutions (3CIT) Q4 FY26' Revenue Triples, But Profit Growth Stalls at 1% Margin
The IT infrastructure firm's March quarter revenue surged 186% year-on-year, yet net profit margin remained wafer-thin at 1.2%.
3C IT Solutions closed FY26 with a 60% jump in annual revenue and a swing to profit. However, its Q4 performance reveals a deeper story of massive top-line growth failing to translate into meaningful bottom-line gains.
For a small-cap IT infrastructure firm, a quarter of explosive growth can be a double-edged sword. 3C IT Solutions' revenue more than tripled from a year ago, but the bottom line tells a story of a business running hard just to stay a few steps ahead of its costs.
The March quarter revenue hit ₹37.28 crore, a 186% leap from the same period last year and a 76% jump from the September quarter. Net profit for the quarter was ₹0.43 crore, up 291% year-on-year. Yet, the net profit margin inched up to just 1.2%, a gain of only 40 basis points from a year earlier.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 12.47
- Revenue (₹ Cr), Q2 FY25: 23.49
- Revenue (₹ Cr), Q4 FY25: 13.02
- Revenue (₹ Cr), Q2 FY26: 21.19
- Revenue (₹ Cr), Q4 FY26: 37.28
- Profit (₹ Cr), Q4 FY24: 0.75
- Profit (₹ Cr), Q2 FY25: -0.17
- Profit (₹ Cr), Q4 FY25: 0.11
- Profit (₹ Cr), Q2 FY26: 0.14
- Profit (₹ Cr), Q4 FY26: 0.43
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY24: 12.47
- Revenue (₹ Cr), Q2 FY25: 23.49
- Revenue (₹ Cr), Q4 FY25: 13.02
- Revenue (₹ Cr), Q2 FY26: 21.19
- Revenue (₹ Cr), Q4 FY26: 37.28
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY24: 0.75
- Profit (₹ Cr), Q2 FY25: -0.17
- Profit (₹ Cr), Q4 FY25: 0.11
- Profit (₹ Cr), Q2 FY26: 0.14
- Profit (₹ Cr), Q4 FY26: 0.43
Net Profit Margin
- Net Profit Margin, Q4 FY24: 6.0%
- Net Profit Margin, Q2 FY25: -0.7%
- Net Profit Margin, Q4 FY25: 0.8%
- Net Profit Margin, Q2 FY26: 0.7%
- Net Profit Margin, Q4 FY26: 1.2%
| Metric | CurrentQ4 FY26 | Same quarter LYQ4 FY25 |
|---|---|---|
| Revenue (₹ Cr) | 37.28YoY +186% | 13.02 |
| Profit (₹ Cr) | 0.43YoY +291% | 0.11 |
| Net Profit Margin | 1.2%YoY +50% | 0.8% |
Why the profit didn't keep pace
The surge was driven by volume, not pricing power. Research from ScanX.trade notes the company's profitability is driven largely by volume growth rather than margin expansion. This points to a model of low-margin hardware resale and trading, where costs rise almost in lockstep with sales.
Expenses grew 185% year-on-year, nearly matching the revenue jump. The company's own strategic focus, outlined in its annual report, is on cloud, cybersecurity, and managed services. But the recent revenue spike appears tied to hardware orders, like a ₹9.08 crore desktop supply deal noted by MCapital.
The working capital squeeze
Growth at this scale strains a small balance sheet. Trade receivables were a high ₹29.29 crore as of September 2026, per MCapital analysis, indicating cash is tied up with customers. Inventory more than doubled in the first half of FY27, further tightening working capital.
Live Chart
· 3CIT
(BSE)
ISIN: INE0R7D01018
This creates a cycle where more sales require more upfront capital, leaving little room for error or delay in collections. The company's debtor days stood at 206 days for FY26, according to data from Cruxal.in.
What comes next?
The outlook is clouded by a sharp reversal in the following half-year. For the six months ended September 2026, the company reported a net loss of ₹0.85 crore on revenue of ₹42.67 crore. This suggests the Q4 surge may have been episodic.
Management has not provided formal guidance, but the focus remains on higher-margin service verticals. The sustainability of growth now depends on shifting the business mix away from thin-margin trading.
Key Points
- Annual revenue grew 60% to ₹58.47 crore in FY26, swinging from a loss to a ₹0.58 crore profit.
- The Q4 revenue jump of 186% delivered only a 1.2% net profit margin, highlighting severe margin pressure.
- High receivables and a recent swing to a loss in H1 FY27 signal significant working capital strain and volatile profitability.
- Future growth hinges on executing a shift from low-margin hardware resale to managed IT and cloud services.
Hexa Perspective
This quarter underscores the classic small-cap growth trap. 3C IT Solutions can generate impressive top-line numbers, but the underlying economics are fragile. The 1% net margin leaves no buffer against operational hiccups or a slowdown in collections.
The subsequent loss reported for H1 FY27 confirms this volatility. Investors are weighing whether the promised pivot to higher-value services can materialize before working capital demands overwhelm the modest profits. For now, the story is one of revenue potential constrained by profitability reality.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.