Vinyas (VINYAS) Q2 FY27 Profit Falls 35% as Capacity Expansion Weighs on Margins
The defence electronics manufacturer saw a sharp sequential decline in profitability, driven by higher interest and depreciation costs from its ongoing expansion.
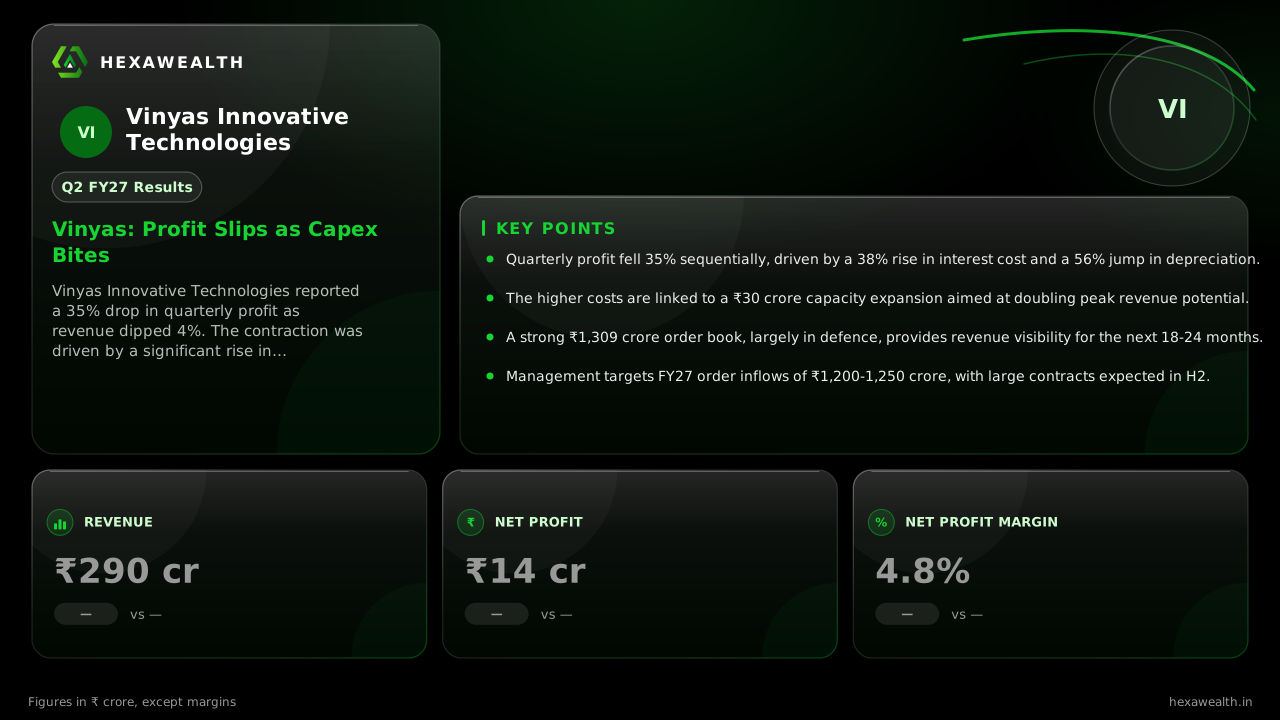
Vinyas Innovative Technologies reported a 35% drop in quarterly profit as revenue dipped 4%. The contraction was driven by a significant rise in interest and depreciation expenses linked to its capacity expansion.
For Vinyas Innovative Technologies, the September quarter was a step back from a strong finish to the previous fiscal year. The defence electronics specialist reported a sequential dip in both revenue and profit, with the bottom line squeezed by the costs of building for the future.
Revenue for Q2 FY27 stood at ₹290.25 crore, down 4% from the March quarter. Profit after tax fell more sharply, dropping 35% sequentially to ₹14.03 crore. The net profit margin compressed by 230 basis points to 4.8%.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 302.39
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 290.25
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 21.53
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 14.03
Revenue (₹ Cr)
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 302.39
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 290.25
Profit (₹ Cr)
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 21.53
- Profit (₹ Cr), Q2 FY27 (Sep 2026): 14.03
Net Profit Margin (%)
- Net Profit Margin (%), Q4 FY26 (Mar 2026): 7.1
- Net Profit Margin (%), Q2 FY27 (Sep 2026): 4.8
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ4 FY26 (Mar 2026) |
|---|---|---|
| Revenue (₹ Cr) | 290.25 | 302.39 |
| Profit (₹ Cr) | 14.03 | 21.53 |
| Net Profit Margin (%) | 4.8 | 7.1 |
The costs of building ahead of demand
The profit drop was not driven by a collapse in operations. Total expenses were flat, and employee costs fell. The pressure came from two specific lines: interest and depreciation. Interest expense rose 38% sequentially to ₹10.61 crore, while depreciation surged 56% to ₹5.7 crore.
This jump aligns with the company's significant capital expenditure program. According to SectorAlpha, Vinyas invested ₹35 crore in capex in FY26, which was 5.1 times its annual depreciation. A new 25,000 sq. ft. system-integration facility is a key part of this expansion.
A robust order book provides the runway
Despite the quarterly dip, the long-term growth story remains underpinned by a substantial order book. Management, in its May 2026 earnings call, reported an order book of ₹1,309 crore, executable over 18-24 months. SectorAlpha notes this is 2.5 times the company's FY26 revenue, with 85-90% coming from defence and aerospace.
Live Chart
· VINYAS
(BSE)
ISIN: INE0OLS01010
The company has guided for FY27 order inflows to be 25-30% above the FY26 level of ₹960 crore. It also anticipates large purchase orders in the second half of the fiscal year, which should support revenue growth ahead.
Key Points
- Quarterly profit fell 35% sequentially, driven by a 38% rise in interest cost and a 56% jump in depreciation.
- The higher costs are linked to a ₹30 crore capacity expansion aimed at doubling peak revenue potential.
- A strong ₹1,309 crore order book, largely in defence, provides revenue visibility for the next 18-24 months.
- Management targets FY27 order inflows of ₹1,200-1,250 crore, with large contracts expected in H2.
Hexa Perspective
The quarter shows the tension between investing for future growth and delivering near-term earnings. The margin compression is a direct cost of the capacity build-out, which aims to lift peak revenue capacity to ₹2,000-2,100 crore. For now, the stock trades at a slight discount to its industry PE, reflecting this near-term earnings pressure.
The investment case hinges on the timely conversion of its large order book and the successful ramp-up of new facilities. If order inflows meet guidance and the new capacity comes online without further delays, the current profit squeeze could be a temporary phase in a longer growth cycle. The key watchpoint is whether operating cash flow, which has been negative, begins to align with reported profits.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.