Vamshi Rubber (VAMSHIRU) Q2 FY27's Revenue Rebounds 50% but Costs Keep It in the Red
Vamshi Rubber's September quarter sales jumped sharply from a low base, but rising expenses and a heavy debt load kept the company in a net loss.
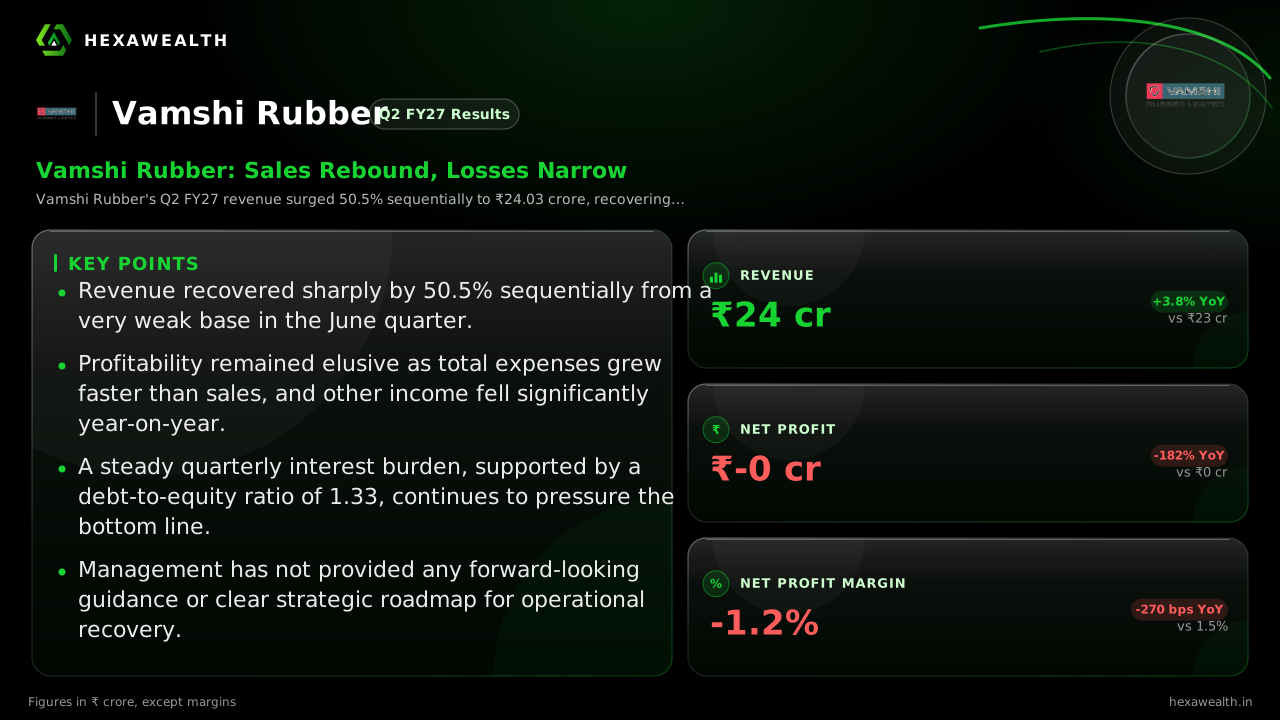
Vamshi Rubber's Q2 FY27 revenue surged 50.5% sequentially to ₹24.03 crore, recovering from a weak prior quarter. However, total expenses grew even faster, and a consistent interest burden led to a net loss of ₹0.28 crore.
For Vamshi Rubber, a manufacturer of tyre retreading materials, the September quarter was about recovering lost ground. After a sharp slump in the June quarter, sales bounced back, but the underlying strain from costs and debt kept profitability out of reach.
The numbers show a business in flux. Revenue for Q2 FY27 was ₹24.03 crore, a 50.5% jump from the prior quarter but only 3.8% higher than a year ago. The bottom line remained negative at a loss of ₹0.28 crore, though this was an improvement from the ₹0.74 crore loss in Q1.
Revenue & profit
Revenue (₹ Cr)
Profit (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 23.16
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 18.86
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 18.71
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 15.97
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 24.03
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.34
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 0.12
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 0.19
- Profit (₹ Cr), Q1 FY27 (Jun 2026): -0.74
- Profit (₹ Cr), Q2 FY27 (Sep 2026): -0.28
Revenue (₹ Cr)
- Revenue (₹ Cr), Q2 FY26 (Sep 2025): 23.16
- Revenue (₹ Cr), Q3 FY26 (Dec 2025): 18.86
- Revenue (₹ Cr), Q4 FY26 (Mar 2026): 18.71
- Revenue (₹ Cr), Q1 FY27 (Jun 2026): 15.97
- Revenue (₹ Cr), Q2 FY27 (Sep 2026): 24.03
Profit (₹ Cr)
- Profit (₹ Cr), Q2 FY26 (Sep 2025): 0.34
- Profit (₹ Cr), Q3 FY26 (Dec 2025): 0.12
- Profit (₹ Cr), Q4 FY26 (Mar 2026): 0.19
- Profit (₹ Cr), Q1 FY27 (Jun 2026): -0.74
- Profit (₹ Cr), Q2 FY27 (Sep 2026): -0.28
Net Profit Margin
- Net Profit Margin, Q2 FY26 (Sep 2025): 1.5%
- Net Profit Margin, Q3 FY26 (Dec 2025): 0.6%
- Net Profit Margin, Q4 FY26 (Mar 2026): 1.0%
- Net Profit Margin, Q1 FY27 (Jun 2026): -4.7%
- Net Profit Margin, Q2 FY27 (Sep 2026): -1.2%
| Metric | CurrentQ2 FY27 (Sep 2026) | PreviousQ1 FY27 (Jun 2026) |
|---|---|---|
| Revenue (₹ Cr) | 24.03 | 15.97 |
| Profit (₹ Cr) | -0.28 | -0.74 |
| Net Profit Margin | -1.2% | -4.7% |
The cost surge that ate the recovery
The sales rebound did not translate to profit because total expenses grew even faster, up 45.2% quarter-on-quarter. This suggests the company faced higher input costs just as production ramped up. A sharp 48.5% year-on-year drop in other income, as noted by StockFin.ai, also removed a cushion that had supported profits in the past.
A debt load that does not ease
A persistent drag is the interest expense, which has held steady near ₹0.45 crore per quarter. This points to a structural burden, with the company's debt-to-equity ratio at 1.33. MyWealthGrid.com flags a weak interest coverage ratio of just 1.5 times, meaning operating profits are barely sufficient to cover interest costs.
Management's silent stance
Notably, the company's management has provided no forward-looking guidance or commentary on a recovery plan. An analysis by StockFin.ai in October stated management had disclosed no new strategic initiatives or financial targets, leaving investors with limited visibility into a turnaround.
Live Chart
· VAMSHIRU
(BSE)
ISIN: INE380C01014
Key Points
- Revenue recovered sharply by 50.5% sequentially from a very weak base in the June quarter.
- Profitability remained elusive as total expenses grew faster than sales, and other income fell significantly year-on-year.
- A steady quarterly interest burden, supported by a debt-to-equity ratio of 1.33, continues to pressure the bottom line.
- Management has not provided any forward-looking guidance or clear strategic roadmap for operational recovery.
Hexa Perspective
The quarter reveals a business caught between cyclical demand and structural challenges. The sales bounce is a positive step, but it only returns revenue to levels seen a year ago. The real story is the margin squeeze from costs and debt.
With no management guidance and thin analyst coverage, the path to sustained profitability is unclear. Investors are left weighing a potential demand recovery in the tyre retreading niche against a balance sheet that offers little room for error. The next few quarters will show if sales can hold and if cost pressures finally ease.
Also read
Want this applied to your portfolio?
Talk to a HexaWealth advisor, or sync your mutual fund data for insights tailored to your holdings.